



PW Consulting: Combine Harvesters Market Poised for 4.5% CAGR, Reaching USD 180M by 2032

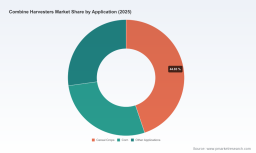
Combine Harvesters Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s latest Combine Harvesters Market study is designed as a strategic compass for executives, investors, and policy teams making critical decisions in 2026. Built on a transparent base year of 2025, a historical window from 2020–2025, and a forward-looking forecast through 2032, the research synthesizes primary-market interviews, manufacturer intelligence, and an econometric forecasting engine. At the macro level, the market expanded from USD 120.0 Million in 2020 to USD 145.0 Million in 2025 and is modelled to reach USD 180.0 Million by 2032, reflecting a compound annual growth rate of 4.5% across the forecast horizon. That steady, mid-single-digit growth masks critical inflection points—technology adoption, policy incentives, and shifting farm economics—that will determine winners and losers over the coming investment cycles.
Combine Harvesters Market
Why this study matters for 2026
-
Timing capital allocation. In an environment where OEMs and distributors are prioritizing digital and autonomy investments, precise, defensible market sizing and forward scenarios allow CFOs and corporate development teams to time CAPEX and M&A more effectively.
Combine Harvesters Market -
Designing profitable product roadmaps. Product leaders will find our mapped buyer journeys, feature willingness-to-pay curves, and operational cost profiles invaluable when balancing hardware complexity, software services, and aftermarket revenue strategies.
Combine Harvesters Market -
Mitigating supply and service risk. Dealers and tier-one suppliers can use our supplier risk matrix and field-service clustering to protect uptime and optimize parts inventory across diverse geographies and crop cycles.
-
Translating policy into market opportunity. With public programs and subsidy schemes influencing upgrade cycles, strategy teams can quantify which incentive structures accelerate replacement and which only reallocate demand.
What the report delivers — practical, transaction-ready outputs
-
Robust market model: Annual historicals (2020–2025) and dynamic scenario forecasts (2026–2032) that support sensitivity testing across price, adoption, and macroeconomic inputs.
-
Commercial segmentation framework: A replicable taxonomy that separates platform type, power class, and application use cases—built to be fed into go-to-market and product planning tools. (Core split datapoints are summarized in the full report to preserve segmentation granularity.)
-
Competitive heat maps: Comparative analysis across product capability (autonomy, throughput, fuel efficiency), brand positioning, distribution reach, and service economics—enabling M&A screening and partnership targeting.
-
Buyer economics and TCO models: Operator-level total cost of ownership scenarios under different utilization and labor-cost assumptions, plus cross-validated field survey inputs for maintenance and lifecycle cost drivers.
-
Scenario playbooks: Four executable market scenarios—Baseline, Technology Acceleration, Policy-Driven Uptake, and Downturn Resilience—each with tactical checklists for OEMs, lessors, and dealers.
-
Deal toolkit: Valuation multiples by capability cluster, integration risk checklists, and three near-term acquisition targets selected based on capability gaps, distribution fit, and aftermarket synergies.
Competitive landscape — reading the footprints of incumbents
The combine harvester market remains led by a mix of global OEMs that combine deep manufacturing scale with growing software and services businesses. Our competitive analysis focuses on strategic positioning rather than raw unit counts, allowing clients to assess where value creation will come from in the next five years.
-
John Deere (Moline, Illinois, United States) — Known for its high-integrated S-Series and X9 machines, Deere’s recent product highlights emphasize automation and operator-assist systems. The company is actively commercializing machine-sync and autopilot features, which create pathways to recurring software revenue and differentiated field productivity metrics.
-
CLAAS KGaA mbH (Harsewinkel, Germany) — CLAAS continues to leverage heritage models while scaling production and brand momentum. Milestones in production demonstrate manufacturing depth, and design continuity positions CLAAS to capitalize on premium segments and special edition releases that reinforce dealer relationships.
-
CNH Industrial N.V. (Amsterdam, Netherlands) — CNH’s high-power CR-series machines target large-scale operations and contractors. Their strategy emphasizes throughput and operating efficiency, which serves well in markets where consolidation of farm acreage and contractorization are accelerating.
-
AGCO Corporation (Duluth, Georgia, United States) — With brands such as Massey Ferguson and Gleaner, AGCO pursues a multi-brand approach to cover distinct channel segments, pairing global OEM capability with regional distribution expertise.
-
Kubota Corporation (Osaka, Japan) — Kubota’s strength in crop-specific solutions (notably in rice- and wheat-dominant regions) and investments in unmanned/autonomous prototypes position the company well in markets where labor constraints drive a premium for automation.
These OEMs are not just competing on metallurgy and horsepower. The strategic battlegrounds are increasingly software-integrated services, dealer experience, financing solutions, and parts availability. Our provider profiles include links to primary product pages and offer a concise view of each company’s strategic intent, R&D focus, and go-to-market mechanics.
Market dynamics shaping strategic choices in 2026
-
Technology and autonomy: Ongoing advances in sensor fusion, machine control, and AI-based harvesting support are altering the economics of labor and throughput. OEMs that move from one-off autonomy features to subscription-grade operational services position themselves to capture higher lifetime value per machine.
-
Labor pressures and service models: Persistent labor gaps in harvesting operations are driving demand for higher automation and new service models—custom-harvesting contractors, equipment-as-a-service, and pay-per-hour harvesting all look more viable under current farm labor dynamics.
-
Policy and subsidy levers: Public programs that incentivize eco-friendlier equipment upgrades are active levers in many markets. Strategic planning must therefore incorporate policy timing and eligibility rules to predict replacement cycles accurately.
-
Aftermarket economics: With field uptime critical to operator economics, dealers who optimize parts logistics and predictive maintenance programs can materially improve fleet utilization—and create differentiated, recurring margin streams.
-
Capital intensity and financing: High-capex assets require flexible ownership models. OEMs and captive finance arms that develop compelling lease and insurance offerings win share by reducing the adoption barrier for smaller operators.
Recent signals and what they imply
-
Market demand volatility: Industry sales reporting has recently signaled a sharp year-on-year sales contraction in certain retail channels. This underscores two realities: (1) inventory and dealer network management must be dynamic; and (2) short-term unit demand swings can mask structural growth in services and retrofit markets.
-
OEM product movements: High-profile product showcases emphasize small-property and rugged-terrain capabilities with integrated autopilot—indicating a deliberate push by tier-one players into smaller-acreage segments and more complex operating environments.
-
Manufacturing milestones: Production volume milestones reaffirm scale advantages but also highlight the importance of capacity planning and supplier diversification as manufacturers pursue both legacy and next-gen platforms.
How to use the report for immediate 2026 plays
-
For strategic planning: Use the scenario models to stress-test five-year product roadmaps against combinations of technology adoption rates and policy shifts. Identify the "minimum viable feature set" that secures aftermarket revenue without overloading initial hardware cost.
-
For commercial teams: Leverage our buyer segmentation and regional dealer mapping to rebalance inventory and prioritize field trials where adoption barriers are lowest and subsidy capture is highest.
-
For M&A and partnerships: Apply the deal toolkit and valuation ranges to rapidly screen targets that fill capability gaps in autonomy, precision agronomy, or distribution reach.
-
For operations and supply chain: Implement the supplier risk matrix and parts-availability scenarios to reduce downtime exposure and optimize spare-parts stocking across critical nodes.
Closing perspective
The combine harvester market in 2026 is at a crossroads: the headline growth is stable, but structural change is accelerating underneath. Executives who combine disciplined market models with targeted investments in software, service, and distribution will be best-placed to convert mid-single-digit market growth into outsized returns. PW Consulting’s Combine Harvesters Market study provides the layered, actionable insight you need to make those choices with confidence—while preserving the granular, proprietary segmentation and financial models that drive high-quality dealmaking and product planning.
To access the complete dataset, subsegment unpacking, and our customizable forecasting model, please visit the PW Consulting report page. Our team is available to translate the findings into a tailored strategic workshop or actionable M&A shortlist specific to your portfolio.
For detailed analysis of this topic, please visit the official page: Combine Harvesters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


