



PW Consulting: Cold Mix Asphalt Additives Market to Grow at 4.92% CAGR (2026–2032)

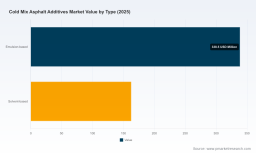
Cold Mix Asphalt Additives Market — Strategic Preview for 2026 Decision-Makers
PW Consulting's new market study on Cold Mix Asphalt Additives positions this segment as a quietly strategic inflection point for materials suppliers, pavement contractors, public works agencies, and investors in 2026. This preview outlines the study’s practical value for near-term corporate decisions, highlights the structural forces reshaping the competitive landscape, and signals where executive teams should concentrate scarce attention and capital. To preserve the report’s commercial integrity this article demonstrates analytical depth while intentionally omitting the granular segment-level tables and region-by-application splits contained in the full report—visit PW Consulting’s Cold Mix Asphalt Additives research page for the complete dataset and vendor scorecards.
Cold Mix Asphalt Additives Market
Why this market matters in 2026
-
Performance meets policy: Cold mix solutions lower the technical and environmental barriers to asphalt rehabilitation, enabling pavement work outside narrow hot‑mix windows and in remote or low-infrastructure settings.
Cold Mix Asphalt Additives Market -
Macro growth with tactical implications: The market has grown steadily from the 2020 base through the 2025 reference year and is forecast to expand across the 2026–2032 horizon at a compound annual growth rate of 4.92% (forecast period). In absolute terms the sector’s scale moves from mid‑hundreds (USD Million, base year 2025) toward a materially larger market by 2032—enough to justify dedicated product lines, supply‑chain investments, and targeted M&A for companies with regional reach or specialty chemistries.
Cold Mix Asphalt Additives Market -
Fragmentation and the premium opportunity: Concentration metrics show a market that is neither a monopoly nor fully commoditized (CR3 ≈ 37.5%, CR5 ≈ 45.2%). This structure creates a two‑track playbook: incumbent suppliers must defend formulation IP and logistics while emerging players can capture premium bio-based or performance-differentiated niches.
What the PW Consulting study delivers (practical contents)
-
Actionable market sizing and near-term forecasts calibrated to a 2025 base year and the 2026–2032 projection window, with scenario sensitivity around raw‑material volatility and regulation-driven adoption curves.
-
Supply‑chain maps and cost‑to-serve models that quantify margin sensitivity to petrochemical feedstock swings, emulsifier availability, and packaging/logistics tradeoffs—tools that allow procurement and finance teams to stress‑test contracts under realistic commodity scenarios.
-
Go‑to‑market playbooks tailored to three corporate archetypes (global chemical majors, regional formulators, and specialized bio‑additive challengers). Each playbook includes channel strategies, sample pricing ladders, and proof‑of‑value messaging for municipal and contractor buyers.
-
Regulatory compliance and risk playbook aligned to multi‑jurisdictional standards (EU REACH, California Proposition 65 analogs, and core Commonwealth frameworks), including a stepwise testing roadmap and estimated time/cost to registration by market.
-
Technology scouting and product roadmaps that evaluate polymer‑modification, bio‑based chemistries, and carbon‑sequestering innovations against durability, workability, and lifecycle‑cost metrics used by municipalities and national agencies.
-
Vendor benchmarking and an M&A target shortlist based on technology fit, geographic coverage, and scalability. The report includes a confidential scoring matrix used by corporate development teams to prioritize diligence targets.
Market dynamics you must factor into 2026 planning
-
Energy and emissions calculus: Cold mix approaches deliver substantial operational benefits versus conventional hot‑mix processes—independent studies show ambient‑temperature application can reduce energy consumption by roughly 35–50% and lower emissions by approximately 40–60%. For organizations evaluating total cost of ownership and sustainability commitments, those reductions materially affect procurement decisions, grant eligibility, and eligibility for green infrastructure funds.
-
Raw‑material volatility: Petrochemical feedstock and crude price swings directly influence the cost base for emulsifiers, amine anti‑stripping agents, and petroleum‑derived adhesion promoters. The net effect is asymmetric risk for formulators with high oil‑based input intensity and limited hedging capability; companies with diversified feedstocks or bio‑based options face less margin stress.
-
Regulatory lift and friction: Green procurement mandates in Europe, North America, and Oceania create demand pull for low‑emission cold mixes—but statutory regimes like REACH and California Proposition 65 also raise non‑trivial compliance costs. Cross‑border product launches must now budget for toxicology dossiers and extended testing timelines, which can extend commercial rollouts by quarters and increase go‑to‑market costs for smaller innovators.
-
Price vs. preference premium for sustainability: Bio‑based alternatives command a market premium—roughly on the order of mid‑teens to low‑twenties percent—reflecting both higher input costs and willingness‑to‑pay by public project owners that prioritize lifecycle emissions. Capturing that premium requires validated EPDs, field performance data, and third‑party certification in many jurisdictions.
Technology and innovation themes
-
Polymer modification is mainstreaming: Polymer‑modified cold additives are improving viscosity control and moisture resistance, enabling higher reclaimed asphalt pavement (RAP) incorporation without sacrificing early strength.
-
Bio‑based formulations are moving from demo to deployment: Recent product launches demonstrate commercialized polymer‑modified, bio‑derived additive systems capable of high RAP content and reduced VOCs—an important proof point for procurement teams that must reconcile sustainability targets with durability requirements.
-
Carbon‑sequestration adjuncts: Novel additions such as biochar show potential to sequester CO₂ within pavements while maintaining traffic durability—opening an adjacent value stream for suppliers able to validate long‑term carbon permanence.
Competitive snapshot — what leading vendors are doing
-
Arkema SA (Courbevoie, France) — Arkema’s ColdGrip® portfolio targets adhesion and moisture resistance by displacing water and promoting bond strength in cold patch applications. Their approach combines applied polymer chemistry with adhesion promoters to extend field service life, which is persuasive for municipal maintenance crews focused on patch longevity. Arkema’s global footprint and application engineering capability make them a credible incumbent for large contracts that demand technical support and supply continuity. (See company resources: https://www.arkema.com)
-
Cargill (Minneapolis, MN, USA) — Cargill’s Anova cold mix additives emphasize polymer‑modified, bio‑based formulations enabling high RAP incorporation, low VOC profiles, and year‑round application flexibility. Their emphasis on bio‑sourcing and supply reliability aligns with government buyers seeking lower‑emission solutions without sacrificing constructability. Cargill’s move into polymer-modified bio‑additives reflects commodity players capturing more value by layering formulation expertise on raw material supply. (See company resources: https://www.cargill.com)
Recent market signals and what they imply
-
Product innovation is accelerating: In mid‑2025 multiple vendors announced new formulations—ranging from polymer‑enhanced bio‑based additives to biochar‑infused mixes that claim CO₂ sequestration. These launches indicate an emergent bifurcation: performance‑first solutions that prioritize durability and logistics, and sustainability‑first solutions that leverage higher‑value procurement channels.
-
Procurement is becoming prescriptive: Public agencies increasingly require documented lifecycle emissions and validated product performance data, which raises the bar for entrants. The combination of green procurement preferences and regulatory compliance obligations amplifies the advantage of vendors who can invest in testing and certification up front.
Strategic implications and recommended next steps for 2026
-
Secure formulation IP or partnerships now. With mid‑single digit market CAGR and growing public procurement incentives, owning a differentiated chemistry—or a reliable licensing channel—will separate margin makers from volume players.
-
Invest in regulatory readiness. Budget for REACH/Proposition‑65 style dossiers and accelerated field trials where you want to compete; the time to first contract is increasingly gated by third‑party validation, not just price.
-
Hedge feedstock risk and de‑commoditize inputs. Consider dual‑sourcing strategies and incremental adoption of bio‑derived intermediates to reduce exposure to crude oil volatility while preserving cost competitiveness.
-
Pursue a two‑track product portfolio: one line optimized for low cost and rapid availability for contractor networks; a parallel premium line with certified sustainability claims aimed at municipal and green‑infrastructure budgets.
-
Use the PW Consulting vendor scorecard and M&A shortlist to prioritize inorganic deals that either fill regional distribution gaps or bring complementary chemistries into the fold.
How to use the full PW Consulting study
Executives preparing 2026 budgets should use the report to stress‑test scenarios across three vectors: cost volatility, regulatory timelines, and procurement demand elasticity for sustainability attributes. The study’s practical tools—cost‑to‑serve models, regulatory checklists, product roadmaps, and a confidential vendor scoring matrix—are designed to convert market intelligence into investment decisions within 60–120 days.
This article provides a high‑resolution view of the forces and decisions that will shape the cold mix additives landscape in 2026. For the complete dataset, segmented forecasts, confidential vendor scorecards, and downloadable decision tools, consult the full PW Consulting Cold Mix Asphalt Additives Market report. PW Consulting’s proprietary appendices contain the granular regional and application splits and the underlying assumptions that corporate strategy, procurement, and M&A teams will require to finalize action plans.
For detailed analysis of this topic, please visit the official page: Cold Mix Asphalt Additives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


