



Hemodialysis Concentrates Market to Reach USD 3,560M by 2032 — PW Consulting

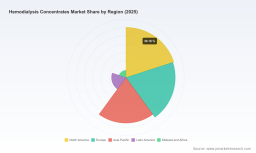
Hemodialysis Concentrates Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise, decision-focused preview of our Hemodialysis Concentrates Market study designed to inform executive choices in 2026. The market reached an estimated USD 2,350 Million in our base year (2025) after steady expansion from 2020, and our scenario modelling projects it to reach roughly USD 3,560 Million by 2032, reflecting a compounded annual growth rate of 6.2% across the 2026–2032 forecast window. These headline figures frame the commercial context; the full study supplies the granular segmentation, scenario tables and playbooks necessary for executable strategies. This article highlights why that intelligence matters and how senior teams should use it without disclosing the detailed segment-level figures reserved for the full report.
Hemodialysis Concentrates Market
Why this research matters for 2026 strategies
- Triage capital allocation: The market’s mid-single-digit CAGR signals durable demand — yet pockets of higher growth and margin exist. The report helps prioritize R&D and manufacturing capex toward those pockets so investment returns exceed the market average.
- Mitigate regulatory and quality risk: Recent Class 2 recalls and amplified quality scrutiny have made regulatory readiness a competitive differentiator; the report includes a regulatory-risk heatmap and remediation playbook.
- Decompress supply-chain vulnerability: Material-cost volatility and single-sourcing risk for medical-grade inputs require structured hedging and supplier strategies; our procurement models quantify trade-offs between cost, resilience and lead-time.
- Inform M&A and partnership decisions: An industry structure with concentrated market shares among leading players creates specific opportunities for bolt-on acquisitions, capacity deals and strategic alliances — the study ranks targets and synergies by ROI horizon.
- Commercial strategy optimization: Pricing, reimbursement and channel mix differ materially by setting (clinic vs home dialysis). The report combines reimbursement mapping with price-elasticity scenarios to guide contract negotiations and tender strategies.
What the full report contains — operational modules for immediate use
- Transparent market architecture: Historical sizing (2020–2025), forecast scenarios (2026–2032), and sensitivity analyses built on demand drivers and supply constraints. High-level market numbers are presented here; granular regional, type and application splits are available in the full dataset to support market-entry and valuation work.
- Segment playbooks: Actionable strategies for acid vs bicarbonate concentrates, premixed vs dry formats and clinic vs home care deployment — each with product, pricing and channel recommendations tailored to execution in 12–36 month horizons.
- Competitive benchmarking: Detailed company profiles, capability matrices, and a 360° view of R&D, manufacturing footprint, regulatory posture and commercial reach for primary market participants.
- Manufacturing and cost modeling: A factory-level cost model calibrated to medical-grade materials, water purification costs, labour and compliance overheads — enabling build vs buy decisions.
- Regulatory & quality playbook: Practical steps to meet evolving device and chemical quality expectations, FDA engagement templates, and corrective action frameworks influenced by recent recall case studies.
- Supply-chain resilience matrix: Supplier concentration scoring, inventory policy optimisation and contingency sourcing pathways for critical inputs.
- Commercial and reimbursement templates: Tender response playbooks, hospital and homecare contracting guides, and KPI dashboards for post-deal integration.
- M&A and partnership screening: A prioritized list of inorganic targets and partnership archetypes aligned to strategic growth paths — from bolt-ons for manufacturing scale to technology tie-ups for digital/IoT-enabled concentrates.
Market dynamics shaping 2026 decisions
- End-user demand drivers: Demographic trends, CKD prevalence and expanded home-dialysis programs underpin structural demand. The net effect is steady volume growth coupled with rising interest in solution formats that simplify administration and reduce clinic burdens.
- Format innovation and product differentiation: Single-use bicarbonate cartridges and other pre-measured delivery systems are reducing point-of-care complexity and contamination risk. These innovations change buying criteria, switching costs and lifecycle economics for providers.
- Quality and regulatory pressure: Multiple FDA Class 2 device recalls in recent periods illustrate that quality lapses are financially and reputationally costly. Organizations with robust quality systems and rapid corrective-action capabilities gain negotiating leverage and lower recall exposure.
- Cost and input volatility: Medical-grade water systems, electrolytes and acid components remain exposed to supply-chain bottlenecks and regional infrastructure constraints. The report quantifies how these input cost swings translate into gross-margin sensitivity by production model.
- Consolidation and concentration: The market exhibits a high level of concentration among leading players, reinforcing scale advantages in manufacturing, distribution and regulatory compliance. Our competitive index shows the top-three players command a substantial share of the market, with the top five controlling an even larger portion — an important consideration for new entrants and suppliers.
- Reimbursement and procurement complexity: Payer policies and procurement practices vary by jurisdiction, affecting the total addressable revenues realized by manufacturers. The study’s reimbursement appendix decodes major markets and identifies pragmatic pathways to favorable contracting.
Competitive landscape — strategic positioning of core players
- Fresenius Medical Care (Bad Homburg, Germany): A mature global manufacturer with integrated product-and-service offerings, recently advancing digital integration through a unified platform that facilitates concentrate-device interoperability. Their scale supports robust regulatory and distribution capabilities, making them a benchmark for competitors and potential partner or acquirer targeting clinical channels.
- B. Braun Melsungen (Melsungen, Germany): Positions concentrates within broader dialysis systems, leveraging system-level bundling to protect margins and retention. Their integrated approach raises entry barriers for standalone concentrate vendors seeking to displace incumbent suppliers in integrated clinics.
- Nipro Corporation (Osaka, Japan): Focused on machine-compatible concentrates and a strong presence in APAC markets. Their technical compatibility with regional device standards and emphasis on manufacturing quality make them a resilient competitor in price-sensitive markets.
- Rockwell Medical (Wixom, Michigan, USA): Innovator in single-use cartridges and dry/sterile formats, actively commercializing new product types and maintaining visibility through prominent conferences. Recent product introductions and trade-show activity demonstrate a playbook centered on technical differentiation and specialty channel penetration.
- Renacon Pharma (Karachi, Pakistan), Farmasol (Kayseri, Turkey) and Pollet Medical Group (Belgium): These players illustrate regional and vertical-integration strategies: local production scale, niche formulations and acquisition-driven expansion. The 2025 acquisition of Farmasol by Pollet Medical Group exemplifies consolidation aimed at securing supply and manufacturing capacity.
What this means for corporate strategy in 2026 — recommended actions
- Prioritize quality systems now: Invest in pre-emptive validation and traceability protocols. The cost of doing so is significantly lower than the combined financial and commercial impact of a recall.
- Diversify supplier and manufacturing footprints: Reconfigure sourcing to reduce single-point risks for medical-grade water treatment and key electrolytes; consider small-scale localized production to service home-care growth corridors.
- Accelerate format-led R&D: Allocate R&D spend to formats that reduce clinic time and contamination risk (e.g., single-use bicarbonate cartridges), as these command premium pricing in tender processes focused on total cost of care.
- Negotiate integrated value propositions: Bundle concentrates with ancillary services or device connectivity to capture higher-margin, longer-duration contracts with dialysis providers.
- Use M&A strategically: Target acquisition candidates that provide manufacturing scale, regulatory dossiers or geographic access rather than solely top-line accretion; the market’s concentration amplifies the benefit of scale-aligned deals.
- Embed scenario planning in procurement and pricing: Deploy the report’s sensitivity matrices to stress-test commercial plans against recalls, raw-material shocks and reimbursement shifts.
How PW Consulting’s study supports boardroom decisions
- We convert market dynamics into actionable options: where to invest, where to partner, and what to divest — each tied to quantified revenue and margin outcomes under multiple regulatory and supply scenarios.
- Our deliverables include ready-to-use slides and financial models for investment committees and M&A teams, plus operational checklists for manufacturing and quality leaders.
- We provide a tailored decision map for three archetypal players — global OEMs, regional manufacturers and pure-play concentrate specialists — so you can adopt the competitive moves most relevant to your role in the value chain.
This briefing is a strategic extract designed to demonstrate the depth and applicability of the full Hemodialysis Concentrates Market study. The dataset behind our headline market sizing, the segmentation by region, type and application, the company-level revenue and performance matrices, and the scenario-specific models are intentionally retained in the complete report to preserve their proprietary value and to enable secure client-level licensing. For executives preparing investment decks, procurement negotiations, product roadmaps or M&A diligences in 2026, the full report supplies the granular evidence and executable templates to move from strategy to measurable outcomes.
Hemodialysis Concentrates Market
Contact PW Consulting through our research portal to access the full report, licensing options and tailored advisory packages that translate these insights into a 12–36 month execution plan aligned to your risk tolerance and strategic objectives.
Hemodialysis Concentrates Market
For detailed analysis of this topic, please visit the official page: Hemodialysis Concentrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


