



PW Consulting: Leather Market to Reach USD 1,138 Million by 2032 at 6.5% CAGR

Leather Market 2026: Strategic Imperatives for Corporate Decision‑Makers
Executive preview
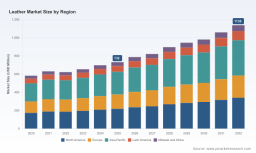
As companies set strategy for 2026, the leather sector sits at an inflection point. Our Leather Market study (base year 2025; historical window 2020–2025; forecast 2026–2032) quantifies both the resilience and the disruption potential of the industry. The global market expanded from a mid‑single‑hundred million base in 2020 to roughly USD 732 million by 2025, and our model projects a compounded growth trajectory (CAGR) of approximately 6.5% through 2032—reaching just over USD 1.13 billion by the end of the forecast horizon. These headline dynamics underline a market that is neither static nor hyper‑consolidated: our concentration metrics show modest top‑player share (CR3 ≈ 24%, CR5 ≈ 28%), indicating ample room for scale plays, vertical integration, and niche premiumization.
Leather Market
Why this matters for 2026 corporate choices
- Regulatory timing is forcing capital choices: With major regulatory changes phasing in during 2026–2027, procurement, compliance and product development budgets will need reallocation now to avoid disruptive retrofits later.
- Growth is material but selective: A steady mid‑single‑digit CAGR creates attractive returns for firms that combine cost control with differentiated product and traceability propositions; undifferentiated commodity players will face margin pressure.
- Fragmentation creates opportunity: The relatively low concentration enables M&A roll‑ups and bolt‑on strategies for manufacturers and distributors seeking scale or route‑to‑market acceleration.
Market trajectory and structural drivers
Our bottom‑up forecast layers demand drivers—luxury and premium footwear/fashion resilience, automotive and furniture cyclical rebounds, and expanding specialty applications—against supply‑side constraints including raw hide availability, energy and chemical cost volatility, and tightening environmental compliance. The net is a steady market expansion path that rewards operational excellence and compliance readiness. Crucially, the growth is not uniform: premium, traceable, and compliance‑certified leather grows faster than blended or low‑trace commodity offerings. For this reason, strategic positioning—premium vs. scale commodity—will determine share and margin trajectories through 2026 and beyond.
Leather Market
Regulatory and trade dynamics altering the playing field
- EU Deforestation Regulation (EUDR): The inclusion of cattle hides and prepared leather within EUDR scope (effective December 2026) fundamentally raises the bar for origin proof and due‑diligence across EU supply chains. Companies selling into or sourcing through Europe must operationalize traceability now.
- OEKO‑TEX and voluntary standards: Industry standards are pre‑empting regulation by demanding delivery‑level provenance documentation from slaughterhouses and tanneries—compliance can become a market access enabler, not merely a cost.
- Chemical restrictions: Recent revisions to REACH‑style restrictions in major markets (effective June 1, 2026 in the U.S. federal notices) require immediate reassessment of finishing chemistries and supplier declarations.
- Standards and national policy moves: Draft standards consultations (e.g., India's BIS) and promotional programs are reshaping how sourcing and export promotion are managed in key producing countries.
- Trade volatility: Short‑term export slippage (e.g., a modest decline in U.S. leather exports in FY26) demonstrates how geopolitics and tariffs can affect near‑term revenue and channel strategies.
Competitive landscape — strategic implications from leading players
The sector features a diverse set of competitors ranging from artisanal tanneries to global brand manufacturers. Key archetypes and strategic takeaways:
Leather Market
- Artisanal premium tanneries (e.g., Horween Leather Company): These firms command premium pricing through provenance, craftsmanship and consistent product performance. Strategy implication: invest in brand partnerships and small‑batch traceable supply chains to capture high margin pockets.
- Brand‑led footwear and apparel manufacturers (e.g., Wolverine Worldwide): Brand owners control downstream margins and have the leverage to demand supplier compliance and innovation. Strategy implication: focus on supplier scorecards, long‑term contracts, and collaborative R&D to secure preferred supply.
- Traditional finished‑leather manufacturers (e.g., Weinheimer Leder): Technical tanning expertise and process control are their competitive moats. Strategy implication: upgrade process automation, chemical use optimization and energy efficiency to defend margins under regulatory pressure.
- D2C premium goods (e.g., Saddleback Leather Co.): Direct channels and lifetime warranty models illustrate premium durability plays. Strategy implication: brands can monetize storytelling about provenance, and after‑sales services can extend customer lifetime value.
- Contract furniture and upholstery specialists (e.g., American Leather Holdings): Custom, high‑value segments remain attractive for specialised suppliers with fast customization capabilities.
- Large emerging‑market manufacturers and exporters (e.g., A.V. Thomas, Bhartiya International): Scale, labor efficiency and export focus drive growth. Strategy implication: these players are positioned to capture volume growth but must compress compliance and traceability costs to maintain competitiveness.
Recent industry signals to watch in 2026
- Design and export fairs (e.g., major international leather fairs and talent showcases) are accelerating innovation diffusion and buyer‑seller matchmaking—use these as a live market‑testing channel for product pilots.
- Regulatory submissions and consultations indicate near‑term tightening; treat policy news as leading indicators rather than background noise.
- Industry promotional funding moves—public agencies reallocating budgets to market development—create windows for co‑funded expansion into select markets.
What the full PW Consulting Leather Market report delivers (practical, executive‑ready content)
We designed the report to be actionable for boardrooms and operating teams. Highlights include:
- Revenue and demand models (2020–2032) with scenario sensitivities and a 6.5% central CAGR;
- Segment and channel analyses with decision trees for premium vs. commodity strategies (note: detailed segment line items and regional/application splits are intentionally withheld here to preserve the report’s strategic value);
- Proprietary supplier risk matrix and a traceability checklist you can apply to Tier‑1 and Tier‑2 suppliers;
- Regulatory compliance playbook (EUDR, chemical restrictions, voluntary standards), including a one‑page executive checklist for procurement and legal teams;
- Commercial playbooks—pricing levers, SKU rationalization templates, and retail vs. D2C margin simulations;
- M&A and partnership framework—target screens and integration checklists tailored to acquire scale or capability (e.g., tanning tech, finishing chemistries, traceability platforms);
- Ten actionable near‑term moves and a 24‑month roadmap to operationalize traceability, reduce chemical risk, and capture premium price realization.
Immediate actions for 2026 planning cycles
To convert the market view into decisions this year, companies should prioritize the following:
- Compliance audit within 90 days: Map supplier documentation against EUDR and OEKO‑TEX requirements; implement corrective action plans for any documentation gaps.
- Traceability pilot: Deploy a focused chain‑of‑custody pilot with a core SKU or product family to test data capture, verification and cost impact.
- Re‑price for compliance: Run margin sensitivity analyses that incorporate incremental compliance and testing costs and reprice contracts where indexation is feasible.
- Supplier diversification and contracting: Secure multi‑source arrangements for critical hides and negotiate clauses for shared compliance investments.
- Capex prioritization: Delay non‑strategic brownfield expansion; prioritize investments in finishing processes that reduce chemical exposure and energy consumption.
Monitoring dashboard for leadership
Track these KPIs monthly to maintain strategic control:
- Raw material availability and unit cost variance;
- Traceability compliance rate across active SKUs;
- Regulatory exposure index (jurisdictions + product lines affected);
- EBITDA margin by product family (pre‑ and post‑compliance cost);
- Order book conversion from premium categories vs. commodity categories.
Closing perspective and next steps
The leather market in 2026 is a study in managed transition: stable headline growth and fragmented supply create both runway and pressure. Companies that treat compliance, traceability and product differentiation as strategic levers—not just cost centers—will capture disproportionate share as buyers and regulators raise the bar. The full PW Consulting Leather Market report contains the segmented intelligence, supplier lists, procurement templates and valuation playbooks you need to operationalize these insights; this introduction purposefully omits detailed sub‑segment tables to preserve the report’s utility for subscribers and clients.
To convert insight into action, senior teams should prioritize a rapid compliance audit, a traceability pilot, and a supplier contracting review in Q1–Q2 2026. PW Consulting stands ready to accelerate any of these workstreams with bespoke modeling, vendor due diligence, and M&A advisory support.
For detailed analysis of this topic, please visit the official page: Leather Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


