



PW Consulting: Modular Data Centers to Hit USD 109.88B by 2032 at 17.11% CAGR

Modular Data Centers Market: Strategic Imperatives for Enterprise Decisions in 2026
Executive snapshot
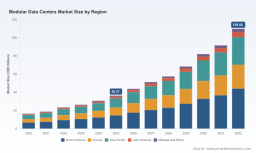
The modular data center market is entering a phase of accelerated maturation and strategic importance for enterprise IT and infrastructure planners. From a historical footprint that expanded from 16.51 Billion USD in 2020 to 36.37 Billion USD in the base year of 2025, our forecast shows continued rapid expansion through the 2026–2032 horizon—reaching 109.88 Billion USD by 2032 at a compound annual growth rate of 17.11% (revenue unit: Billion USD, currency: USD). For C-suite leaders and infrastructure decision-makers preparing 2026 budgets and roadmaps, this trajectory creates a set of discrete opportunities and measurable risks: speed-to-service, modular scalability for AI/HPC, supply-chain resilience, and regulatory and standards-driven compliance requirements.
Modular Data Centers Market
Why 2026 is an inflection point
- AI-driven demand intensity: The performance and density requirements of modern AI and HPC workloads are reshaping what “modular” must deliver—higher power density per rack, integrated liquid-cooling options, and factory-integrated IT stacks ready for rapid turn-up.
- Edge and distributed deployments: Enterprises and service providers are shifting from purely centralized builds to distributed modular footprints that reduce latency and expand availability while lowering time-to-market.
- Standards and safety converge: Recent updates to safety and performance frameworks (notably the revised UL 2755 outline for prefabricated modular systems) and community-driven standardization efforts such as Open Compute Project’s modular sub-project are creating clearer technical baselines—reducing vendor lock-in risk but increasing the compliance bar for providers.
- Commercial consolidation with room for niche leaders: Market concentration metrics show that the top three firms hold a meaningful share (~42.5% CR3) and the top five ~55.2% (CR5), signifying a landscape where scale matters but specialized capabilities and speed-to-market still create advantage for agile suppliers and system integrators.
- Supply-chain and construction economics: Prefabrication and factory-controlled fabrication reduce onsite labor and schedule risk in regions with constrained labor supply and logistics challenges—making modular deployments a preferred risk-managed route for many projects.
What PW Consulting’s Modular Data Centers Market study delivers
- Precision market sizing and a transparent forecast model (base year 2025; historical coverage 2020–2025; forecast 2026–2032) that incorporates demand drivers across cloud, colocation, edge, and enterprise segments.
- Practical decision frameworks for procurement, site selection, and vendor qualification that tie technical choices (cooling architecture, prefabrication level, power distribution topology) to financial KPIs.
- Vendor capability mapping and competitive scenario analysis—covering product roadmaps, integration risk, deployment velocity, and after-sales support models—structured to support RFP and pilot-selection processes.
- Regulatory and standards impact assessment (UL 2755:2025, OCP modular efforts) and a compliance checklist to accelerate approvals and insurance underwriting.
- TCO and ROI templates that model capex/opex trade-offs under different density, utilization, and energy-price scenarios—delivering an enterprise-grade view of breakeven horizons for modular versus traditional builds.
- A risk-adjusted route-to-deployment playbook that addresses supply-chain volatility, factory acceptance testing (FAT) best practices, and commissioning timelines for AI/HPC and edge workloads.
Note: The report contains granular segment-level data and proprietary split analyses that are not published in this prospectus. Access to the full dataset and interactive models is available via our research portal.
Modular Data Centers Market
Competitive landscape — strategic signals to watch
The modular market is being shaped by a mix of global infrastructure incumbents, systems integrators, and specialized modular fabricators. Strategic buyers should watch three broad vendor archetypes: scale integrators with end-to-end lifecycle services, engineering-centric suppliers with deep factory-prefab capabilities, and high-velocity providers focused on AI/edge time-to-service.
Modular Data Centers Market
- Vertiv (Lewisville, Texas) — Vertiv’s prefabricated modular solutions emphasize integrated power, cooling, and IT modules targeted at AI/HPC and high-density applications. Their modular megawatt-scale approach is designed for rapid scaling; enterprises targeting high-density clusters should evaluate Vertiv for turnkey performance and global service footprints.
- Schneider Electric (Boulogne-Billancourt, France) — Schneider’s EcoStruxure modular offerings prioritize adaptable designs for heterogeneous environments. Their strength lies in management integration and broad systems compatibility—an advantage for enterprises seeking a standardized control plane across multiple sites.
- ABB (Zurich, Switzerland) — ABB positions itself around modular, scalable solutions that accelerate colocation deployment and ROI. Their industrial automation expertise can be decisive where flexible power and distribution schemes are key to phased growth.
- Eaton (Dublin, Ireland) — Eaton’s SmartRack modular solutions marry rack-level integration with power and cooling enclosures. A recent product expansion (Jan 2026) in collaboration with Flexnode targeted rapid AI factory deployments, claiming significant compressions in deployment schedules—a strategic signal for buyers needing fast, validated rollouts.
- Flex (Sunnyvale, California) — Flex’s pre-engineered AI infrastructure platforms emphasize accelerated deployment timelines (vendor claims of up to ~30% faster delivery). Their strength is in manufacturing scale and integration velocity for compute, power, and cooling.
- Dell Technologies (Round Rock, Texas) — Dell’s modular approaches focus on modularized racks and integrated compute stacks for edge and high-density contexts, useful where vendor-managed compute and infrastructure lifecycle services are required.
- M.C. Dean (Alexandria, Virginia) — M.C. Dean brings specialized rack and overhead electrical configuration expertise and has strengthened its IP portfolio (patent issuance for a modular support rack system in mid-2026), making them an attractive partner for large campus or distributed installations with complex cabling and electrical requirements.
- Haskell Modular Solutions (Greenville, South Carolina) — Haskell’s factory-controlled fabrication model supports highly customized modular builds with predictable quality and shortened onsite schedules—an option for enterprises with bespoke site constraints.
Recent product and standards developments to factor into vendor selection
- Eaton’s January 2026 expansion (product collaboration with Flexnode) signals continued vendor focus on rapid AI deployment stacks and compressed schedule guarantees; buyers should insist on validated FAT outcomes and SLA-backed delivery timelines.
- Vertiv’s 2025 OneCore announcement highlights an industry trend toward modular architectures that scale from megawatt to hyperscale blocks optimized for AI/HPC; technical interoperability and cooling choices will define performance differentials.
- Siemens’ mid-2025 turnkey edge announcement underscores the growing marketplace for fully integrated, rapid-deployment edge modules suited to both permanent and interim operations.
- Regulatory and standards shifts (UL 2755:2025; OCP modular sub-project) are tightening the compliance envelope—enterprises should require vendor certification and third-party verification as part of procurement criteria.
Operational playbook for procurement and deployment in 2026
- Define workload-first requirements: quantify power-per-rack, expected scaling cadence, and service-level needs tied to application classes (AI training, inference, latency-sensitive edge services).
- Prioritize factory acceptance and modular integration testing: require FAT reports, documented thermal and acoustic performance, and validated interconnect tests for multi-module clusters.
- Embed standards and compliance clauses: ensure vendor commitments to current safety outlines and to any relevant OCP or interoperability frameworks.
- Contract for schedule and risk: include milestone-based payments, liquidated damages for deployment slippage, and options for phased scalability tied to business KPIs.
- Mitigate supply-chain volatility: diversify module suppliers for critical components, secure long-lead items under separate contracts, and evaluate local assembly hubs where lead times or logistics are constraining.
Financial considerations and TCO framing
With the market expanding at a high-teens CAGR and total addressable demand moving toward triple-digit billions by 2032, enterprises must reframe capital planning around modularity as a financial lever: faster time-to-service converts to earlier revenue capture or operational savings; factory-quality controls reduce rework and change-order risk; and standardized modules simplify long-term maintenance and part-procurement. Our report provides scenario-based TCO models that translate density, utilization, and energy-efficiency choices into payback timelines and NPV sensitivities—valuable inputs for 2026 capital allocation and site-portfolio strategies.
Key strategic questions for the C-suite in 2026
- Are we optimizing for speed-to-market (prefabricated/all-in-one modules) or for highest possible customization and futureproofing?
- How will our AI/HPC roadmap change rack-level power, cooling, and footprint requirements over the next 24–48 months?
- Do our procurement and contracting templates require updates to capture factory acceptance, interoperability certification, and regulatory compliance for modular systems?
- Which vendors align to our geographic, lifecycle, and service objectives—do we need vendor diversity to manage concentration risk?
- Have we stress-tested capital plans against the high-growth scenario reflected in market forecasts to 2032, and what is our phased investment trigger?
Conclusion: 2026 will be a year of decisive builds and strategic pilots. The modular data center market’s strong growth profile (17.11% CAGR across 2026–2032) and accelerating product innovation create an environment where early, well-structured decisions can materially alter an enterprise’s infrastructure cost curve and service agility. PW Consulting’s full Modular Data Centers Market report contains the segment-level insights, vendor scorecards, financial models, and procurement templates needed to convert the macro opportunity into executable 2026 programs. For access to the complete dataset, interactive models, and procurement playbooks, please refer to our research portal.
For detailed analysis of this topic, please visit the official page: Modular Data Centers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


