



PW Consulting: Boat Insurance Market Forecasted at 5.85% CAGR Through 2032

Boat Insurance Market — 2026 Strategic Prelude
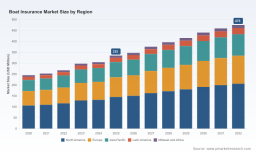
As organizations map their 2026 strategic agendas, the boat insurance segment presents a blend of steady expansion, concentrated competitive dynamics, and policy-driven inflection points that require deliberate, data-backed responses. PW Consulting’s latest market study — anchored on a 2025 base year and projecting through 2032 — positions the market at approximately USD 335 million in 2025 and forecasts growth at a compound annual growth rate (CAGR) of 5.85% over the 2026–2032 horizon, guiding the market toward roughly USD 475 million by 2032. This briefing synthesizes the strategic implications of those macro trends and previews the practical deliverables embedded in the full report, while intentionally reserving the granular splits and proprietary scenario outputs for subscribers.
Boat Insurance Market
Market trajectory: steady expansion with concentrated supply
Between 2020 and 2025 the market demonstrated durable expansion driven by a mix of recreational demand recovery and steady activity in commercial marine segments. That momentum continues into the forecast window and is underpinned by two structural features that will shape 2026 decisions.
Boat Insurance Market
- Growth momentum: The mid-single-digit CAGR reflects predictable, insurance-driven uplift rather than episodic boom — a profile that favors disciplined underwriting and incremental product innovation over speculative capacity expansion.
- Concentration dynamics: Market share is clustered among a small number of incumbents, creating a landscape in which three firms account for a majority slice of business while the top five extend that dominance further. These concentration metrics raise the stakes on distribution control, pricing power, and product differentiation for both incumbents and challengers.
Where demand and risk meet: drivers insurers must model in 2026
Underwriting profitability in the near term will hinge on how carriers adapt to four interlocking drivers:
Boat Insurance Market
- Climate and extreme weather exposure: Insurers face rising storm and surge volatility in coastal corridors. Reinsurance cost pressures and episodic losses are already being reflected in pricing actions across high-exposure geographies.
- Regulatory interventions: New state-level mandates altering minimum liability requirements or proof-of-insurance regimes will reshape addressable risk pools and distribution friction. For example, recent legislative activity in certain jurisdictions is increasing the minimum liability coverage required for certain classes of watercraft — a change that has immediate implications for product design and compliance workflows.
- Distribution evolution and consumer behaviors: Digital-first quoting, membership-based models, and bundling with auto/home lines continue to change customer acquisition economics. Average annual premiums for many recreational buyers remain modest, making scale and cost-to-serve a critical profitability lever.
- Segmentation of fleet economics: Commercial operations such as fishing and shipping display different loss drivers and lifetime values than the recreational segment; translating that into differentiated underwriting scorecards and premium architectures is a near-term imperative.
Competitive landscape: strategic postures and playbooks
The competitive field includes long-established multiline insurers, specialty marine underwriters, and nimble insurtech entrants. The incumbents’ public positioning and recent moves illuminate likely strategic plays for 2026:
- Large multiline carriers (digital scale + bundling): Organizations with established auto and homeowners footprints leverage cross-sell and digital quote engines to reduce acquisition costs. Expect continued focus on streamlined purchasing journeys and integrated policy bundles targeting customers whose boats are insured alongside other household assets.
- Specialty carriers and MGAs (product depth + bespoke underwriting): Firms that emphasize yacht and commercial vessel capabilities maintain underwriting flexibility, tailored endorsements, and loss-mitigation services. Their strength is customization for higher-value craft and complex liability exposures.
- Insurtechs and program managers (speed + niche focus): New entrants are proving the value of focused product innovation, rapid expansion into high-potential states, and partnerships with distribution platforms. Recent market moves show targeted geographic expansion into major boating markets and tailored admitted/excess capacity strategies.
Sample company archetypes reflected in the market: consumer-focused online quoters; fleet and commercial specialists; high-net-worth yacht underwriters; and membership-oriented providers leveraging partner underwriters. Each archetype implies different investment priorities — from scale-oriented digital marketing to actuarial investments in catastrophe modeling.
Regulation and pricing: tactical consequences for product teams
New regulatory actions imposing minimum liability limits or proof-of-insurance at registration points materially change the distribution environment. Where jurisdictions introduce mandatory liability thresholds, expect a structural uplift in addressable premium and administrative complexity around registration and enforcement. Simultaneously, data indicates that in coastal-intensive markets insured premiums are already experiencing meaningful upward pressure as reinsurers reprice catastrophe exposure. Together, these forces create both risk and opportunity: higher premiums can improve margins if loss ratios are managed, but they can also accelerate customer churn if carriers fail to articulate clear value.
Actionable playbook for 2026
Insurers and investors should prioritize a balanced program of quick wins and strategic investments. PW Consulting’s practical recommendations include:
- Short-term (0–12 months): Reprice exposures in high-frequency coastal corridors; launch targeted marketing for homeowners-to-boat cross-sells; implement claims triage automation to contain loss adjustment expense; and update compliance checklists for new state liability mandates.
- Medium-term (12–36 months): Invest in refined catastrophe and hull risk models, develop parametric storm cover options to accelerate claims payment, expand program distribution partnerships with marina groups and OEMs, and pilot telematics/usage-based endorsements for high-value recreational craft.
- Capital and reinsurance: Reassess reinsurance attachment strategies in light of rising coastal volatility; consider layered protections and alternative capital instruments to smooth earnings and support competitive quoting in peak seasons.
- M&A and partnerships: Use a market-concentration-informed approach to evaluate tuck-in acquisitions that enhance distribution or modeling capabilities; deploy minority investments to secure distribution exclusivity with tech platforms or membership organizations.
What the full PW Consulting study delivers — practical, executable intelligence
The depth of the full report is designed for decision-makers who need executable outputs rather than academic summaries. Highlights include:
- Proprietary market sizing and validated historical trajectory from 2020–2025, plus scenario-based forecasts to 2032 that stress-test demand under varying climate, regulatory, and economic permutations.
- Competitive playbooks and capability benchmarks tied to public and private players — mapping which organizations compete on price, product breadth, or service-led differentiation.
- Practical underwriting tools: scorecards, loss-driver matrices, and a claims-operations checklist tailored to recreational, commercial fishing, and commercial shipping classes.
- Regulatory impact models that quantify the operational and premium implications of recent and proposed state statutes, including proof-of-insurance mechanics and minimum liability changes.
- Pricing sensitivity and profitability dashboards that allow scenario toggling for premium elasticity, reinsurance cost shocks, and claim frequency shifts.
- M&A target shortlist and diligence templates keyed to market concentration dynamics, integration risk, and near-term premium accretion potential.
- Implementation roadmaps and KPI scorecards for the first 24 months post-launch of new products or distribution initiatives.
Strategic takeaways for 2026 planning
For executive teams setting 2026 priorities, our analysis yields three clear strategic imperatives:
- Control distribution economics. Scale-enabled distribution and low acquisition cost remain the strongest defensive moats. Whether by bundling, digital direct-to-consumer channels, or exclusive program agreements, reducing cost-to-acquire is a primary lever on 2026 P&Ls.
- Differentiated risk selection and product innovation. With premium pressure rising in exposed geographies, carriers that can segment more accurately, offer parametric options, or underwrite fleet exposures with precision will hold the margin advantage.
- Proactive regulatory readiness. Anticipate and operationalize around state-level liability changes and registration enforcement. Carriers that can seamlessly validate coverage at point-of-registration or offer compliant product wrappers will capture displaced buyers and reduce frictional churn.
Why this study matters now
As 2026 planning cycles compress, leadership teams need more than broad directional insight — they need templates, tested scenarios, and competitor intelligence that directly feed underwriting models and GTM plans. PW Consulting’s research is structured to convert market forecasts and concentration analytics into prioritized actions: where to reprice, where to underwrite, whom to partner with, and which regulatory shifts to treat as strategic opportunities rather than compliance costs.
For decision-makers seeking the underlying segment-level data, regional demand curves, and the full set of proprietary modelling outputs that informed this strategic synopsis, the complete report and its annexes contain the granular intelligence required to operationalize these recommendations. Access to those proprietary splits, scenario models, and deal-level diligence materials is available via our full report portal.
In an environment where policy change, climate exposure, and digital distribution converge, the 2026 winners will be those who translate macro trends into tight underwriting action plans, nimble distribution plays, and defensible product differentiation—before premium cycles force reactive moves. PW Consulting’s Boat Insurance Market study is designed to be that bridge from insight to execution.
For detailed analysis of this topic, please visit the official page: Boat Insurance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


