



PW Consulting: Security Screening Systems Market to grow at 7.8% CAGR (2026–2032)

Security Screening Systems Market: Strategic Imperatives for 2026 Decision‑Makers
As organizations and public agencies re-evaluate physical security postures in the wake of shifting threat vectors, the Security Screening Systems market is transitioning from point solutions to integrated, data‑driven platforms. PW Consulting’s new market research—anchored on a 2025 base year, a 2020–2025 historical window and a 2026–2032 forecast horizon—shows a market that expanded from roughly USD 6.0 billion in 2020 to USD 8.5 billion in 2025 and is projected to grow at a 7.8% CAGR into the decade, approaching the mid‑teens of billions by 2032. For executives making procurement, R&D, and partnership decisions in 2026, the implications are clear: scale matters, but speed, integration capability and governance will determine who captures value.
Security Screening Systems Market
Why this research matters for 2026 strategy
-
Timing and investment planning: The reported 7.8% CAGR and the multi‑year trajectory provide planning envelopes for capital and operating budgets. Whether you are an airport authority contemplating checkpoint CT rollouts, a border agency evaluating non‑intrusive inspection (NII) capacity, or a systems vendor prioritizing product roadmaps, these macro trajectories set fiscal guardrails.
Security Screening Systems Market -
Vendor selection and competitive dynamics: The market remains meaningfully fragmented (our concentration metrics indicate the top three and top five firms together do not dominate the market), which creates both procurement choices for buyers and M&A optionality for vendors seeking scale.
Security Screening Systems Market -
Operational integration risk: The next wave of procurements prioritizes not only detection performance but the ability to integrate AI analytics, remote screening workflows, and cyber‑secure data handling—capabilities that separate platform leaders from legacy equipment suppliers.
High‑level market anatomy (what we reveal — and why we withhold)
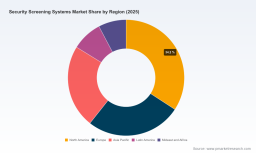
Our analysis synthesizes the market’s overall growth, vendor concentration, regulatory environment and technology adoption patterns to produce forward‑looking strategic guidance. To preserve the tactical value of the full study for subscribers and clients, granular splits by region, product and application are deliberately withheld in this summary. What we do make available here are the decisive market forces, real‑world supplier moves and practical decision frameworks that will shape procurement and investment through 2026 and beyond.
Key market dynamics shaping decisions in 2026
-
Technology convergence: Computed Tomography (CT), advanced X‑ray, millimeter‑wave (mmWave) imaging, and AI‑enabled analytics are converging into interoperable screening platforms. Buyers increasingly evaluate systems for throughput, false‑alarm reduction via AI, and remote screening capability that enables centralized interpretation centers.
-
Regulatory and safety constraints: Radiation and RF safety standards remain binding design constraints for suppliers and buyers. For example, X‑ray full‑body screening systems are governed by effective dose limits; mmWave solutions are subject to RF exposure standards. Procurement teams must bake compliance testing and documentation into RFP requirements to avoid deployment delays.
-
Procurement follows funding cycles: Public‑sector allocations—such as the 2026 federal budget priorities for checkpoint CT systems—create time‑bound windows for large procurements. Private venue operators and infrastructure owners similarly concentrate upgrades around financing and capital planning cycles.
-
Data governance and cross‑border operations: Remote screening and centralized image interpretation introduce complex privacy and cybersecurity requirements. Deployments that transnationally transmit imagery must reconcile local data protection laws and the security protocols of receiving agencies—an issue underscored by recent international remote baggage screening implementations.
-
Service and lifecycle economics: Buyers are shifting attention from capital cost alone to total cost of ownership—service, spare parts, software subscriptions including AI model updates, and cybersecurity patches drive lifecycle economics and supplier lock‑in.
Competitive landscape — what strategic patterns we observe
The vendor ecosystem comprises legacy industrial OEMs, specialized imaging firms, and software‑centric entrants. Strategic moves over the past 18 months highlight three themes:
-
Platformization by legacy OEMs: Established imaging leaders continue to extend hardware portfolios with AI and remote screening services, creating vertically integrated offerings to lock in long‑term service and analytics revenue.
-
Order flow and contract wins: Mid‑sized inspection specialists are capitalizing on high‑volume, near‑term procurements for cargo and vehicle inspection, underscoring the importance of a service footprint and rapid deployment capabilities.
-
Strategic alliances and consolidation: Expect continued JV formation and partnerships that pair imaging hardware with enterprise software and systems integration capabilities to offer turnkey detection ecosystems.
Illustrative vendor signals (recent developments and strategic implications)
-
Operationalized remote screening: A leading UK‑based OEM recently deployed an international Remote Baggage Screening System connecting airports and government agencies, demonstrating the operational feasibility—and compliance complexity—of cross‑border image transmission. For buyers and system integrators, this is a proof point for remote models; for privacy officers, it is a reminder to harden data protection and access controls.
-
Contract momentum among NII specialists: Several recent multi‑million dollar orders for cargo and vehicle inspection systems reflect durable demand from logistics and border security stakeholders. Vendors that couple hardware with rapid commissioning and local lifecycle support gain an advantage in these procurements.
-
Alliance‑driven product development: A newly announced joint venture between a systems integrator and an imaging specialist signals a trend toward combining enterprise software, analytics and advanced imaging technologies into unified offerings—shortening time‑to‑market for solutions that meet enterprise‑grade IT and security requirements.
Operational and procurement recommendations for 2026
-
Adopt a platform‑first evaluation: Prioritize suppliers offering modular, software‑driven architectures that decouple hardware refresh from analytics subscriptions. This reduces future rip‑and‑replace risk while enabling continuous performance improvements via AI updates.
-
Embed compliance and cyber in the RFP: Require demonstrable adherence to radiation and RF safety standards, and demand third‑party cybersecurity attestations and data‑handling procedures for any remote screening capability.
-
Model true lifecycle costs: Build TCO models that include software licensing, model retraining, remote monitoring, service SLAs and parts availability. Use scenario analysis to stress‑test budgets against higher‑than‑expected service demand and supplier consolidation risk.
-
Pilot with measurable KPIs: Shortlist vendors for pilot deployments with prespecified throughput, detection efficacy and false alarm metrics, plus operational KPIs for integration effort and latency for remote interpretation workflows.
-
Prioritize suppliers with local service networks: For border and cargo inspection, local commissioning and spare‑parts logistics materially affect uptime—an essential consideration when evaluating bids.
-
Prepare for procurement windows tied to public budgets: Map capital budgets and single‑point regulation changes (e.g., checkpoint CT allocations) to procurement timelines to avoid missing critical funding cycles.
Risk map — what could derail plans
-
Regulatory tightening: Changes in safety or data laws can increase compliance costs or necessitate hardware redesigns.
-
AI performance variability: Overreliance on vendor‑provided AI without in‑house validation frameworks can expose programs to detection degradation in the field.
-
Vendor concentration shifts: Although current concentration metrics indicate space for competition, selective consolidation or strategic partnerships could shift bargaining power and increase switching costs.
-
Supply‑chain and geopolitical constraints: Hardware components and cross‑border service models are sensitive to trade and export controls; contingency sourcing is prudent.
What the full PW Consulting study contains (practical deliverables)
The comprehensive report equips leaders with a playbook to act in 2026 and includes:
-
Detailed market forecast models and scenario analyses through 2032, with sensitivities tailored to funding, regulatory and technology adoption pathways.
-
Vendor scorecards and capability maps that assess imaging performance, AI maturity, service footprint, integration APIs, and cyber/data governance posture.
-
Procurement templates—RFP language, compliance checklists, pilot KPI definitions and TCO modeling templates—to accelerate decision cycles and reduce procurement execution risk.
-
Hands‑on guidance for pilots and scale deployments, including integration sequencing, data sovereignty playbooks, and governance frameworks for remote screening operations.
-
Strategic M&A and partnership playbooks outlining where scale, capabilities and geographic reach create the best value for acquirers and partners.
Concluding guidance — a practical checklist for Q1–Q2 2026
-
Map your immediate capital availability against the market’s growth trajectory and funding windows relevant to your sector.
-
Shortlist vendors based on integration readiness and evidence of operational deployments—not only lab performance.
-
Require transparent AI validation and an auditable data governance framework as non‑negotiable contract elements.
-
Plan pilots with rapid decision gates tied to measurable reductions in false alarms and lifecycle cost projections.
-
Assess M&A or JV opportunities to accelerate capability acquisition versus organic development where time‑to‑market is critical.
PW Consulting’s Security Screening Systems Market study provides the quantitative backbone and the executable playbooks to make those checklist items operational. For access to the full dataset—including regional and product breakdowns, vendor market shares, and downloadable procurement templates—consult the full report or contact our advisory team to arrange a bespoke briefing and scenario run for your organization.
For detailed analysis of this topic, please visit the official page: Security Screening Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


