



PW Consulting: Road Transport Refrigeration Market to Reach USD 6.65M by 2032 at 5.8% CAGR

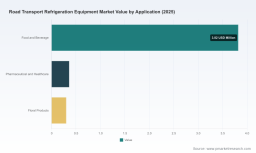
Road Transport Refrigeration Equipment: Strategic Imperatives for 2026 — A PW Consulting Preview
As global supply chains continue to recalibrate in the wake of pandemic-era disruptions, stricter emissions regulation, and accelerating electrification, the road transport refrigeration equipment (TRU) market is entering a decisive phase. PW Consulting’s upcoming market study—anchored on a 2025 base year and covering 2020–2025 historically with a 2026–2032 forecast horizon—frames that phase with actionable analysis for executives planning investments, fleet transition strategies, and product development roadmaps in 2026.
Road Transport Refrigeration Equipment Market
Why 2026 is a Strategic Inflection Point
-
The market has shown steady expansion: our assessment documents a compound annual growth rate (CAGR) of 5.8% across the forecast window, reflecting a combination of demand growth in perishables logistics, regulatory-driven replacement cycles, and uptake of electric TRU technologies.
Road Transport Refrigeration Equipment Market -
Underpinning that growth is a clear trajectory: the overall market value rises from the early-2020s baseline through the 2025 base year and continues upward into the early 2030s, validating multi-year investment for manufacturers, fleet operators, and service networks.
Road Transport Refrigeration Equipment Market -
Regulatory timelines and enforcement actions that become binding in 2025–2026 (notably state-level zero-emission mandates and refrigerant restrictions) create mandated replacement and retrofit windows. For many stakeholders, 2026 is the year to move from pilots and selective deployments to scaled rollouts or strategic hedging.
What This Preview Offers — and What It Withholds
We present a high-level synthesis of market dynamics, competitive posture, technology economics, and regulatory risk so that C-suite leaders and investment committees can prioritize decisions for 2026. Consistent with the “trailer” intent of this briefing, we deliberately omit the granular segmentation tables and proprietary split data that inform supplier selection, pricing negotiation, and site-by-site deployment economics. Those datasets and scenario models are available in the full PW Consulting report.
Key Market Dynamics Shaping 2026 Decisions
Regulatory Acceleration and Operational Impact
-
State-level emission regimes—most prominently California’s Transport Refrigeration Unit (TRU) Airborne Toxic Control Measure (ATCM) amendments—are moving from rulemaking into implementation. Amendments require progressively higher proportions of zero-emission TRUs in subject fleets by the end of 2025 and 2026, and CARB’s 2025 implementation updates broaden enforcement tools to include registration, reporting, and operating fees. The U.S. EPA’s partial waiver in early 2025 clarifies enforcement jurisdiction, reinforcing the practical force of these timelines.
-
Refrigerant policy is another lever: limits on global warming potential (GWP) for newly manufactured TRUs are already in force, pushing OEMs and aftermarket providers to validate lower-GWP chemistries or non-fluorinated alternatives in their platforms.
Technology Economics: Electrification vs. Diesel
-
Electric TRUs are moving beyond niche use. Operational modeling in our study shows that, on an hourly basis, electric systems consume measured electrical energy in the single-digit kW range versus diesel flow measured in fractions of a gallon per hour—yielding tangible hourly fuel/energy savings (we model average hourly savings that become compelling over total lifecycle horizons when paired with predictable electricity pricing and reduced maintenance).
-
However, total cost of ownership is context dependent. Charging infrastructure availability, route duty cycles, ambient extremes, and capital financing terms materially alter payback timelines. PW Consulting’s scenario engine quantifies break-even for common duty profiles; these outputs are a core deliverable in the full report.
Supply-Chain Volatility and Component Risk
-
Steel and other commodity inputs used in TRU housings and components are exposed to global metal-market volatility. Procurement strategies that previously focused on price are now being rebalanced to secure continuity of supply and minimize production lead-time risk.
-
For OEMs, this means dual-sourcing strategies, inventory buffering, and supplier partnership models tied to shared risk-reward metrics. For fleets, it justifies multi-vendor service agreements to avoid single-source downtime risk.
Competitive Landscape — Who’s Setting the Pace
The TRU market is characterized by a mix of long-established OEMs, regional specialists, and an expanding set of technology-focused entrants. Market concentration is moderate: the top three players account for a substantial share of the market, with the top five representing a clear majority—an environment where scale affords R&D and distribution advantages, but niche differentiation remains viable.
Profiles and Strategic Moves
-
Thermo King (Wood Dale, Illinois) : Continues to anchor its portfolio across diesel, hybrid, and all-electric TRUs. Recent launches targeted urban and light-duty segments with modular nose-mount solutions optimized for box trucks—an explicit play for last-mile and regional distribution fleets.
-
Carrier Transicold (Minneapolis, Minnesota) : Advances in reduced-maintenance, lower-operating-cost platforms signal a push to protect legacy diesel revenue while accelerating electrified product lines for center-divide trailer applications.
-
Guchen Thermo (China) : Expanding capability across diesel, electric, and battery-assisted TRUs for medium and heavy trucks positions Guchen for both domestic scale and export opportunities as global buyers seek competitive price-performance trade-offs.
-
Zanotti (Italy; Daikin subsidiary) : Focuses on refrigerated van and truck conversions with engineering depth in system integration—appealing to markets where retrofits and conversions remain cost-effective alternatives to full vehicle replacement.
-
Kingtec Group (US) and Hubbard Products (UK) : Both play crucial roles in complementary segments—trailers, RVs, and cold rooms—and demonstrate the importance of regional service networks and aftermarket parts availability.
Recent product introductions and sector benchmarks further crystallize market directions. Thermo King’s mid-2025 nose-mount unit responds to a growing demand for compact, precise-control systems in urban logistics. Carrier’s Vector 8811MT emphasizes lifecycle cost reduction—an explicit counterpoint to electrification narratives by retaining relevance for diesel-centric operators who prioritize uptime and maintenance economics. Industry benchmarking by the North American Council for Freight Efficiency (published in late 2024) provides the first independent efficiency baselines for transport refrigeration performance, enabling apples-to-apples comparisons and accelerating procurement discipline.
Practical, Actionable Guidance for 2026
For OEMs and Component Suppliers
-
Prioritize modular architectures: design platforms that can accept multiple powertrain options (diesel, hybrid, electric) and alternative refrigerants with limited airframe rework. This reduces the obsolescence risk tied to rapid rule changes.
-
Invest in service networks and digital diagnostics: reduced downtime and predictive-maintenance capabilities are increasingly decisive purchase criteria for large fleet operators.
-
Secure supply continuity: institutionalize commodity risk management and consider contractual hedges or long-term supplier agreements for critical metals and electronics.
For Fleet Operators and 3PLs
-
Shift from pilot mode to prioritized scaling by establishing a triage framework: identify routes and vehicle types where electric TRUs yield the shortest payback and prioritize those for conversion early in 2026.
-
Negotiate comprehensive service and performance contracts that align incentives for uptime, energy efficiency, and refrigerant stewardship.
-
Plan for compliance costs and administrative requirements: CARB-style registration, reporting, and operating fees necessitate new operational workflows and potential third-party compliance support.
For Investors and Strategic Buyers
-
Focus due diligence on software-enabled players and OEMs with clear electrification roadmaps and service ecosystems; these assets differentiate value beyond hardware.
-
Consider staged capital deployment tied to regulatory milestones and infrastructure rollouts to manage transition risk and preserve optionality.
What the Full PW Consulting Report Delivers
Beyond this executive preview, the full market study provides the operational detail required to execute 2026 strategies: market sizing and forecast models by vehicle type and application, supplier benchmarking with capability matrices, a scenario-based total-cost-of-ownership (TCO) engine for common duty cycles, regulatory impact models for major jurisdictions, and procurement playbooks for OEMs and fleets. Importantly, the full dataset includes the granular splits, unit shipment models, and pricing sensitivities that firms need to model deployment, yet are intentionally excluded from this preview to preserve the research’s proprietary value.
Final Advisory
For decision-makers planning 2026 investments, the message is clear: the TRU market is both growing and converging around a new set of success factors—regulatory compliance, electrification economics, service excellence, and supply-chain resilience. Acting early to secure the right mix of hardware, software, and partner agreements will convert regulatory risk into competitive advantage. PW Consulting’s full report equips executives with the data and playbooks to make those choices with confidence.
To convert this strategic preview into operational plans for 2026, stakeholders should prioritize scenario modeling tied to their specific route profiles, capital constraints, and compliance jurisdiction. Our team stands ready to run customized configurations derived from the full market dataset and to support procurement and fleet-transition roadmaps.
For detailed analysis of this topic, please visit the official page: Road Transport Refrigeration Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


