



Organic Cocoa Market to Reach USD 984M by 2032 with a 6.98% CAGR — PW Consulting

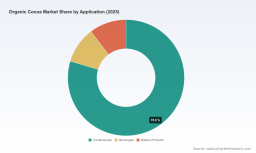
Organic Cocoa Market — Strategic Preview for 2026 Decision-Makers
As consumer demand for certified, traceable and sustainably produced ingredients intensifies, organic cocoa has moved from niche to strategic input for food manufacturers, ingredient traders and agribusiness investors. PW Consulting’s Organic Cocoa Market study (base year 2025; historical window 2020–2025; forecast period 2026–2032) synthesizes commercial realities, regulatory shifts and supply-side constraints into a pragmatic decision toolkit for 2026. This short briefing highlights the report’s strategic value, the principal market forces you must plan around, and the practical levers companies can deploy—while reserving the full, actionable segment and regional detail for subscribers.
Organic Cocoa Market
Market trajectory at a glance
-
Market scale and momentum: The organic cocoa market has expanded materially over the last half-decade — rising from roughly USD 452 Million in 2020 to USD 620 Million in 2025 (Million, USD, base year 2025). Our forecast model projects sustained growth through 2032, reaching an estimated USD 984 Million by the end of the forecast period.
Organic Cocoa Market -
Growth rate: The market’s compound annual growth rate (CAGR) for the forecast window (2026–2032) is 6.98%, reflecting a blend of premiumization, product adoption in value-added applications, and expanding certified supply chains.
Organic Cocoa Market -
Market structure: Concentration is material. The top three firms control a dominant share of the market, and the top five further consolidate supplier influence — dynamics that shape pricing power, certification access and buyer negotiation strategies.
Why this matters for 2026 strategy
-
Risk and opportunity confluence: 2026 will be the year when regulatory stringency, certification bottlenecks and premium consumer demand collide with structural supply constraints. Companies that prepare now can capture outsized margins in premium channels while avoiding supply disruptions.
-
Regulatory inflection points: European organic regulations and tightened audit and operator-group rules have increased compliance costs and raised barriers to market access for many smallholder producers. This accelerates consolidation and creates premium sourcing opportunities for supply chain players that can manage compliance end-to-end.
-
Traceability and provenance as premiums: Buyers increasingly pay for verifiable origin, regenerative practices and Fairtrade-style premiums. Investments in traceability and farmer engagement are no longer “nice to have” — they are required to defend shelf space in premium categories.
Key market dynamics shaping 2026 choices
-
Supply-side fragmentation vs. buyer concentration: Smallholder-dominated origins remain the backbone of organic cocoa production, but a significant portion of producer organisations currently struggle to meet new group-of-operators and segregation standards. This creates short- to medium-term supply squeezes for fully certified, audit-ready volumes.
-
Certification & development partnerships: Multilateral and development agency initiatives are actively reshaping the supplier base—partnering with cooperatives to upgrade governance, agroforestry practices and organic certification. These programs both expand long-term supply and create near-term winners among cooperatives that successfully upgrade.
-
Processing capacity and product mix: Processors with dedicated organic lines and segregated facilities capture higher-value volumes. Vertical integration—from bean sourcing through processing to ingredient sale—remains a primary route to margin capture and traceability assurance.
-
Premiumization of applications: While confectionery remains a core outlet, beverage, bakery and specialty ingredient applications are expanding demand for certified organic derivatives. Portfolio choices (e.g., focusing on butter versus powder versus liquor) and co-manufacturing partnerships dictate margin profiles.
-
Concentration risks: With a high CR3/CR5, buyer choices are constrained by a small set of large suppliers; strategic buyers should prepare contingency sourcing plans and invest in supplier development to reduce vulnerability.
What PW Consulting’s report delivers (practical, actionable)
-
Proprietary market model: An Excel-ready model projecting demand and supply across 2026–2032 with scenario toggles for price shocks, accelerated certification rollouts and attrition of smallholder volumes.
-
Decision-grade playbooks: Supply-side and commercial playbooks for manufacturers, ingredient traders and investors covering supplier due diligence, contract structures, and premium capture strategies.
-
Regulatory and compliance roadmap: A concise compliance checklist and timeline for EU organic regulations and audit readiness, including mitigation pathways for smaller suppliers and cooperative onboarding templates.
-
Risk matrix and stress-tests: Identified failure modes (regulatory non-compliance, climate-related yield shocks, logistics interruption) with quantified P&L impacts under three probability scenarios.
-
Supplier scorecards and sourcing tender templates: Practical templates to evaluate processors and cooperatives on traceability, segregation capability, certification maturity, processing capacity and commercial terms.
-
M&A and partnership pipeline: Candidate screening criteria and indicative value drivers for bolt-on acquisitions, joint ventures and long-form offtake agreements—tailored to capture premium organic value pools.
-
Sustainability KPIs and farmer engagement playbook: Pragmatic metrics and field interventions that drive yield uplift, reduce input costs through agroforestry and deliver certified volumes within defined timelines.
Competitive landscape: strategic implications for incumbents and challengers
The market features a mix of specialized organic traders/processors, global ingredient giants with organic lines, and mission-driven specialty brands. Each group faces different strategic choices:
-
Specialized organic processors and traders (e.g., firms focused exclusively on certified organic supply and processor integration) have the advantage in credibility and farmer relationships. Their strategic priority is scaling certified throughput without compromising segregation practices and audit trails.
-
Large global suppliers and agribusinesses use integration and procurement scale to securitize supply and offer wide product portfolios. Their strategic play involves investing in dedicated organic processing capacity and leveraging sustainability programs to secure long-term feedstock.
-
Premium chocolate brands and specialty ingredient companies win on provenance and consumer storytelling. For them, direct sourcing, transparency and premium positioning justify higher unit economics—but their scalability depends on securing reliable certified supplies.
Notable market participants exemplify these archetypes: established organic processors with direct farmer-cooperative sourcing; Swiss and European processors running large dedicated organic facilities; global agribusiness groups with segregated organic lines; and mission-first brands that monetize traceability. Competitive moves to watch in 2026 include capacity investments for segregated processing, expanded cooperative certification programs, and consolidation via selective M&A to secure certified volumes.
Priority actions for 2026 — a tactical roadmap
-
Secure certified throughput: Lock in multi-year offtake or forward purchase agreements with certified suppliers and cooperatives, coupled with supplier development clauses that underwrite certification upgrades.
-
Invest in traceability: Allocate budget for digital traceability pilots (blockchain or interoperable ledgers) tied to sustainability claims; convert traceability into price premiums and procurement leverage.
-
Segregation capacity & flexibility: Evaluate the economics of dedicating processing capacity versus contract manufacturing with certified partners. Short-term lease or tolling arrangements can reduce capital exposure.
-
Regulatory compliance program: Implement the report’s compliance roadmap immediately—focus on group-of-operators governance, audit-readiness and segregation controls to avoid market access loss, especially into Europe.
-
Scenario planning: Build three modular scenarios—“Certification Ramp-up,” “Origin Shock,” and “Premium Compression”—and stress-test P&L, working capital and logistics for each.
-
Partnerships with development agencies: Co-invest in producer organization upgrades and agroforestry programs (which often unlock matching donor or FAO-supported funds), de-risking supply growth and improving ESG credentials.
-
Value-chain integration assessment: For mid-sized players, run an M&A and build-vs-buy decision framework focused on acquiring processing capability or locking in origin relationships rather than commoditized bean trading.
-
Commercial segmentation: Define a two-track commercial approach—premium track (traceable, single-origin, regenerative) and scale track (cost-competitive, certified bulk)—with distinct margin models and sales channels.
How to use this research in the next 90 days
-
Immediate: Use the compliance checklist to audit your supplier base for EU readiness and identify high-risk contracts.
-
30–60 days: Run the report’s stress-tests on your procurement and hedging models; engage top suppliers on certification roadmaps and secure targeted offtakes.
-
90 days: Implement traceability pilots and finalize a prioritized shortlist for either capacity investment or M&A based on the report’s supplier scorecards.
Next steps and access to full detail
This briefing highlights priorities and strategic implications. PW Consulting’s full Organic Cocoa Market report contains the granular regional and application breakdowns, supplier-level benchmarking tables, model files and acquisition-target profiles necessary for transaction and operational execution. Core segment-level tables and regional splits have intentionally been omitted from this preview to preserve the commercial integrity of the analysis—subscribers receive the full dataset, downloadable models and customizable playbooks.
For executive briefings, model walkthroughs or to license the full dataset and templates, PW Consulting’s industry team is available to tailor the findings into a bespoke implementation plan for your organization’s 2026 priorities.
For detailed analysis of this topic, please visit the official page: Organic Cocoa Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


