



PW Consulting: Manual Motor Starters Market to Reach USD 857M by 2032 at 4.5% CAGR

Manual Motor Starters Market — Strategic Preview for 2026 Decision-Making
As companies map capital allocation and product roadmaps for 2026, understanding the structural forces shaping the Manual Motor Starters (MMS) market has become indispensable. This preview summarizes the strategic value of PW Consulting’s full market study and highlights the actionable intelligence executives must consider. The analysis is grounded in a comprehensive base-year assessment (2025) and a forward-looking forecast through 2032—presenting a clear growth trajectory and the competitive and regulatory constraints that will determine winner and laggard moves over the next investment cycle.
Manual Motor Starters Market
Market Trajectory: the Big Picture
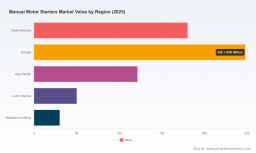
Between 2020 and 2025 the MMS market exhibited steady expansion from its historical trough to a 2025 baseline of USD 630 Million (base year 2025). Our forecast period (2026–2032) carries that momentum forward at a compound annual growth rate (CAGR) of 4.5%, taking the market toward the high hundreds of millions by 2032. This steady, mid-single-digit CAGR signals a market that is resilient, technically driven and amenable to incremental product and process innovation rather than explosive disruption.
Manual Motor Starters Market
For corporate strategists, the implication is clear: this is a market where scale, channel reach, and technical compliance matter. The pace of growth supports disciplined, ROI-focused investments—selective product line refreshes, targeted channel expansion, and operational efficiency programs—rather than large, speculative bets.
Manual Motor Starters Market
Why This Report Matters for 2026 Decisions
- Capital prioritization: The forecast establishes realistic revenue growth ceilings and informs NPV models for product investments, plant upgrades and geographic expansion through 2032.
- Portfolio optimization: The study identifies where incremental engineering spend will produce the highest commercial leverage—whether in ruggedized designs for harsh environments, compact starters for distributed automation, or cost-optimized variants for volume channels.
- Go-to-market clarity: Supplier and channel economics, buyer segmentation and procurement patterns in the report enable more precise commercial segmentation and tailored value propositions for 2026 tenders.
- Regulatory risk and compliance: The analysis consolidates standards and hazardous-location requirements that affect product certification timelines and cost to market.
Key Strategic Themes — What We Found
- Industrial stabilization with opportunistic modernization: Core demand is driven by ongoing replacement cycles and maintenance in mature industrial segments. There is a parallel premium segment growth opportunity for starters that combine manual simplicity with clearer fault indication and modularity to fit compact panels.
- Regulation and safety are competitive levers: Compliance with IEC/UL regimes is table stakes; products that demonstrate higher short-circuit breaking capacity and hazardous-location certification capture premium placements in critical infrastructure and petrochemical projects.
- Serviceability and diagnostics matter: Buyers increasingly prize starters with visible fault indication and simplified field servicing. This trend favors suppliers who bundle aftermarket support and digital-enabled diagnostics without excessive cost inflation.
- Channel-led volumes vs. specification-led projects: Distinct go-to-market plays exist—one focused on distribution and rapid replenishment for maintenance spares, the other on engineered sales for process-critical installations. Successful players maintain dual capability.
- Pricing dispersion creates space for differentiated value capture: Average selling prices for industrial-grade manual motor starters range broadly (industry observations put a working range around USD 150–450 depending on rating and protection features). This spread enables premiumization for compliance and performance while permitting low-cost volume plays.
Competitive Landscape — who matters and how they play
The MMS market is moderately consolidated: the top three suppliers account for a meaningful minority of the market, while the top five approach half the market. Such concentration levels reward operational excellence, but also leave room for regional specialists and focused challengers to prosper. Below we distill strategic positioning across the leading vendors covered in the study.
- ABB (Zurich, Switzerland) — Offers compact, protection-focused series that blend thermal-magnetic protection with robust short-circuit ratings. ABB’s emphasis on specification-level performance (including high short-circuit breaking capacities) positions it for safety-critical projects and high-reliability industrial accounts.
- Schneider Electric (France) — Maintains a broad portfolio with recent catalog refreshes that emphasize modularity and ease of selection for system integrators. Schneider’s brand strength in control and automation creates cross-sell leverage into broader motor management solutions.
- Eaton (Dublin, Ireland) — Offers a mix of industrial and commercial starter lines with deep distribution reach. Eaton’s strategy focuses on channel depth, parts availability and the ability to serve high-volume maintenance replenishment needs.
- Siemens (Germany) — Competes on engineering pedigree, integration with automation stacks and product robustness. Their offerings are attractive in high-specification projects and OEM relationships.
- NOARK Electric (USA) — An agile challenger with product releases that emphasize built-in fault indication and competitive price-to-performance. Recent product introductions signal an intent to gain share in distribution-led segments.
- Fuji Electric (Japan) — Leverages compact, reliable product designs often specified into industrial OEMs and regional infrastructure projects.
- Appleton Electric (USA) — Differentiates through factory-sealed, hazardous-location starters that address Class I Division 1/2 applications—an attractive niche with higher margins and slower cyclicality.
- LS Electric (South Korea) — Focuses on cost-competitive solutions that can be localized by regional partners and distributors.
Recent industry moves reinforce these dynamics: NOARK’s mid‑2025 introduction of the Ex9S80 underlines appetite for expanded fault-indication features in compact form factors, while Schneider’s late‑2025 catalog refresh highlights continued investment in modular starter platforms. These tactical advances translate into strategic positioning that we analyze in detail in the full report.
Regulatory, Technical and Cost Constraints
- Standards and safety: Manual motor starters are electromechanical devices governed by IEC and UL standards for isolation, control and overcurrent protection—compliance timelines and certification costs affect time-to-market and margins.
- Hazardous-location requirements: There is a persistent premium for devices certified for hazardous locations (e.g., factory-sealed designs suitable for Class I Division 1/2). Suppliers that can cost-effectively certify and supply these lines benefit from durable project pipelines.
- Short-circuit performance: Manufacturers routinely validate short-circuit breaking capacity up to high levels (industry product documentation cites capacities up to ~100 kA at 400 VAC). Achieving and documenting those capabilities impose engineering and test-lab costs that smaller suppliers may struggle to amortize.
- Component and raw-material volatility: Component supply and metallic raw-material pricing can widen the ASP dispersion and compress margins; disciplined procurement and multi-sourcing strategies are therefore essential for 2026 resilience.
What the PW Consulting Report Contains — Practical, Transactional and Tactical
The full study is constructed to be immediately actionable for strategy teams, product managers and commercial leaders. Key deliverables include:
- Market sizing and validated growth scenarios (historical 2020–2025 baseline and 2026–2032 forecasts with sensitivity ranges).
- Segment-by-segment demand drivers and crosswalks to capital expenditure cycles in heavy industry, utilities and process manufacturing.
- Detailed buyer persona and procurement-process mapping for maintenance, OEM and project-spec buyers.
- Channel economics and distribution playbooks, including margin stacks and stocking models for tiered distribution.
- Competitive benchmarking with product-level feature comparisons and go-to-market strategies for the leading suppliers.
- Regulatory compliance matrix and certification timeline playbook for hazardous-location and high short-circuit applications.
- Pricing architecture and ASP sensitivity scenarios to test margin preservation strategies under raw-material volatility.
- M&A and partnership screening—targets, valuation heuristics and integration risk flags for market consolidation opportunities.
- Implementation roadmap and 90/180/365 day playbooks tailored to market-entry, product-refresh and channel-execution initiatives.
How Executives Should Use This Intelligence in 2026
- Prioritize product investments that reduce total cost of ownership for buyers (serviceability, modular spare parts, fault indication) rather than feature arms races.
- Calibrate distribution footprint: emphasize fill-rate and rapid dispatch in maintenance-heavy channels while supporting engineered sales motions for project and OEM accounts.
- Validate certification pipelines for hazardous and high-short-circuit applications early in the product development process to avoid costly delays.
- Use the report’s pricing sensitivity models to stress-test ASP strategies under different raw-material and supply scenarios.
- For M&A-minded executives, leverage the concentration profile: identify targets that provide either distribution reach or niche certifications rather than broad product overlaps.
PW Consulting’s full Manual Motor Starters Market report provides the datasets, dashboards and scenario tools that translate these strategic recommendations into executable plans. The preview you have here is intentionally strategic—designed to surface the conclusions and the decision levers. The full report contains the segment tables, granular regional and application splits, product-level feature matrices and downloadable datasets required to underpin board-level investment decisions.
Next Steps
If you are preparing budgets, capex plans or product roadmaps for 2026, access to the full dataset and the interactive forecast model will materially reduce execution risk and accelerate time-to-value. The complete study contains the granular segmentation and pricing tables, vendor scorecards and the custom scenario workbench that senior teams use to finalize investment cases.
Contact PW Consulting to obtain the full report and the accompanying model. Our advisory team can also run a tailored workshop to translate market scenarios into a prioritized 18‑month action plan aligned to your portfolio and channels.
For detailed analysis of this topic, please visit the official page: Manual Motor Starters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


