



PW Consulting: Germanium Market at USD 320M in 2025, poised for 3.5% CAGR to 2032

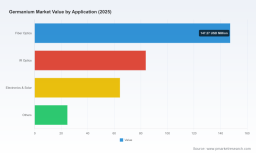
Germanium Market 2026: Strategic Imperatives from PW Consulting’s Market Outlook
As critical minerals rise toward the top of corporate and national security agendas, germanium has moved from niche specialty to strategic input for fiber optics, infrared optics, semiconductors, and next‑generation solar technologies. PW Consulting’s Germanium Market study—anchored on a 2025 base year and extending through 2032—translates raw data into decision frameworks. Our core macro finding: the global germanium market has expanded from a modest revenue base in 2020 to a substantially larger market by 2025, and is forecast to continue growing through 2032 at a compound annual growth rate (CAGR) of 3.5% under our central scenario. This report is designed to help executives convert that trajectory into concrete procurement, investment, and geopolitical risk decisions in 2026.
Germanium Market
Why this report matters for 2026 corporate strategy
-
Procurement resilience: With supply‑side policy shocks becoming more frequent, procurement teams need multi‑vector sourcing roadmaps and contract structures that reflect tight supply buffers and higher volatility.
Germanium Market -
Capital allocation: Investors and corporate development teams require forward‑looking scenario analysis to decide on capacity expansions, recycling investments, and M&A targets in an environment of rising strategic support for domestic production.
Germanium Market -
Product roadmaps: R&D and product groups must assess material design choices (e.g., germanium‑containing vs. alternative materials) against cost curves and supply risk profiles to prioritize development timelines.
-
Regulatory and geopolitical planning: Supply disruptions driven by export controls and trade measures require playbooks that align lobbying, contingency sourcing, and domestic production incentives.
High‑level market trajectory (what the macro data tells us)
Our top‑line market sizing traces a steady recovery and expansion: the market value moved up between 2020 and 2025 and, under the central forecast, continues to trend upward through 2032. The CAGR of 3.5% across the 2026–2032 forecast window points to a market that is growing steadily rather than explosively—creating strategic opportunities that reward early, targeted moves rather than reactive catch‑up plays. Importantly, market concentration metrics show a moderately consolidated supplier base (CR3 at roughly one‑third of market share and CR5 approaching half the market), which amplifies the impact of individual supplier moves and policy levers on global availability and pricing.
Key market dynamics shaping 2026 decisions
-
Policy and trade: Since 2023, export licensing and direct export restrictions from major producing countries have reframed supply risk. Complementing these controls, a series of policy instruments enacted elsewhere—ranging from executive orders to tariff measures—are accelerating government‑backed incentives for domestic processing capacity. Together, these trends increase the strategic value of near‑term investments in localized refining and recycling.
-
Price volatility: Recent market developments demonstrate pronounced price volatility. Buyers should assume a higher base price environment and build hedging and contract flexibility into purchasing strategies. Our scenarios quantify upside price shocks and the economic thresholds at which demand substitution or accelerated recycling becomes viable.
-
Supply augmentation and substitution: Private and public capital are already moving to expand capacity and recycling. Notable capacity expansions and strategic acquisitions in early 2026 indicate escalated efforts to secure domestic primary and secondary sources—actions that will gradually relieve pressure but require multi‑year timelines.
-
Technological and demand shifts: Applications across fiber optics, IR optics, and electronics/solar continue to drive end‑use demand. Small shifts in adoption rates across these verticals can have outsized effects on Germanium balances given overall market scale and concentration dynamics.
Competitive landscape — who matters and why
The market’s competitive set is a mix of integrated primary producers, refiners/recyclers, and specialty materials firms. Key players include established miners and refiners with integrated value chains, as well as specialty manufacturers and recyclers that can rapidly scale purified product flows. Recent corporate moves—capacity expansions in North America, offtake agreements linking recycling technologies to downstream processors, and the transfer of primary asset ownership—have shifted the strategic map in ways that matter for buyers and investors.
-
Integrated primary producers with upstream access maintain strategic leverage over raw flows and are obvious partners or targets for downstream players seeking security of supply.
-
Refiners and recyclers that can produce high‑purity germanium act as swing suppliers in constrained markets; investments in recovery technology and offtake partnerships materially change availability over a multi‑year horizon.
-
Specialty manufacturers and compound producers retain commercial advantages where proprietary processing yields differentiated product forms or lower contamination risk—critical for semiconductor and optical applications.
Report contents — what executives will find inside
This study blends market intelligence, structured scenario analysis, and practical playbooks to support immediate and medium‑term decisions. Highlights include:
-
Market sizing and demand modeling from 2020 through 2032, including a central forecast and two alternative scenarios for upside and downside demand/policy outcomes.
-
Supply‑side analysis that maps primary, secondary, and emerging recovery channels; a supplier matrix with operational footprints and capacity indicators; and concentration metrics that identify single‑point risks.
-
Price‑formation framework and sensitivity testing: an operational model that ties raw supply shocks and policy shifts to end‑market price responses across our forecast horizon.
-
Regulatory and geopolitical risk assessment, with stress‑test outcomes under different trade restriction and subsidy regimes.
-
Transaction and operational playbooks: M&A screening criteria, JV templates, recycling investment cases, procurement contracting checklists, and capex prioritization matrices.
-
Proprietary datasets and dashboards: time‑series market values, demand drivers by application group, supplier profiles and recent corporate developments, and an executive heatmap of near‑term supply risks.
Practical implications and recommended actions for 2026
Translate insight into prioritized action across three horizons:
-
Immediate (0–6 months): Run a supplier‑risk audit, secure staggered offtake contracts with optionality, and fast‑track small‑scale recycling pilots to create a local buffer. Update procurement KPIs to incorporate geopolitical risk scores and supplier concentration exposure.
-
Near term (6–24 months): Pursue strategic partnerships with refiners or recyclers, evaluate targeted bolt‑on acquisitions to de‑risk supply, and model product redesign options where substitution can be achieved without degrading performance.
-
Medium term (2–5 years): Consider greenfield refining or shared regional assets with public or private co‑investors where strategic national policy supports domestic capacity; integrate advanced recycling and recovery technologies into core materials strategy.
How PW Consulting’s intelligence changes the odds
Our analysis does not simply report historical trends—it quantifies the levers that matter in 2026: policy shifts, supplier capacity moves, recycling scale‑up, and demand elasticity across end markets. Clients using our models can run bespoke scenarios that answer questions such as: At what price threshold does demand pivot toward substitution? Which supplier disruption scenarios create systemic shortage risk? Where is it optimal to invest in domestic capacity versus signing long‑term offtake contracts?
What we intentionally leave for report access
Consistent with the “trailer” principle behind this overview, we have showcased the analytical architecture and strategic utility of the study while preserving the report’s granular datasets and proprietary split tables for subscribers. The full report contains downloadable tables, regional and application breakdowns, supplier share matrices, and financial models for immediate use by procurement, corporate development, and strategy teams.
To convert these insights into operational advantage in 2026—securing supply, optimizing capital allocation, and managing policy risk—access the full PW Consulting Germanium Market study and datasets on our website. The complete product provides the granular segmentation, supplier scorecards, and model inputs necessary to execute the playbooks outlined above.
For detailed analysis of this topic, please visit the official page: Germanium Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


