



PW Consulting: Car Amplifiers Market to Hit USD 620.9 Million by 2032 at 7.0% CAGR

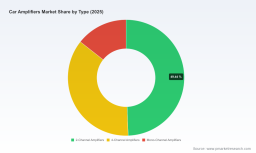
Car Amplifiers Market — 2026 Strategic Preview
Opening Frame: Why this preview matters for 2026 decision cycles
As companies reallocate R&D, manufacturing, and commercial resources for the post‑pandemic recovery, the car amplifiers market sits at an inflection point. PW Consulting’s latest market research — built on a 2020–2025 historical base and a 2026–2032 forecast horizon — provides the empirical ballast that boards and executive teams need to make confident bets in 2026. The headline mathematics are clear: the market expanded from roughly 302.5 million USD in 2020 to about 386.3 million USD in 2025, and our model projects growth to approximately 427.9 million USD in 2026 and toward 620.9 million USD by 2032 at an underlying CAGR of 7.0% for the forecast window. These macro dynamics are the starting point; the strategic value of the full study is in turning that trajectory into defensible commercial choices.
Car Amplifiers Market
Market snapshot and interpretive headline risks
Historical momentum through 2025 reflects two structural forces: continued aftermarket demand for high‑performance audio and deeper OEM integration of premium audio systems. Looking ahead, growth is driven by product premiumization (DSPs, class‑D efficiency gains, and multi‑channel solutions), tighter testing and verification expectations, and evolving vehicle architectures that place new constraints and opportunities on amplifier design. At the same time, market concentration metrics indicate meaningful scale advantages: the top three players command over half of the market, and the top five approach three quarters. This concentration amplifies the strategic importance of brand, OEM relationships, and validated performance claims.
Car Amplifiers Market
At the policy and standards layer, voluntary but widely referenced testing standards continue to shape buyer trust. Updated testing protocols and independent verification—alongside vendor certifications—are becoming de‑facto entry hurdles for premium segments. For manufacturers and investors, the interplay of certification, verified performance, and perceived product quality will increasingly determine which platforms secure OEM slots and which secure long‑term aftermarket loyalty.
Car Amplifiers Market
What corporate leaders will find immediately useful in this research
- Proven, audit‑ready market sizing and forecasting model that links macro fleet and vehicle mix trends to amplifier demand drivers.
- A supplier benchmarking framework that ranks vendors across technology (DSP, thermal, EMI, class architecture), OEM traction, aftermarket distribution effectiveness, and validated performance certifications.
- Modular go‑to‑market playbooks for OEM engagements, specialist aftermarket channels, and direct‑to‑consumer premium strategies.
- Operational intelligence: component cost build‑ups, typical BOM margins by product architecture, and manufacturing footprint tradeoffs informed by labor‑and‑supply realities.
- Scenario and sensitivity analyses — including upside/downside cases tied to regulation, certification changes, and raw‑material price shocks — with actionable trigger points for M&A and capacity decisions.
Competitive landscape — who matters and why
The market is populated by a mix of legacy electronics majors, audio‑specialist independents, and OEM‑facing Tier 1 groups. Each cluster pursues a distinct strategic play:
- Premium independents (examples included): position on audio fidelity and lifestyle cachet — often supporting marine‑rated or specialty vehicle integrations and leveraging brand equity in enthusiast channels.
- Performance brands: focus on power density, thermal management and demonstrable peak output for aftermarket installers and show cars; proof points such as independent certifications and high‑profile show unveilings are common tactics.
- Japanese consumer electronics incumbents: balance broad OEM relationships with a wide aftermarket portfolio; scale in supply chain and integration expertise is their competitive moat.
- OEM integrators and Tier‑1s: embed amplifiers within complete infotainment clusters and take advantage of vehicle‑level validation resources and multi‑year contracts.
Selected vendor patterns from our coverage: certain premium firms emphasize DSP and reference‑level audio processors, while performance‑oriented brands showcase highest‑output 12V architectures for the aftermarket. Several players strengthen market credibility through catalog refreshes, high‑visibility demonstrations at mobility and tuning festivals, and targeted product introductions at industry shows. Independently verified performance (third‑party measurement and Klippel‑style validation) has emerged as a differentiator for high‑end claims.
Recent market signals that matter to 2026 planning
- Product and catalogue refreshes by specialist audio vendors signal continued investment into acoustics and integration tools for premium installs.
- Showcase launches at major trade events underscore an ongoing aftermarket appetite for headline‑making power amplifiers; these launches often precede dealer and installer demand surges.
- Independent testing standards and the first vendor certifications under new verification regimes are sharpening the edge between marketing claims and measurable performance — a factor that is changing procurement language in OEM RFQs.
- Manufacturing concentrations and labor footprints in Asia remain an operational reality; labor and capacity considerations are already influencing sourcing decisions and contingency planning for new entrants and incumbents alike.
How to translate the research into a 2026 action playbook
Companies that convert market growth into sustainable profit will do three things well: align product architecture to validated vehicle constraints; prioritize verified performance and certifications; and ensure supply‑chain resilience. For 2026 decisions, we recommend a phased set of actions:
- Immediate (0–6 months): validate product claims through recognized third‑party measurement; re‑baseline pricing and warranty agreements to reflect verified performance; and stress‑test supplier continuity plans.
- Near term (6–18 months): accelerate modular platform development for scalable channel variants (OEM‑grade, premium aftermarket, specialist installs), and pursue targeted partnerships with infotainment Tier‑1s and select automakers.
- Medium term (18–36 months): selectively invest in capacity or M&A to shore up market positions where scale and certification lead to durable OEM slots; deploy localized manufacturing buffers to head off regional disruptions.
Risk matrix — what to watch in 2026
- Standards uptake and certification expectations: delayed or inconsistent adoption by vendors can impair access to premium OEM contracts.
- Component supply and labor dynamics: concentration of production and episodic labor cost volatility can compress margins or force price increases.
- Technological substitution: efficiency gains (e.g., more efficient amplifier classes or integrated amplifier‑infotainment ASICs) could compress demand for discrete amplifier units in certain vehicle classes.
- Channel friction: misaligned incentive structures between OEM integration teams and aftermarket distribution networks can limit scale‑up of new products.
What is deliberately left for the full report
This preview outlines the analytical scaffolding and strategic implications. The full PW Consulting report contains the detailed segmented market model, vendor scorecards, product‑level profitability matrices, region‑by‑region demand curves, and downloadable financial models that underpin the forecasts. We intentionally withhold the granular segmentation tables and explicit regional/application allocations here so that decision‑makers access the comprehensive data package with full context and interactive spreadsheets available on the report portal.
Final counsel for executives preparing 2026 plans
2026 will be a year when execution against validated claims and supply resilience will separate winners from laggards. Executives should move beyond topline growth narratives and ask three operational questions: (1) Can we prove our claims under recognized test protocols? (2) Do we have the modular architecture to serve both OEM leverage and aftermarket margin pools? (3) Are our sourcing and manufacturing playbooks hedged against regional labor and component concentration risks? The full PW Consulting Car Amplifiers Market report equips leadership teams with the models, verification frameworks, and strategic playbooks to answer these questions, prioritize investments, and present defensible roadmaps to boards and investors.
To unlock the full dataset, vendor rankings, and interactive scenario models that drive the 2026 strategic recommendations, access the complete report and supporting Excel tools on our research portal.
For detailed analysis of this topic, please visit the official page: Car Amplifiers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


