



PW Consulting: Chromium Oxide Green to Reach USD 776.2M by 2032 at 5.2% CAGR

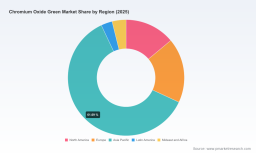
Chromium Oxide Green Market — A 2026 Strategic Preview for Executive Decision-Makers
PW Consulting’s latest Chromium Oxide Green Market study (base year 2025; historical window 2020–2025; forecast 2026–2032) provides the actionable intelligence senior executives need to set course in 2026. The market reached approximately USD 546.5 Million in 2025 and, under our central scenario, grows at a 5.2% CAGR through the 2026–2032 forecast period to reach roughly USD 776.2 Million by 2032. This preview outlines why the report matters for boardrooms and strategy teams this year — and what practical levers it contains — while intentionally reserving the granular segment-level datapoints for the full research package.
Chromium Oxide Green Market
Why this study should shape your 2026 agenda
-
Timing: 2026 is a pivot year for chromium supply economics — energy, feedstock, and regulatory headwinds are converging to create both operational risk and strategic opportunity.
Chromium Oxide Green Market -
Decision focus: procurement contracts, capital allocation for compliance and emissions control, product portfolio prioritization (pigment vs. metallurgical vs. refractory), and M&A / partnership scouting.
Chromium Oxide Green Market -
Clarity on growth: with a mid-single-digit CAGR in our baseline, executives need to distinguish durable demand pockets from price-driven volume swings.
Macro drivers and market dynamics
The Chromium Oxide Green market is shaped by three interconnected vectors: end-use demand, feedstock and production capacity, and regulatory / ESG pressure.
-
End-use demand: Chromium oxide’s role across coatings, ceramics, rubber, metallurgical and refractory applications continues to anchor baseline consumption. Incremental gains are coming from improved formulation stability in high-performance coatings and demand tied to construction and industrial refurbishment cycles.
-
Feedstock and capacity: Production relies heavily on sodium dichromate feedstock and benefits from an installed global capacity base that, by industry estimates, supports tens of thousands of tonnes annually. That underlying capacity provides a buffer to sudden demand shocks, but the concentration of primary feedstock sources creates susceptibility to regional supply interruptions and price volatility.
-
Cost inflation and price transmission: Energy, freight and raw-material pressures have driven supplier repricing actions in 2026. Notably, one major producer announced a significant price increase in March 2026 — a market signal that should trigger scenario planning for procurement and margin management.
Regulatory and ESG landscape — constraints and catalysts
Chromium chemistry is under heightened regulatory scrutiny. Recent updates include mandatory registrations and safety dossier refreshes under European frameworks, and a substantial share of manufacturers reporting higher compliance costs. In parallel, nearly half of production facilities face stringent emission standards that materially increase operating expenditure or force capital investment.
-
Compliance baseline: Key jurisdictions now require formal registration and updated safety data for Chromium(III) oxide; enterprises sourcing globally must validate REACH and comparable registrations in their supplier due diligence.
-
Cost of compliance: Around half of manufacturers report rising compliance costs — this is not a niche line item but a recurring operating burden that should be built into supplier TCO models.
-
Strategic implication: ESG-driven cost pressure is accelerating consolidation among producers with the capital to retrofit emission controls, while creating opportunity for suppliers who can credibly certify low-emission, high-purity material.
Competitive landscape — profiles and strategic postures
The market shows a moderate degree of concentration: leading global suppliers together command just over half of the market value, making supplier strategy a critical element of risk management. The competitive field includes established European, North American and Asian producers, plus regional specialists serving industrial-grade channels.
-
LANXESS (Cologne, Germany) — Global leader with high-purity pigment lines produced in flagship sites; emphasizes quality and eco-focused manufacturing. Its 2026 pricing action underscores the influence large producers have on market direction.
-
Elementis (London, UK) — Strong European position across pigment and metallurgical offerings, with a reputation for consistent quality and technical service.
-
Venator (United States) — Supplies across coatings, plastics and refractories with a sustainability narrative in its product lines, relevant for customers seeking certified low-impact inputs.
-
Vishnu Chemicals (India), Hebei Chromate and other Chinese producers — Competitive cost structures and high-purity refractory/metallurgical grades make these suppliers critical to volume markets and export flows.
-
Hunter Chemical (United States) and Cofermin (Germany) — Niche and speciality players with FDA- or industry-approved portfolios targeting high-specification applications.
-
Regional suppliers (MidUral, Aktyubinsk, Hubei Zhenhua, Jirong) — Provide industrial scale supply into domestic and adjacent export markets; relevant for customers balancing cost, lead-time and regulatory alignment.
What the full report delivers — practical, deal-ready content
PW Consulting’s full study is designed as a toolkit for immediate 2026 execution. Highlights include:
-
Robust market-sizing and methodology: transparent top-down and bottom-up approaches, reconciled to public filings and proprietary channel data for the 2020–2025 historical series and 2026–2032 forecasts.
-
Scenario modeling: three strategic demand scenarios (baseline, upside, downside) with sensitivity levers for energy prices, feedstock disruption, and accelerated regulatory tightening.
-
Supplier scorecards: operational, regulatory and sustainability KPIs for major producers, enabling rapid shortlisting for dual-sourcing or strategic partnership.
-
Procurement playbook: negotiation templates, indexation clauses, hedging and inventory strategies calibrated to the observed mid-single-digit growth environment.
-
CapEx and compliance blueprint: benchmarking of emissions control, wastewater treatment and process upgrades, with indicative timelines and cost buckets to support capex approval cycles.
-
Commercial and product roadmaps: go-to-market options for pigment vs. metallurgical grade offerings, formulation guidance, and downstream customer segmentation to prioritize sales efforts.
-
M&A and partnership screening: acquisition targets and strategic alliances mapped by technological capability, geographic footprint and regulatory posture.
-
Risk matrix and mitigation playbooks: supply interruption scenarios, regulatory shock playbooks, and contingency procurement plans for 30/60/90-day disruptions.
Key implications for corporate strategy in 2026
-
Procurement and sourcing: move from price-only sourcing to total cost of ownership models that include compliance and emissions capex. Add dual-sourcing from at least one geographically diversified supplier and one low-emission certified supplier.
-
Product strategy: accelerate formulation work for high-value coatings and specialty ceramics where margin expansion is most feasible, and evaluate premium “eco” lines for customers with sustainability mandates.
-
Capex planning: plan for staged investments in emissions controls where in-house production exists; where investments are not viable, consider longer-term contracting with certified producers.
-
M&A and JV diligence: prioritize targets that provide either technical differentiation (high-purity grades) or strategic geographic access to reduce lead times and tariff exposure.
-
Commercial risk management: incorporate surcharge pass-through clauses tied to relevant indices, and maintain strategic inventory buffers to weather short-term supplier pricing actions.
-
Regulatory readiness: embed REACH and comparable jurisdiction checks into product approvals and supplier onboarding; prepare SDS and hazard communication updates as part of product compliance governance.
How to use this preview
This article is a strategic preview intended to demonstrate analytical depth and to frame the executive decisions that need to be made in 2026. The full PW Consulting Chromium Oxide Green Market report contains the proprietary segmentation, regional and application splits, company-level KPIs, and downloadable data tables that underpin the scenarios and recommendations summarized here.
For procurement leads, R&D heads, corporate development teams and C-suite sponsors, the study provides an integrated playbook: validated market numbers, supplier intelligence, compliance roadmaps and tactical templates to turn insight into executable plans. If you are preparing budgets, supplier contracts or a strategic M&A pipeline in 2026, this research will materially shorten your decision cycle and improve outcome predictability.
PW Consulting’s approach combines industry-level capacity assessments, primary supplier interviews, regulatory scans, and proprietary demand overlays. We have intentionally withheld the granular segment-specific figures from this preview to preserve the value of the full dataset and to ensure you obtain the actionable, auditable numbers required for board-level decisions.
To access the full dataset, supplier scorecards, and scenario models that operationalize the implications above, please consult the complete Chromium Oxide Green Market report. The full report is structured to get your team from insight to action within 30 days — from contract language to capex planning to M&A shortlists.
For detailed analysis of this topic, please visit the official page: Chromium Oxide Green Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


