



Vein Finder Market to Hit USD 574M by 2032 at 5.15% CAGR — PW Consulting

Vein Finder Market 2026: Strategic Imperatives for Decision-Makers
Executive snapshot
As health systems globally seek to reduce procedural failure rates, improve patient throughput and lower per-procedure costs, the vein finder market has moved from niche adjunct to operationally material medical device category. Our PW Consulting Vein Finder Market research (base year 2025; historical 2020–2025; forecast 2026–2032) shows the market achieving steady expansion at a compound annual growth rate (CAGR) of 5.15%. Measured in USD millions, the market is recorded at USD 405.0 Million in 2025 and is modeled to progress meaningfully through the forecast window, reflecting steady clinical adoption and incremental technology improvements.
Vein Finder Market
Why this study matters for 2026 decisions
- Timing: 2026 is the first full year after multiple supplier refreshes and regulatory milestones that materially alter supplier capacity and product availability. Procurement cycles that began in 2024–25 will be assessed and renewed this year—making 2026 strategy decisions pivotal.
- Operational impact: Incremental improvements in imaging fidelity and device ergonomics are unlocking new use cases (e.g., emergent vascular access in high-throughput departments) that directly influence capital allocation and staffing models.
- Market structure clarity: Our market concentration analysis shows a market in which the top three firms control a plurality but not a monopoly (CR3 ≈ 47.3%), and the top five account for a clear majority (CR5 ≈ 61.9%), creating a competitive environment where scale matters but agility and product differentiation can still win.
Market trajectory and structural implications
The Vein Finder market’s steady CAGR reflects a classic medical-technology maturation curve: sustained clinical validation, gradual price erosion on legacy technologies, and a steady stream of incremental innovations that expand addressable use cases. Between 2020 and 2025 the market expanded consistently, and our forecasts through 2032 anticipate continued growth as hospitals embed vein visualization into standard vascular access protocols and as outpatient and home-care settings adopt portable solutions.
Vein Finder Market
For executives, the practical takeaway is twofold. First, strategic investments—whether in product development, sales infrastructure, or clinical education—must be planned on a multi-year horizon to capture compounded returns. Second, scale remains an advantage for pricing and distribution, but differentiated product characteristics (battery life, imaging depth, ease of disinfection, integration with EHR/workflow) can overturn incumbency in targeted clinical pockets.
Vein Finder Market
Technology and clinical adoption dynamics
- Modular innovation: Near-infrared (NIR) and transillumination technologies continue to be the primary performance vectors. Recent device launches emphasize improved imaging algorithms, longer battery and field durability, and easier sterilization protocols—attributes that shorten training curves and reduce total cost of ownership.
- Shifting use cases: While vascular access remains the dominant clinical application driving unit uptake, secondary use cases (dermatology, surgical planning, pediatric and geriatric care) are growing. Adoption is often incremental—starting with high-volume wards and expanding laterally as clinicians gain confidence.
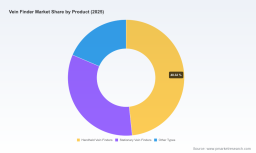
- Form factor segmentation: Handheld and portable systems are taking share in ambulatory and emergency care settings due to flexibility and lower upfront procurement friction; stationary, projection-based systems retain an advantage in procedural suites and specialized departments where integration and multi-user access are priorities.
Competitive landscape — what to watch in 2026
The competitive field contains a mix of established specialty vendors and nimble regional players. Core competitors in the space include long-standing specialists that have introduced next-generation systems, as well as newer entrants focused on localized regulatory approvals and cost-competitive portfolios.
- AccuVein Inc. continues to invest in next-gen handheld NIR systems, launching an AV600 model in early 2026 that emphasizes enhanced imaging and field durability—an explicit signal that incumbents are prioritizing product robustness for clinical throughput environments.
- Christie Medical Holdings retains its presence with projection-style systems tailored to high-volume procedural settings; attention to cleaning and compatability instructions in its device guides signals an operational focus required by large hospital clients.
- TransLite and other transillumination specialists keep competing on simplicity and focused performance for specific clinical niches such as EMS and pediatric use.
- China-based manufacturers and other regional players (including those updating catalogs or securing local regulatory clearances) are expanding addressable markets by offering competitive price-performance tradeoffs—which will accelerate adoption in emerging markets and price-sensitive channels.
Recent industry events in early-to-mid 2026—product launches, catalog updates and first-mover regulatory clearances in emerging markets—are reshuffling procurement conversations. Companies that can couple product improvements with clear clinical evidence and robust service models will command leverage in hospital negotiations.
Regulatory and procurement environment
- Regulatory posture: Many non-contact projection and certain LED-based visualization devices continue to qualify for lower-risk regulatory pathways in major markets, which reduces time-to-market for new entrants. Simultaneously, device-specific cleaning compatibility and hospital infection-control expectations are becoming decisive procurement filters.
- Procurement dynamics: Hospitals are shifting from unit-by-unit purchases to portfolio-level sourcing—favoring vendors who offer predictable maintenance, integrated training programs, and demonstrable throughput improvements. Pricing discussions are increasingly tied to service-level metrics and failure-rate reductions rather than hardware list price alone.
- Emerging-market nuance: Local regulatory clearances in high-growth countries are enabling domestic manufacturers to compete effectively on price and distribution speed; multinational suppliers must decide between direct investment, distribution partnerships, or licensing strategies to maintain presence.
Actionable strategic playbook for 2026
PW Consulting’s analysis produces a set of high-confidence actions for executives who need to convert market intelligence into deliverables this year.
- Prioritize clinical evidence tied to operational KPIs. Sponsor and publish cohort studies that quantify first-attempt success improvements, procedure-time reductions and downstream cost avoidance. These metrics win procurement conversations faster than imaging-resolution specifications alone.
- Segment go-to-market by clinical workflow, not by department names. Target high-throughput wards (e.g., emergency, dialysis, pediatric floors) with tailored propositions—bundled devices, training and service commitments—rather than one-size-fits-all offers.
- Design differentiated pricing models. Introduce outcome-linked pricing for high-volume clients and subscription-based models for outpatient chains. These reduce procurement friction and align incentives for device uptime and service performance.
- Invest selectively in product robustness and cleaning compatibility. Hospital infection-control requirements and device longevity directly affect total cost of ownership and purchasing decisions—make these explicit selling points backed by test data.
- Establish regional playbooks. For emerging markets, consider licensing or local manufacturing relationships to accelerate regulatory clearances and meet price-performance expectations. For mature markets, double down on integration, bundled service and clinical training.
- M&A and partnering discipline. With CR5 around 61.9%, there is room for bolt-on acquisitions that extend clinical reach or broaden portfolio breadth. Prioritize targets with complementary clinical data, robust service networks, or unique form-factor IP over purely geographical roll-ups.
What the PW Consulting report delivers (practical components)
This study is crafted to be directly actionable for product, commercial, and corporate development teams. Deliverables include:
- A robust market model (historical 2020–2025; forecast 2026–2032) with scenario toggles for adoption rates, price erosion and service revenue assumptions;
- A competitive playbook detailing product positioning, service propositions and go-to-market templates for both mature and emerging markets;
- Regulatory and procurement risk-mapping by market cluster, including recommended mitigations for device cleaning, classification and local registration timelines;
- Commercial templates—provider ROI calculators, contract language frameworks and clinical-evidence study protocols—designed to shorten sales cycles and strengthen negotiation positions.
Importantly, while this introduction highlights directional insights and strategic implications, detailed sub-segment tables and confidential supplier share estimates are intentionally reserved for the full report. Those granular views are essential for transaction-level decisions and are accessible through our research portal.
How to use this intelligence in Q2–Q4 2026
- Rapid portfolio review: Use the market model to stress-test product roadmaps against conservative and optimistic adoption curves, then prioritize R&D and capital accordingly.
- Commercial pilots: Launch high-impact pilots in targeted clinical pockets where you can demonstrate measurable throughput benefits within 90–180 days.
- Regulatory pathway alignment: If entering new jurisdictions, map registration timelines to procurement cycles to avoid missed contracting windows.
- M&A readiness: Prepare an acquisition checklist that emphasizes clinical evidence dossiers, service coverage maps and IP transferability to accelerate deal execution in a moderately consolidated market.
Closing — the strategic value of evidence-led action
The vein finder market offers predictable, above-inflation growth driven by practical clinical benefits and a wave of incremental product innovation. For 2026, success will flow to organizations that combine rigorous evidence generation, targeted commercial execution and operational readiness to support clinicians. PW Consulting’s Vein Finder Market research provides the modeling, competitive context and executable tools to translate these market dynamics into defensible strategic moves—while leaving the detailed, transaction-critical sub-segment datasets to the full report for subscribers and clients.
For organizations preparing budgets, evaluating M&A opportunities, or planning product launches in 2026, this study is designed to shorten decision cycles and reduce execution risk.
For detailed analysis of this topic, please visit the official page: Vein Finder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


