



PW Consulting: Heating Furnace Market Poised for 5.5% CAGR Through 2032

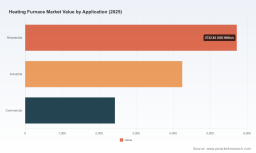
Heating Furnace Market — Strategic Preview for 2026 Decision-Makers
As Pw Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a high-level briefing on our Heating Furnace Market study that positions executive teams to make decisive, risk-calibrated moves in 2026. Built on a robust historical window (2020–2025) and a detailed forecast horizon (2026–2032), this analysis synthesizes macro growth trajectories, regulatory inflection points, raw-material pressures, competitive positioning, and product/technology vectors that will determine winners and laggards through the end of the decade.
Heating Furnace Market
Market at a Glance — What the Numbers Tell Us
The heating furnace market reached a substantive base in 2025, and our model projects a compound annual growth rate (CAGR) of 5.5% through 2032 under the central scenario. That pace reflects a mix of retrofit activity, new construction demand, technology upgrades driven by energy-efficiency standards, and selective industrial investment in advanced heating technologies. By 2032 the market is forecast to be meaningfully larger than the 2025 baseline, creating a multi-billion dollar opportunity pool for suppliers, integrators, and service specialists who align product roadmaps and channel strategies to the emerging regulatory and fuel-price landscape.
Heating Furnace Market
Why This Report Matters to 2026 Strategy
-
Actionable timing: The 2026–2032 forecast period overlays a critical regulatory cascade and commodity cycle that will drive product obsolescence and create windows for premiumization. Companies that allocate capex and R&D in 2026 with these timelines in mind will capture disproportionate share in the early-adoption tranche.
Heating Furnace Market -
Policy-driven premiums: New efficiency mandates and updated industry standards are reshaping product architectures. Our study translates those mandates into product-level technical requirements, compliance timelines, and estimated retrofit volumes — enabling procurement, product and regulatory teams to prioritize investments that protect margin.
-
Supply chain resilience: Rising commodity costs and supply constraints for key inputs (notably steel) are compressing supplier margins. The report provides scenario-tested procurement strategies and supplier-sourcing playbooks that reduce exposure while maintaining launch schedules.
-
Competitive intelligence: We map winners by capability (high-efficiency combustion platforms, induction heating for industrial users, and digital-integrated solutions for the residential channel) and identify whitespace where late entrants can establish new footholds.
Report Contents — Practical Deliverables (Summary)
-
Market sizing and growth drivers: historical decomposition and bottom-up forecast models capturing demand levers across channels and end-markets for 2026–2032.
-
Regulatory impact analysis: scenario modeling of efficiency standards, codes, and guidance (including major published rules and ASHRAE guidance) and their timing impacts on product lifecycles and cost pass-through.
-
Technology and product roadmaps: competitive benchmarking of combustion, electric, induction, and hybrid heating technologies, with R&D priorities and cost-to-performance trajectories.
-
Go-to-market playbooks: channel segmentation, pricing strategies, aftermarket and service monetization blueprints, and digital value propositions for 2026 rollouts.
-
Supply-chain and procurement risk maps: critical-input exposure assessments, hedging strategies, and alternative sourcing scenarios tuned to 2026 supply dynamics.
-
M&A and partnership pipeline: prioritized target archetypes, valuation heuristics, and integration risks for roll-up or capability-acquisition plays.
-
Decision-support tools: ROI calculators, sensitivity analyses, and playbook checklists designed for board-level decision cycles in 2026.
Competitive Landscape — Forces Shaping Market Structure
The market exhibits moderate concentration: the leading three firms account for under one third of market share, while the top five remain below the 40% threshold. This structure favors firms capable of scale in manufacturing, differentiated product platforms, or superior channel access — but it also leaves meaningful room for regional specialists and engineered-solution providers to disrupt.
-
Carrier — a leader in high-efficiency gas and electric furnaces, leveraging variable-speed technology and ENERGY STAR positioning. Carrier’s strength is in system-level integration and channel reach; their playbook for 2026 should emphasize lifecycle services and bundled efficiency solutions for premium segments.
-
Trane Technologies — through the Trane and American Standard brands, they emphasize reliability, high AFUE performance, and integrated smart controls. The strategic lever for Trane is pushing system integration with building controls, enabling recurring revenues via service and controls subscriptions.
-
Lennox International — known for premium, quiet, and modulating models. Lennox’s advantage lies in differentiated product performance; defensive moves in 2026 should include expanding value-added installation training and optimizing compressor/electronics supply chains to protect margin on high-end SKUs.
-
Rheem Manufacturing — a value-to-performance player offering durable constructions across gas and electric lines. Rheem can increase share by streamlining aftermarket parts availability and reinforcing installer loyalty programs in growth geographies.
-
Goodman Manufacturing — competes on affordability and dependable performance. Goodman’s strategic opportunity in 2026 is to couple cost leadership with modular, upgradable electronics that enable an eventual premium services attach without undermining price positioning.
-
Inductotherm Group — a specialist in industrial induction heating for metal processing. Inductotherm benefits from capital-equipment tailwinds where energy efficiency and process repeatability are mission-critical; their 2026 play should focus on digital process monitoring and vertical partnerships with metal processors.
Recent Industry Moves and Their Strategic Bearings
-
Product launches at industry shows in 2025 signaled a push toward next-generation burners, compact system furnaces, and installation/diagnostic tools — all pre-positioning vendors for retrofit waves and stricter efficiency expectations. These launches create short-term differentiation but will be table stakes if regulations tighten as expected.
-
Commodity-pressure events in 2025 increased unit cost volatility for steel and other inputs. Tactical purchasing strategies and contract renegotiations are essential in 2026 to preserve gross margins without sacrificing availability.
-
Published standards and guidance from regulatory bodies and ASHRAE are converging toward uniform efficiency and safety practices. The timing of these policies creates predictable windows for product obsolescence and forced retrofits — windows that can be exploited for margin-rich replacement cycles if firms are operationally prepared.
Key Strategic Imperatives for 2026
-
Prioritize compliance-led product refreshes: Prepare engineering and supply chains in 2026 to meet impending efficiency thresholds. Delaying retooling beyond 2026 risks compressed timetables and elevated replacement costs.
-
Monetize services and digitalization: Build subscription and predictive-maintenance offers tied to smart controls and diagnostics. These revenue streams insulate firms from cyclical capex swings and enhance customer retention.
-
Hedge raw-material exposure: Implement layered sourcing, strategic stockpiling for critical components, and supplier partnerships that include cost-sharing mechanisms to absorb short-term price spikes.
-
Invest selectively in electrification and induction capabilities: While gas-fired solutions remain central today, the long-term vector favors electrified and induction offerings in select industrial and premium residential segments. Early entrants to hybrid platforms will secure attractive pricing power.
-
Optimize channel economics: Rebalance investments between direct-installation programs, contractor incentives, and OEM distribution to ensure profitable installation throughput as retrofit demand accelerates.
-
Use M&A to plug capability gaps: Targets that expand controls, digital services, or induction expertise will accelerate time-to-market and are generally less capex-intensive than greenfield R&D investments.
Risk Factors and Contingencies
-
Regulatory timing risk — accelerated or delayed adoption of efficiency mandates materially affects replacement cadence and inventory strategies.
-
Fuel-price dynamics — projected shifts in relative electricity vs gas pricing alter total-cost-of-ownership calculations and customer switching behavior; companies should stress-test pricing and product mixes against both higher and lower electricity-to-gas scenarios.
-
Supply-chain shocks — single-source dependence for critical components elevates vulnerability; diversification is a priority.
Next Steps — How Executives Should Use This Preview
This briefing outlines the strategic shape of the market and the levers that leaders must pull in 2026 to create defensible growth. Our full report contains the granular segmentation, regional and application breakdowns, product-level compliance requirements, and executable 90–180–360 day playbooks that are intentionally withheld from this preview to preserve proprietary insights. For teams developing 2026 budgets, crafting M&A pipelines, or revising R&D roadmaps, the full dataset and scenario models are indispensable.
Pw Consulting is prepared to walk leadership teams through tailored briefings, readiness assessments, and rapid-deployment playbooks grounded in the report’s findings. For those prioritizing decisive action in 2026, the time to translate scenario visibility into execution capability is now.
For detailed analysis of this topic, please visit the official page: Heating Furnace Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


