



PW Consulting: 2-in-1 Laptops Market Poised for 7.0% CAGR to 2032

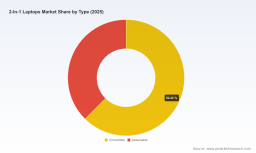
2‑In‑1 Laptops Market — Strategic Preview for 2026 Decision‑Makers
As enterprises and device manufacturers set strategy for 2026, understanding where the 2‑in‑1 laptop market is heading is no longer optional — it is foundational. This preview, prepared by PW Consulting’s Senior Strategy Team, distills the essential macro trajectory, competitive dynamics, and risk vectors that will determine winners and losers over the coming investment cycle. It intentionally reveals the high‑level intelligence you need to prioritize actions while withholding the granular subsegment tables that form the core of our paid analysis — the exact splits and micro‑metrics that materially affect tactical decisions are available in the full report.
2-In-1 Laptops Market
Why this study matters for 2026 strategic decisions
-
Market momentum: The 2‑in‑1 market has demonstrated consistent growth through the early 2020s and is positioned for continued expansion. From the early‑2020 baseline, the market expanded to a mid‑2020s base year and is forecast to accelerate through the 2026–2032 horizon at a mid‑single‑digit compound annual growth rate (CAGR) of 7.0%.
2-In-1 Laptops Market -
Investment signals: That trajectory means that capital allocation decisions made in 2026 — on product R&D, factory capacity, and go‑to‑market programs — will compound through the decade. Firms that act on forward‑looking scenario analysis will capture asymmetrical returns versus those reacting to last year’s trends.
2-In-1 Laptops Market -
Portfolio optimization: For OEMs and channel partners, the study provides the strategic lens to rationalize SKUs, prioritize form factors (convertible vs detachable), and align inventory strategies with projected demand curves and component lead‑time dynamics.
Market trajectory — a data‑driven snapshot
From an industry vantage, the 2‑in‑1 market has grown from roughly USD 2.6 billion in 2020 to just over USD 3.3 billion in the base year of 2025. Our forecast indicates continued expansion, with the market approaching the mid‑USD 3.6 billion mark in 2026 and progressing toward more than USD 5.3 billion by 2032 under the central case — driven by product renewal cycles, AI‑enabled user experiences, and sustained demand in both consumer and commercial channels.
This trajectory is underpinned by three structural forces: improving component integration (notably displays and NPUs), diversification of CPU/accelerator architectures, and the gradual normalization of supply chains following geopolitically‑induced dislocations. While the headline CAGR of 7.0% is valuable, the sector’s true inflection points occur at the component and regional level — details that the full dataset and scenario matrices unpack in actionable form.
Competitive landscape — who matters and why
The market shows a relatively concentrated supplier set: the largest OEMs collectively control a material share of industry revenue (CR3 in the high‑sixties percent range). That concentration creates predictable competitive dynamics — scale advantages in components procurement, marketing reach for channel rollout, and the ability to fund platform‑level AI investments.
-
Dell — leverages enterprise relationships and breadth of 2‑in‑1 SKUs. Dell’s focus on Intel Core Ultra‑based platforms and pen/touch integration keeps it relevant across corporate fleets that prioritize manageability and security.
-
HP — blends enterprise product reliability with consumer innovation. HP’s Elite and OmniBook lines push OLED screens and embedded AI features, strengthening positions in hybrid work and premium consumer segments.
-
ASUS — differentiates through display and performance variants. With lines that span ProArt to ROG and Chromebook, ASUS exploits form‑factor flexibility and display technology leadership (high‑res OLED options and 360° hinges).
-
Acer — driving aggressive silicon diversification. Recent product introductions emphasize Snapdragon‑based platforms and long battery life, an important wedge in mobility‑centric enterprise and education deployments.
-
Lenovo — strong portfolio depth from consumer Yoga to enterprise Think‑class alternatives. Lenovo’s adoption of AI‑centric OS features (e.g., Copilot integrations) is accelerating differentiation on user productivity.
-
Samsung — capitalizing on AMOLED and system‑level integration. Samsung’s Galaxy Book 2‑in‑1 family marries display quality with AI PC capabilities — a clear play for high‑value creative and premium segments.
-
Microsoft — the benchmark in detachable innovation. Surface Pro lines and high‑end detachable devices set expectations for detachable performance, design, and OS‑level AI experiences.
Collectively, these firms are converging on three common battlegrounds: display quality and touch/pen fidelity, AI/NPU acceleration at the edge, and supply chain resilience. Our full competitive module includes vendor scorecards, SKU‑level margin proxies, and partner maps that are essential for channel and OEM negotiation strategies — material intelligence that we withhold from this public preview.
Dynamics and risk vectors shaping 2026 outcomes
Several external dynamics will materially affect 2026 decisions. These are not abstract — they change unit economics, time‑to‑market, and strategic timing for launches and capacity investments.
-
Geopolitical trade friction: Export controls and tariffs have forced manufacturers to diversify component sourcing and accelerate localization. This is reshaping supplier selection and influencing the preferred locations for assembly and sub‑assembly closer to end markets.
-
Component shortages and semiconductor risk: Ongoing trade tensions amplify lead‑time volatility for advanced semiconductors and displays. Firms that model multi‑tier sourcing alternatives and maintain strategic buffer inventories gain negotiating power and reduce stock‑out costs.
-
Raw material and input cost inflation: Retaliatory tariff cycles and logistic disruptions have driven significant cost pressure on finished device pricing. Price elasticity and channel promotion planning are therefore critical to preserve market share without eroding margins.
-
Regulatory procurement impacts: Public sector procurement authorities note longer lead times and elevated costs in laptop categories; vendors targeting government and education buyers must factor compliance and SLA adjustments into bids.
Two recent industry developments exemplify these dynamics: Acer’s May 2026 launch of a Snapdragon‑based Swift Spin 14 AI (highlighting the high‑performance ARM ecosystem and multi‑day battery claims) and a February 2026 ramp of OLED touch controller ICs by a display component specialist — both signals that component roadmaps and platform choices are rapidly evolving.
How senior executives should use this research in 2026
-
Product roadmap prioritization: Use our scenario outputs to decide which form factors and feature sets to fund in 2026 R&D budgets. Prioritize investments that increase perceived differentiation (display, pen UX, AI edge performance) without disproportionately raising BOM risk.
-
Procurement and supply‑chain hedging: Implement a supplier risk matrix and alternative sourcing playbook derived from our lead‑time and cost simulations to protect critical launches.
-
Channel and pricing strategy: Align promotional cadence and inventory targets by integrating our demand seasonality models and price‑elasticity analysis — especially where education and enterprise refresh cycles drive volume.
-
M&A and partnership screening: Apply our vendor scorecards and technology roadmaps to shortlist acquisition targets or strategic equity partnerships that accelerate access to OLED, NPU, or modem capabilities.
-
Regulatory and procurement readiness: Use our policy impact assessments to construct compliant bid strategies for public sector opportunities, where lead‑time and origin constraints are now binding.
What the full PW Consulting report delivers (practical contents)
The full research package is designed as a boardroom‑ready decision tool. Key deliverables include:
-
Comprehensive market model (historical 2020–2025; forecast 2026–2032) with scenario ranges, sensitivity tables, and demand drivers by macro segment.
-
Detailed competitive intelligence: SKU‑level maps, product launch timelines, go‑to‑market matrices, and vendor scorecards that quantify technology and channel advantages.
-
Supply‑chain heatmaps and mitigation playbooks, including alternate sourcing ladders, contract negotiation levers, and lead‑time optimization tactics.
-
Commercial playbooks for OEMs and channel partners — pricing tactics, bundle strategies, and promotional calendars tailored to education, enterprise, and premium consumer buyers.
-
Investment and M&A screening tools: proprietary valuation benchmarks for target selection, plus integration risk checklists tied to component availability and IP ownership.
-
Executive‑ready briefings and slide decks customizable for investor relations, board meetings, and sales enablement.
Note: This preview deliberately omits the granular region‑by‑region and application‑by‑application splits and unit‑level price tables — those constitute the core, monetizable intelligence in the subscription report. If your team requires subsegment KPIs and the underlying datasets to operationalize these recommendations, the full report contains downloadable Excel models and interactive dashboards.
Conclusion — what to act on now
Decisions made in 2026 will lock in product portfolios and supply‑chain commitments for multiple years. The macro outlook is favorable — mid‑single‑digit CAGR and a market that nearly doubles over the forecast horizon — but upside capture requires targeted investments in AI‑enabled UX, display quality, and resilient sourcing. For firms that can combine product differentiation with multi‑tier supply strategies, the coming windows offer meaningful growth and margin expansion.
To convert these insights into a 90‑day action plan tailored to your organization, request the full PW Consulting 2‑In‑1 Laptops Market report and our accompanying scenario workbench. The preview is sufficient to inform strategic intent; the full intelligence package is required to execute with conviction.
For detailed analysis of this topic, please visit the official page: 2-In-1 Laptops Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


