



PW Consulting: Pipe Joints Market Set to Hit USD 327.9 Million by 2032

Pipe Joints Market — 2026 Strategic Preview for Corporate Decision‑Makers
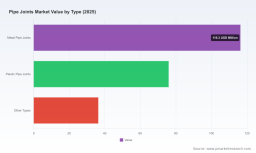
PW Consulting presents a concentrated strategic preview of our forthcoming Pipe Joints Market report — a practical briefing designed to shape capital allocation, sourcing, product and regulatory strategies for the year ahead. The market, measured on a base year of 2025, sits at approximately USD 228.6 Million and is forecast to expand at a compound annual growth rate (CAGR) of 5.35% through the 2026–2032 horizon, reaching roughly USD 328 Million by 2032. This trajectory reflects steady, structurally driven demand and meaningful pockets of opportunity for manufacturers, system integrators and large buyers. The purpose of this preview is to surface the decision‑critical themes and tactical playbooks contained in the full study while reserving the granular sub‑segment data for the full report and interactive dashboards.
Pipe Joints Market
Why this briefing matters for 2026 decision cycles
-
Capital planning: The modest but reliable market growth and clear technology clustering (mechanical couplings, restrained joints, expansion assemblies) change the payback calculus for plant retrofits, specification changes in new builds, and inventory rationalization.
Pipe Joints Market -
Procurement and supplier strategy: With raw material costs moderating in 2026 and product unit prices ranging broadly by spec (general metal joints commonly priced in the low tens to low hundreds of dollars, with high‑spec alloy units commanding up to the low thousands), procurement teams can redesign sourcing agreements to capture savings while insulating against volatility.
Pipe Joints Market -
Regulatory compliance and risk management: Recent fire‑safety regulations affecting nonmetallic joint approvals are already reshaping specification windows for building and sprinkler systems. Compliance readiness has become as material to project timelines as lead‑time control.
-
M&A and partnership targeting: The market remains fragmented — top sellers control a modest share of demand (the three‑firm and five‑firm concentration ratios are low‑to‑moderate), making targeted acquisitions and channel partnerships a fast route to capability expansion and geographic reach.
What the full report contains (practical deliverables)
-
Transparent market sizing and validated forecast model (historical 2020–2025; forecast 2026–2032) with scenario toggles for raw material, regulatory and capex cycles.
-
Go‑to‑market playbooks: product specification checklists by system class, procurement negotiation levers, installation labor reduction case studies and retrofit decision trees.
-
Supply chain heatmaps and supplier scorecards: lead time breakouts, near‑term sourcing risks, and an inputs‑to‑cost bridge that isolates steel, elastomers and specialty alloys for targeted hedging.
-
Competitive benchmarking and strategic options: capability matrices for mechanical couplings, restrained joints, expansion joints and polymer fittings; potential M&A candidates and integration synergies.
-
Regulatory tracker and certification roadmap: actionable steps to ensure product approvals under recent code updates and an audit checklist for installation compliance.
-
Interactive commercial tools: total cost of ownership (TCO) calculators, SKU rationalization simulators and procurement timing models designed to be used in board‑level capital deliberations.
Market dynamics snapshot — what’s driving demand and cost in 2026
-
Infrastructure and retrofit momentum: Spend on water systems, urban utilities and industrial maintenance continues to underpin steady demand. The full study maps demand drivers against investment cycles to indicate where replacement and new‑build opportunities cluster.
-
Material and cost dynamics: Steel prices have moderated in 2026 after prior volatility; this normalization reduces immediate margin stress for metal‑focused manufacturers but amplifies competition on delivery and technical differentiation.
-
Specification shifts and safety codes: New fire‑safety requirements and installation standards are prompting architects, contractors and owners to revise product lists and installation practices, accelerating adoption of certified mechanical systems in higher‑risk applications.
-
Installation productivity as a product differentiator: Solutions that materially shorten onsite labour time — grooved systems, pre‑fabricated couplings, and modular joint assemblies — are being prioritized by contractors seeking certainty on schedule and cost.
Competitive landscape — what leading vendors reveal about strategy
The competitive set combines specialist manufacturers, broad system suppliers and component specialists. The market’s fragmentation (three‑firm and five‑firm concentration ratios are consistent with a low‑to‑moderate level of consolidation) implies that focused investments or partnerships can rapidly change a vendor’s standing.
-
Northwest Pipe Company — Positioning: engineered steel water pipe with integrated watertight joint systems. Strategic implications: strength in engineered, long‑lead water projects and the ability to bundle pipe + joint as a specification advantage in municipal and large‑scale water programs.
-
Victaulic — Positioning: global leader in grooved mechanical couplings emphasizing rapid installation and system safety. Strategic implications: Victaulic’s product innovation (including recent rigid‑joint sprinkler coupling introductions) highlights the premium buyers place on labor savings and standardized systems — a competitive vector others must address.
-
Teekay Couplings — Positioning: UK‑manufactured mechanical couplings across an extensive diameter range focused on installation efficiency and weight savings. Strategic implications: regional manufacturing and breadth of diameters create advantages in projects where logistics and weight constraints matter.
-
American Cast Iron Pipe Company — Positioning: restrained joints for ductile iron pipe with a focus on preventing endwise separation under thrust. Strategic implications: product specialization that supports utility and heavy‑civil specifications; attractive partner for consortium bids on large water infrastructure programs.
-
Holz Rubber Company — Positioning: custom and standard expansion joints designed to absorb thermal movement and misalignment. Strategic implications: elastic joint systems are complementary to rigid coupling providers; cross‑sell and integration opportunities exist for firms that marry mechanical and elastomeric technologies.
Recent market activity — from product launches to trade fairs — underscores two tactical realities: suppliers continue to compete on installation efficiency and compliance credentials, while trade‑show circuits remain key for procurement discovery and specification shifts. Examples include a spring 2026 product launch focused on rigid sprinkler joints and high‑visibility trade fairs where global suppliers showcased new couplings and fittings.
Immediate strategic actions for executive teams in 2026
-
Reprice and renegotiate supply contracts now that steel costs have moderated. Capture savings through indexed contracts that retain upside protection against raw material re‑spikes.
-
Prioritize certification and installation compliance for nonmetallic and hybrid systems where codes have tightened. Fast‑tracking approvals shortens lead times for projects tied to new safety standards.
-
Run a 90‑day SKU and specification audit to identify where modular couplings or pre‑assembled joints can reduce onsite labour by 15–30% (case estimates documented in the full study).
-
Develop an M&A/partnership shortlist: target small‑to‑mid players with complementary installation technologies or regional manufacturing that can be integrated quickly to improve service and margins.
-
Implement the TCO toolkit from the report: move procurement conversations from unit price to lifecycle cost, factoring in installation time, maintenance intervals and failure‑risk premiums.
-
Design a compliance monitoring cadence: align engineering, procurement and legal teams to ensure product specs remain compliant as local codes evolve.
How PW Consulting supports your 2026 strategy
PW Consulting’s full Pipe Joints Market report delivers the data, models and practical playbooks required to convert market insight into executable plans. The deliverables include downloadable datasets, interactive scenario models, supplier‑level briefings, and a short‑form board presentation tailored to capital approval cycles. The full report contains the granular sub‑segment breakouts, regional demand dashboards and unit‑price matrices that our preview intentionally holds back to guide readers to the full, interactive resource.
If your 2026 agenda includes supply‑chain realignment, targeted M&A, specification revision or capex reprioritization in piping systems, the intelligence in the full report reduces risk and accelerates decision timelines. PW Consulting’s advisory team is prepared to run focused workshops using the report’s tools to convert insights into a 90‑day action plan customized for your footprint.
Summary: the pipe joints market offers manageable growth with clear levers for value creation in 2026 — procurement reshaping, compliance acceleration and targeted capability builds offer the highest near‑term returns. The full PW Consulting study contains the empirical detail and implementation templates required to make these moves with confidence.
For detailed analysis of this topic, please visit the official page: Pipe Joints Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


