



PW Consulting: Tire Protection Chains Market Forecast at 5.3% CAGR Through 2032

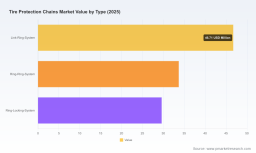
Tire Protection Chains Market — Strategic Outlook for 2026
Introduction: Why PW Consulting’s latest study matters this year
As senior industry advisers at PW Consulting, we wrote this market brief to frame the decisions that will determine leadership in the Tire Protection Chains (TPC) market through 2026 and beyond. The market sits on a steady growth trajectory — with a base-year market size of approximately USD 110 million in 2025 and a compound annual growth rate (CAGR) of 5.3% across our forecast period — culminating in a materially larger opportunity by the end of the decade. This article previews the strategic implications and high‑confidence signals from our full study while intentionally preserving the detailed segment-level intelligence for clients who access the complete report.
Tire Protection Chains Market
Why this study should influence 2026 corporate priorities
-
Procurement optimization: TPCs are a capital‑intensive consumable for mine operators, quarries and heavy‑equipment fleets. The full study translates market growth and supplier dynamics into negotiating levers and total cost of ownership (TCO) templates that materially change procurement outcomes.
Tire Protection Chains Market -
Capex and product roadmaps: A predictable market CAGR of 5.3% masks pockets of higher technical replacement and aftermarket potential. Engineering and product teams need to align alloy, forging and installation investments to capture premium wear‑resistant segments.
Tire Protection Chains Market -
M&A and partnership screening: Moderate concentration among suppliers creates acquisition and JV opportunities. Our approach prioritizes targets by technological differentiation, certification footprint and production footprint — turning market sizing into actionable target lists.
-
Regulatory and certification compliance: Evolving regional regulations and mandatory standards exert outsized influence on procurement cycles. Executives must embed compliance checks into supplier selection to prevent operational downtime and warranty exposure.
Macro dynamics shaping 2026 decisions
Three systemic forces drive the TPC market today: the industrial cycle of mining and heavy civil works; materials and manufacturing technology evolution; and regulatory/certification frameworks. Our study tracks each and demonstrates how they map to tactical decisions.
-
Demand fundamentals — mining, quarrying and heavy‑equipment renewals remain the principal consumption drivers. Despite cyclical fluctuations in commodity markets, replacement and aftermarket services create a durable base that supports the mid‑single‑digit CAGR identified in our forecast.
-
Materials and manufacturing — steel remains the dominant feedstock for TPCs (industry data indicates steel accounts for a significant share of material composition). High‑alloy, drop‑forged link technology is the accepted engineering standard, and new metallurgical innovations (e.g., nano‑alloy treatments) are shifting the value equation from unit price toward lifecycle performance.
-
Regulation and standards — certification frameworks such as EN‑TSE 663 and ISO 9001 continue to be gating factors for participation in the large‑scale supply chains of OEMs and mining contractors. Additionally, transport and winter‑equipment mandates in key jurisdictions (for example, the carriage requirement for suitable snow chains on certain goods vehicles across seasonal periods) create recurring demand and shape product specifications.
Interpreting the market trajectory
Our historical base (2020–2025) and forecast horizon (2026–2032) reveal a market that is expanding steadily rather than exploding: the reported CAGR of 5.3% reflects maturation and increasing aftermarket penetration rather than broad commoditization. For decision‑makers this implies:
-
High value in differentiation: Suppliers that shift the conversation to lifecycle cost and safety will capture premium margins.
-
Incremental volume gains: Compounded growth opens targeted scale advantages for manufacturers who invest selectively in automation and forging capacity.
-
Resilience to short‑term shocks: Diversified procurement strategies and inventory planning are effective hedges against raw‑material (steel) volatility and transportation disruptions.
Competitive landscape — strategic implications from leading players
The TPC supplier community is a mix of long‑established European specialists, regional champions, and price‑competitive global manufacturers. Overall market concentration is measurable — our analysis shows a meaningful share sits with the top incumbents — a structural fact that shapes distributor margins, OEM relationships and after‑sales ecosystems.
-
European technical leaders: Companies with deep R&D, strict certification regimes and established OEM relationships maintain a competitive edge on premium, high‑durability products. Recent product innovation from one Austrian incumbent — a nano‑alloy chain series claiming materially higher wear resistance — illustrates how metallurgical advances can re‑price the market toward lifecycle performance.
-
Regional manufacturing scale: Turkish and Eastern European manufacturers emphasize vertical integration of forging and heat‑treatment processes and aggressive export programs. These players are attractive partners for distributors focused on balanced price/performance offerings.
-
Provider diversification in emerging markets: Suppliers in Africa and Asia position cost competitiveness with local authorizations and OEM partnerships. Their value proposition to mines and contractors commonly rests on favorable TCO claims and local service capabilities.
-
US incumbents and niche specialists: Established companies in North America hold long histories in chain manufacturing and are relevant for customers valuing domestic sourcing, custom engineering and rapid aftermarket response.
For buyers and investors, the competitive takeaway is clear: choose partners that combine certification compliance, demonstrable product testing, and local service capability. Recent industry activity — from product launches demonstrating significant wear improvements to high‑visibility participation at international OTR conferences — is repositioning competition around quality and placement rather than pure price.
Operational and procurement playbook for 2026
Based on the study’s signals, PW Consulting recommends the following prioritized actions for companies acting this year:
-
Run supplier TCO pilots that replace unit‑price decisions with lifecycle metrics (wear resistance, downtime impact, installation time and recyclability).
-
Enforce certification gates (EN‑TSE 663 and ISO 9001) in contractual terms and include independent lab test clauses for metallurgical claims.
-
Mitigate steel supply risk with dual‑sourcing and hedging strategies; tie purchasing contracts to clear performance KPIs that shift risk to suppliers.
-
Prioritize aftermarket and field service capabilities: warranties, rapid delivery of replacement links and certified fitment support are decisive differentiators.
-
Screen M&A targets using a three‑lens rubric: technological differentiation (alloy/forging), certification footprint, and distribution reach into high‑value end markets.
What the full PW Consulting report delivers (select highlights)
-
Transparent market sizing and forecasting methodology with stress scenarios for commodity cycles and regulatory shifts.
-
Value‑chain mapping from raw‑steel inputs through forging and heat treatment to aftermarket service economics.
-
Detailed competitive profiles and supplier scorecards (technology, capacity, certification, claims verification, and go‑to‑market reach).
-
Procurement playbooks, TCO calculators and sample RFP language to operationalize supplier negotiations.
-
Regulatory compliance matrix and installation/operational risk heatmaps for major jurisdictions.
-
Implementation roadmaps for 90/180/365 days aligned to capex and procurement cycles.
How to translate insight into action — a 90/180/365 roadmap
-
90 days: Conduct supplier audits focused on certification and metallurgical verification; initiate one pilot for lifecycle performance measurement.
-
180 days: Consolidate preferred supplier list; renegotiate warranty and performance‑linked terms; adopt standardized TCO metrics across business units.
-
365 days: Execute selective investments in supply chain redundancy or M&A to secure differentiated alloy or forging capability; roll out aftermarket service programs that monetize uptime improvements.
Closing — why executive teams should prioritize TPC strategy in 2026
The Tire Protection Chains market provides a classic example of a mature industrial segment where incremental technical improvements and smarter procurement convert into outsized competitive advantage. With a stable mid‑single‑digit CAGR and a clear path toward higher aftermarket value, 2026 is a decision point: companies that formalize lifecycle‑centred procurement, validate metallurgical claims, and selectively invest in capacity or capability will capture the premium margins and durable customer relationships that define market leadership.
For practitioners seeking the complete, actionable intelligence — including the anonymized segment and regional detail that underpins our recommendations — please refer to the full PW Consulting market study. The report contains the granular data, supplier scorecards and implementation tools required to translate the market’s trajectory into measurable business outcomes.
For detailed analysis of this topic, please visit the official page: Tire Protection Chains Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


