



PW Consulting: Eyeglass Edging Machines Market to Reach USD 1,570 Million by 2032 at 5.8% CAGR

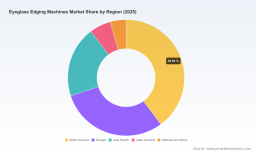
Eyeglass Edging Machines Market: Strategic Briefing for 2026 Decisions
Executive snapshot
The global eyeglass edging machines market stands at an inflection point. Using 2025 as the base year, our market model places overall industry revenue at approximately USD 1,056 Million. Under the core forecast scenario the market expands at a 5.8% CAGR through the 2026–2032 horizon, trending toward roughly USD 1,570 Million by 2032. Market concentration is meaningful: the three largest vendors account for a majority share (CR3 ~52%), and the top five capture roughly two-thirds (CR5 ~65%).
Eyeglass Edging Machines Market
This briefing highlights the strategic value of PW Consulting’s full Eyeglass Edging Machines Market study for board- and C-suite-level decision making in 2026. It presents evidence‑driven direction on demand drivers, technology and supply dynamics, competitive posture, and the commercial playbook executives should deploy this year — while intentionally reserving granular segment tables and precise regional/application shares for the full report.
Eyeglass Edging Machines Market
Why this market matters in 2026
- Resilient core demand: Optical retail labs and manufacturing channels continue to underpin steady replacement and capacity-add cycles, while rising penetration of advanced materials (polycarbonate, Trivex, high-curve lenses) increases demand for higher-spec finishing equipment.
- Automation and productivity uplift: The movement from manual and semi-automatic systems toward higher-throughput automatic edgers is accelerating, driven by labor-cost pressures and the need for consistent finish quality across diverse lens geometries.
- Regulatory and environmental compliance: Emerging dust-emission rules in key markets and the new EN IEC 60601-2-57:2026 safety standard impose capital, design and lifecycle-service considerations on both OEMs and operator-customers.
Market dynamics: drivers, constraints and inflection points
Several forces are shaping supplier economics and buyer behavior in 2026:
Eyeglass Edging Machines Market
- Raw-material concentration: Premium diamond-abrasive wheels — a critical consumable for precision edging — face tight global supply chains. Shortages and lead-time variability increase the strategic value of consumables partnerships and create margin volatility for independent repair shops and smaller OEMs.
- Compliance-led product redesign: Stricter dust-emission norms across North American and EU jurisdictions, coupled with the new IEC‑aligned safety standard for non-laser light source devices, are accelerating demand for enclosed, filtered edger architectures. This creates a near-term retrofit market and a longer-term replacement cycle for legacy equipment.
- Labor and skills substitution: Advances in grinding-wheel technology and ergonomic machine design are reducing dependence on skilled hand-finishing while improving throughput for polycarbonate and Trivex lenses. For buyers, this translates into faster payback on automation investments in high-volume settings.
- Service and consumables as recurring revenue: Consumables, spare parts and field service represent the recurring-revenue backbone for leading vendors. Firms with tight aftermarket access to abrasive supplies and local service capability sustain higher lifetime customer value and defensibility.
Competitive landscape — what winners look like
The market features a mix of long-established optical-equipment OEMs and specialized global players. Leadership profiles are differentiated by product breadth, local service networks, and capabilities across in-office versus lab-scale finishing:
- Coburn Technologies (California, USA): Strong in-office portfolio and recent premium in-office launches that emphasize finishing capability for high-curve and hydrophobic lenses. Their focus is on precision finishing and ease-of-use for the retail channel.
- Huvitz Corporation (South Korea): Broad edging systems line-up with recent introductions targeted at sunglass edging and frame-over-lens workflows, reflecting an expansion strategy into North American retail channels.
- Nidek Co., Ltd. (Japan): A high-volume finishing specialist with models oriented to industrial and large-lab throughput, reinforcing strength in automation and integration with upstream measurement systems.
- Essilor Instruments, Visionix/Briot (France): European incumbents with integrated instrument portfolios and strong lab-to-retail channel access; they differentiate through end‑to‑end optical processing ecosystems.
- Regional and emerging suppliers (Italy, China, USA, Japan): Manufacturers such as MEI Srl, Shanghai Supore, Ningbo FLO, Topcon and Innava cover niches from compact block-less edgers to cost-competitive automatic systems, and are increasingly important for price-sensitive and retrofit segments.
Notable recent moves: in 2025 several vendors introduced upgraded premium edgers aimed at specialty lenses and sunglass applications — a clear signal that product innovation is shifting toward higher-margin, feature-rich systems. For specifics on each vendor’s product roadmap and comparative capability matrix, the full report provides a vendor scorecard and benchmarking grid.
Supply chain & technology implications
- Consumables security is strategic: Securing a multi-source supply of premium diamond abrasives or investing in captive grinding wheel capacity is a direct lever to reduce finished‑goods variability and protect service levels.
- Design for compliance: Manufacturers should prioritize enclosed dust management, modular filtration upgrades, and firmware-level compliance to the 2026 safety standard — retrofits will be a major near-term revenue stream for capable OEMs.
- Digital enablement: Connectivity for remote diagnostics, predictive maintenance, and consumable tracking improves uptime and supports subscription/consumable bundling strategies that lock in customers.
- Aftermarket as a differentiator: Service network density, training offerings, and fast consumable replenishment are decisive purchase criteria for high-volume labs and retail chains.
Strategic imperatives for 2026 decision-makers
Executives considering capital allocation, product development, M&A or go-to-market pivots this year should prioritize five lines of action:
- Audit and segment your installed base: Identify retrofit candidates for enclosed filtration and remote-monitoring upgrades — short-term CAPEX conversion projects can yield outsized ROI by extending tenure and meeting regulatory timelines.
- Lock consumables and spare parts channels: Negotiate multi-year supply agreements or co‑invest in abrasion media production to avoid margin erosion and service disruptions tied to abrasive shortages.
- Rebalance product portfolios toward automation and block‑less processing where unit economics and throughput justify investment. For retailers with distributed footprints, compact automatic edgers can accelerate same-day fulfillment capability.
- Invest in aftermarket and digital services: Build remote diagnostics, predictive maintenance, and consumable subscription offers to shift revenue mix toward recurring and higher-margin streams.
- Use M&A tactically: Target niche makers of specialty finishing technology, filtration solutions, or regional service networks to accelerate compliance-ready offerings and local reach.
Practical 90‑day playbook
- Week 1–4: Conduct a rapid installed-base survey to quantify non-compliant legacy units and high-value retrofit opportunities.
- Week 5–8: Engage top abrasive suppliers for capacity commitments; test alternative superabrasive sources to build redundancy.
- Week 9–12: Pilot an enclosed, connected edger in one high-volume outlet; measure downtime, finish yield, and consumable consumption to validate business case for wider roll-out.
What the full PW Consulting report delivers
The complete study is designed as an operational playbook for 2026 and beyond. It contains:
- Proprietary market-sizing and forecast model (2020–2032) with scenario toggles and sensitivity to consumable cost, regulatory adoption rates, and automation uptake.
- Detailed vendor benchmarking, product capability matrices, and pricing archetypes — useful for procurement, competitive planning and RFP preparation.
- Granular segmentation by region, type and application (note: this briefing intentionally omits those segmented figures to preserve the premium value of the full dataset).
- Supply-chain risk maps and recommended mitigation contracts for key consumables (diamond abrasives, coolant systems, precision spindles).
- Regulatory compliance roadmap tied to EN IEC 60601‑2‑57:2026 and localized environmental standards, including retrofit cost curves and timing scenarios.
- Service and consumables monetization frameworks, plus sample commercial terms and contract templates for subscription offerings.
- Investment and M&A screening criteria, plus a short-list of target archetypes aligned to different strategic plays.
How to use this research in board deliberations
Frame capital requests and strategic plans around three questions the report enables you to answer with precision:
- Which assets should be replaced vs. retrofitted this fiscal year to achieve compliance and productivity objectives?
- How much incremental margin can be captured by converting customers to consumable/subscription models?
- Which acquisition or partnership opportunities de‑risk supply and accelerate go‑to‑market in priority segments?
Final note and next step
Eyeglass edging machines remain an essential — but evolving — node in the optics value chain. For executives preparing 2026 capex cycles, the decision levers are clear: secure consumables, accelerate compliance-ready product adoption, and convert installed base relationships into recurring‑revenue service streams. PW Consulting’s full market study provides the granular segmentation, vendor scores and executable templates needed to act; this briefing is a strategic trailer that surfaces the actionable implications while reserving the in-depth tables and models for the full report.
To access the full dataset, vendor scorecards, and the 90‑day implementation kits referenced above, please visit our report page or contact your PW Consulting representative for an executive briefing and model access.
For detailed analysis of this topic, please visit the official page: Eyeglass Edging Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


