



PW Consulting: Air Source Heat Pumps Market to hit USD 80.45B by 2032 with 7.2% CAGR

Air Source Heat Pumps Market 2026: Strategic Preview for Commercial Leaders
As PW Consulting’s chief industry analyst, I present a strategic preview of our full Air Source Heat Pumps Market study — a practical intelligence package designed to influence board-level decisions in 2026. The market for air source heat pumps has moved from niche to mainstream with measurable scale: from roughly USD 34.3 Billion in 2020 to an estimated USD 49.2 Billion in 2025, and a trajectory that reaches around USD 80.5 Billion by 2032. Our forecast period (2026–2032) reflects a compound annual growth rate of 7.2% — a pace that supports decisive investment, capacity planning and competitive repositioning this year.
Air Source Heat Pumps Market
Why 2026 is a Pivot Year
-
Regulatory inflection points and incentive programs converge with maturing technology and supply-chain shifts. Between tightened HFC rules in multiple jurisdictions and upcoming U.S. energy efficiency standards, manufacturers and channel partners must align product roadmaps and go‑to‑market models now to avoid margin compression or market exclusion later.
Air Source Heat Pumps Market -
Macro growth is established and accelerating: the market that was mid‑tens of billions in 2020 is heading toward a near‑hundred‑billion‑scale opportunity within the coming decade. That scale supports vertically integrated plays, aftermarket monetization and new finance models for residential deployment.
Air Source Heat Pumps Market -
At the same time, concentration metrics indicate a market that is neither a pure commodity nor a closed oligopoly — top-three players hold a material share while a broader top-five control close to two‑thirds of market value — creating openings for focused challengers and regional champions.
What the Full Report Delivers (Practical, Actionable)
-
Market sizing and scenario forecasts (2026–2032) with high-resolution sensitivity modelling to show outcomes under different regulatory and incentive scenarios.
-
Go‑to‑market playbooks for manufacturers, distributors and large contractors: pricing anchors, installer economics, midstream incentive capture and channel margin models calibrated to current labor and material dynamics.
-
Technology and refrigerant transition analysis mapping timing and cost-to-serve impacts of R32, R290 and legacy R‑410A phaseouts — including a supplier readiness index to help prioritize supplier qualification or backward integration.
-
Manufacturing and CAPEX decision support: profitability maps for capacity expansions, near‑market manufacturing, and targeted retrofits. The report includes plant retrofit case models and payback timelines under multiple volume assumptions.
-
Competitive landscape with commercial profiles and strategic options for primary incumbents and regional players; an M&A heatmap identifying consolidatable niches and potential bolt-ons for rapid capability acquisition.
-
Regulatory intelligence and compliance roadmaps: jurisdictional trackers, implementation lead times and contingency checklists for product certification, labeling and refrigerant quotas.
-
Installer ecosystem diagnostics and demand-stimulation frameworks including midstream incentive design, OEM-installer partnerships and consumer financing propositions to de-risk household adoption.
Competitive Landscape — Who Matters and Why
-
Global system leaders such as Daikin, Mitsubishi Electric and Carrier combine broad product portfolios with deep distribution channels and R&D depth — they set technology benchmarks (inverter controls, cold-climate optimization) and often lead in regulatory compliance readiness.
-
Major diversified players (Trane Technologies, LG, Samsung, Hitachi, Panasonic) leverage brand, global manufacturing scale and adjacent HVAC offerings to cross-sell and bundle solutions across residential and commercial channels.
-
China‑based mass manufacturers (e.g., Gree) fight on price-performance and rapid scale; their play is cost leadership plus aggressive channel displacement in developing markets.
-
Climate-specialist European firms (Bosch Thermotechnology, NIBE) exploit cold-climate expertise and integration with building‑level thermal systems, focusing on European and high-latitude markets where efficiency and integration matter more than lowest upfront cost.
-
Technology differentiators to watch: variable‑speed compressors, low-GWP refrigerants, integrated hydronic systems, and digital service platforms that enable remote commissioning, predictive maintenance and subscription service models.
Recent Developments That Will Shape 2026 Decisions
-
Capital allocation into manufacturing for advanced components is accelerating. A recent, large retrofit investment by a major manufacturer targets variable‑speed compressor production in North America with an operational timeline into 2027 — signaling manufacturing localization and component control as a strategic priority.
-
Midstream incentive programs are maturing. A notable regional accelerator launched a multi‑hundred‑million‑dollar program (late‑2025) designed to reduce upfront cold‑climate unit costs for installers by several hundred dollars per unit; such programs materially alter installer economics and adoption curves in targeted geographies.
-
Regulatory moves are compressing the window for refrigerant transition: new GWP ceilings and tightened quota systems have already caused sharp cost divergence between legacy and low‑GWP refrigerants in some markets. This drives a two-speed market where compliant SKUs command pricing power and non‑compliant inventories become stranded.
Strategic Imperatives for 2026
-
Prioritize refrigerant and compressor roadmaps now. Product portfolios should be aligned to post‑2026 regulatory thresholds and to logistics‑secure refrigerant supply; delay risks inventory write‑downs and lost access to key markets.
-
Localize critical components or secure long‑term supplier commitments. The capital investments and retrofit programs announced by competitors demonstrate the advantage of proximity to high-growth markets and speed to service.
-
Partner with midstream and installer networks to monetize incentives. OEMs that structure point-of-sale incentives, installer rebates and co‑funded training programs will capture uptake faster and secure longer service lifecycles.
-
Build service, financing and digital offerings to stretch lifetime value. With equipment expected to be standard in more homes and buildings, recurring revenue from service contracts, remote monitoring and financing will be a key differentiator.
-
Adopt scenario-based CAPEX planning. Use the report’s sensitivity models to stress-test manufacturing expansions and SKU rationalization under differing policy and incentive outcomes.
-
Scan for M&A that buys missing capabilities quickly: cold‑climate engineering, inverter control IP, or installer networks. Given the market concentration dynamics, well‑targeted acquisitions can materially change competitive positioning.
How Executives Should Use This Preview
-
CxOs: Use the macro view and regulatory timelines to set investment gating criteria, prioritizing technologies and regions that align with your tolerance for regulatory compliance risk and capital intensity.
-
Heads of Product and R&D: Map SKU rationalization and refrigerant transitions against supplier roadmaps and certification lead times included in the full study.
-
Commercial leaders: Reassess distributor margins and installer economics in light of midstream incentives and the planned energy-efficiency standard updates that take effect later this decade.
-
M&A teams: Leverage the report’s consolidation heatmap to identify targets that accelerate time‑to‑market for compliant, high-margin SKUs and service capabilities.
What We Intentionally Withhold in This Preview
-
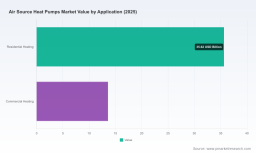
To preserve the commercial value of the primary research and models, this preview omits granular regional, application and type splits and the specific revenue and share figures by segment. Our full report contains the detailed tables and interactive models that quantify those splits and allow you to run custom scenarios for your business lines.
-
We also withhold the detailed rank‑order supplier readiness index and proprietary installer margin curves — these are part of the deliverables for clients who require executable go‑to‑market plans.
Next Steps
-
For executives preparing 2026 budgets, the choice is clear: treat air source heat pumps as a strategic growth engine. The market’s size and 7.2% CAGR across the 2026–2032 forecast window justify near‑term investment in compliant SKUs, supply‑chain resilience and channel economics.
-
Contact PW Consulting to access the full study, interactive financial models and our tailored workshop offerings. We will help convert the market-level opportunity into a prioritized, executable investment roadmap for your organization.
PW Consulting’s Air Source Heat Pumps Market study is built to inform high‑stakes decisions in 2026. It combines market-scale evidence, regulatory foresight and competitor intelligence into operational playbooks that translate opportunity into measurable outcomes. The next step — accessing the full dataset and scenario tools — enables precise planning and decisive action.
For detailed analysis of this topic, please visit the official page: Air Source Heat Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


