



PW Consulting: Gene Therapy Market to Grow at 19.25% CAGR to 2032

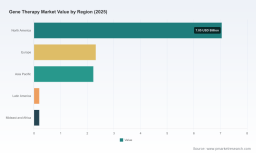
Gene Therapy Market 2026: Strategic Preview for Corporate Decision-Makers
As gene therapy accelerates from pioneering science to scalable commercial reality, executive teams face a compressed window in 2026 to convert technological promise into durable business advantage. PW Consulting’s Gene Therapy Market study — based on a 2025 base year and projecting through 2032 — synthesizes market trajectories, regulatory inflection points, commercial bottlenecks and competitor strategies into an actionable playbook. This preview highlights the research’s strategic value for 2026 decisions, demonstrates the depth of our analysis, and intentionally refrains from publishing the granular segmentation tables that are included in the full report.
Gene Therapy Market
Market snapshot: growth dynamics and structural context
The gene therapy market has moved from nascent to high-growth in less than a decade. Our historical series shows a clear acceleration through 2020–2025 and, with the report’s forecast period spanning 2026–2032, we estimate continued robust expansion at a compound annual growth rate (CAGR) of approximately 19.25% across the forecast window. In practical terms, the market that stood in the single-digit billions in the early 2020s is projected to scale to multiple tens of billions of USD by the early 2030s.
Gene Therapy Market
Two structural characteristics underpin this expansion and should guide 2026 strategy: first, the market remains moderately concentrated at the top, with leading incumbents controlling a meaningful share of commercialized assets and platform capabilities; second, cost and logistics remain non-trivial — ultra-cold chains and biologics-grade inputs continue to represent a material portion of supply chain cost bases, in some cases accounting for roughly one-fifth to two-fifths of total distribution and production costs.
Gene Therapy Market
Why this report matters for 2026 corporate decisions
- Prioritize portfolio bets with quantified upside and risk: With steep growth projected through 2032, companies must distinguish between platform plays (vector development, manufacturing) and product plays (indication-specific therapies). Our model maps revenue potential against timing and probability-of-success to reveal which bets reach break-even within a typical corporate planning horizon.
- Prepare for regulatory acceleration and conditional approvals: In January 2026 regulators signaled increased flexibility in chemistry, manufacturing and control (CMC) requirements for cell and gene therapies, lowering certain entry barriers. The report models how this regulatory shift shortens expected time-to-market for different development strategies and where increased CMC risk persists.
- Design reimbursement and contracting strategies now: High one-time costs for single-dose therapies necessitate innovative payer approaches. The research evaluates outcome-based agreements, annuity and risk-sharing models, and recent policy movements (including proposed expansions to new-technology reimbursement mechanisms) to map realistic revenue realization scenarios across major payers.
- Mitigate supply-chain exposure: Cold-chain logistics and specialized raw materials are concentration points for cost and disruption. We quantify sensitivity of commercial margins to logistics cost shocks and provide sourcing and vertical-integration scenarios that can materially improve gross-margin profiles.
Core strategic imperatives for 2026
- Lock platform flexibility: Build or acquire modular vector and manufacturing capabilities that can serve multiple clinical programs to reduce COGS volatility.
- Negotiate payer-first evidence generation: Embed real-world evidence (RWE) and outcomes-based endpoints into late-stage trials to streamline managed-entry agreements in major markets.
- Design hybrid commercial models: Combine centralized manufacturing for quality consistency with regional fill-finish capabilities to reduce cold-chain miles and tariff exposure.
- Prioritize differentiated indications: Favor indications where clinical differentiation, durable efficacy and manageable patient populations align to justify premium pricing and payer negotiation.
Competitive landscape: what leading players signal
The commercial field combines large diversified biopharma and specialized gene-therapy pioneers. Our competitive analysis focuses on strategic posture—platform depth, commercial execution, and pipeline breadth—rather than confidential sales figures. Highlights from the ecosystem:
- Novartis (Basel): With marketed assets addressing rare neuromuscular disease, Novartis demonstrates the playbook for converting single-product approvals into integrated patient-access programs and manufacturing scale-up. Their experience underlines the importance of post-launch lifecycle management and global reimbursement engagement.
- Bristol-Myers Squibb (New York): As a major oncology and cell-gene therapy participant, BMS illustrates how CAR-T and related modalities can be integrated into existing oncology franchises, leveraging commercial channel synergies and payer relationships to accelerate adoption.
- Janssen Biotech / J&J (Beerse): The company’s multiple myeloma asset underscores opportunities in complex oncology indications where high per-patient value must be balanced with manufacturing throughput constraints.
- Vertex Pharmaceuticals (Boston): Vertex’s advances in hemoglobinopathies demonstrate the strategic value of deep disease expertise and partnerships that facilitate curative-intent development for genetically-defined populations.
- bluebird bio (Cambridge): A specialist with multiple blood-disorder programs, bluebird’s trajectory highlights both the upside of platform-centric innovation and the operational demands of delivering multiple gene therapies to market.
- Sarepta, BioMarin, CSL Behring, Krystal Biotech, PTC Therapeutics: Each firm represents a different go-to-market approach—niche orphan focus, broad rare-disease portfolios, established biologics manufacturing strength, or cutaneous and CNS specialization. The competitive map in the report translates these profiles into likely partnership, M&A and co-development scenarios.
Collectively, market leaders suggest three likely competitive dynamics through 2028: (1) platform consolidation and strategic partnerships around vector supply and manufacturing, (2) regional specialization where companies leverage existing payer relationships, and (3) differentiated commercialization for high-value, one-time treatments with bespoke access agreements.
Regulatory and reimbursement environment — implications for 2026 strategy
- Regulatory adaptivity reduces certain bottlenecks: The FDA’s January 2026 guidance on more flexible CMC pathways should speed several late-stage programs, but companies must still meet product-specific quality expectations. Tactical implication: accelerate CMC investments in parallel with pivotal trials to be market-ready faster.
- Payer models are shifting: Outcome-based managed-entry agreements and proposed expansions of add-on reimbursement mechanisms change the calculus for pricing and cash-flow modeling. Firms that design evidence-generation and contracting capabilities now will capture premium value later.
- Supply chain as a strategic asset: Given that cold-chain and biological raw materials can account for a substantial share of costs, supply-chain resilience has become a competitive moat—especially for players seeking to scale beyond early adopters.
What the PW Consulting report contains (practical deliverables)
The full Gene Therapy Market report is organized to support strategic decision-making across corporate functions. Key deliverables include:
- Market model with annual revenue forecasts (historical 2020–2025 base series and detailed 2026–2032 projections), sensitivity scenarios and break-even analysis for different commercialization pathways.
- Regulatory and reimbursement playbook, including modeled outcomes for outcome-based contracting, NTAP-like mechanisms, and region-specific managed-entry requirements.
- Supply-chain cost mapping and scenarios that quantify the impact of logistics, raw-material pricing and manufacturing scale on gross margins.
- Competitive profiles and strategic positioning matrices for leading firms, including partnership likelihood scores and suggested M&A targets by strategic intent.
- Go-to-market templates for clinical-stage companies covering launch sequencing, stakeholder engagement timelines, and payer negotiation playbooks.
- Appendices with methodological assumptions, data sources and redacted segmentation matrices; the full, unredacted segment-level tables and granular regional/application splits are available exclusively with the report purchase.
How to use these insights in a 2026 boardroom
- Investment committees: Use our model to test valuation scenarios under different reimbursement and manufacturing cost assumptions. Identify the investment tranche that aligns with acceptable payback periods given the expected market growth trajectory.
- Commercial leaders: Build payer engagement roadmaps now that prioritize outcome evidence generation and contract pilots in markets with supportive policy frameworks.
- R&D/CMC teams: Reallocate near-term budgets to derisk CMC readiness in parallel with late-stage clinical activities—regulatory flexibility shortens windows but requires readiness to meet quality and comparability expectations.
- Supply-chain and procurement: Implement dual-sourcing and regional fill-finish strategies to reduce cold-chain distances and improve margin resilience.
Concluding perspective and next steps
Gene therapy will reshape therapeutic categories and payer economics during the remainder of this decade. The market’s projected high-teens CAGR through 2032 signals opportunity at scale — but seizing that opportunity requires early commitment to manufacturing readiness, payer-focused evidence generation, and pragmatic commercial models. PW Consulting’s report consolidates the quantitative forecasts, regulatory and reimbursement mapping, and competitive playbooks needed to chart a defensible path through 2026 and beyond.
For an executive-ready briefing, access to the complete segmentation tables, and the full suite of actionable tools (financial models, negotiation templates, and partnership prioritization matrices), please consult the full Gene Therapy Market report on our website. The preview above is intentionally selective to protect the granular intelligence that differentiates strategic execution from tactical noise.
For detailed analysis of this topic, please visit the official page: Gene Therapy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


