



PW Consulting: Zener Diodes Market to Reach USD 1,063.11 Million by 2032 at 4.2% CAGR

Zener Diodes Market 2026: Strategic Imperatives for Decision Makers
Market snapshot
The Zener diodes market has moved from a compact specialty segment into a core building block of modern power-management and protection architectures. Our baseline analysis (base year 2025) shows the market expanding from roughly USD 654 million in 2020 to USD 797 million in 2025, and, under our central forecast, progressing to approximately USD 1,063 million by 2032. This trajectory represents a compound annual growth rate (CAGR) of 4.2% across the 2026–2032 projection window. That steady, mid-single-digit expansion masks important inflection points—miniaturization, automotive qualification, and transient-protection demand driven by large-scale compute and communications deployments—that will define competitive advantage in 2026 and beyond.
Zener Diodes Market
Why this research matters for 2026 decisions
- Strategic clarity in a fragmented market: With the market exhibiting modest overall growth and a relatively low top-player concentration (CR3 ~25.4%, CR5 ~33.0%), there is room for both incumbents and focused challengers to expand share. However, scale alone is insufficient; product differentiation and go-to-market agility matter more than ever.
- Design-to-supply alignment: 2026 will be the year many OEMs consolidate system-level design choices (power islands, transient suppression strategies, and packaging standards). Choosing a Zener strategy now determines qualification timelines, inventory commitments, and total cost of ownership through 2028.
- Risk calibration against structural shocks: Supply-chain disruptions and demand spikes (notably from AI server motherboard procurement cycles) have and will continue to create asymmetric lead-time and pricing pressures. Buyers who align sourcing and design-in strategies with resilient suppliers will sustain lower product-development friction.
Macro dynamics shaping vendor and buyer strategies
- Miniaturization and packaging technology: Leadless and sidewall-plated packages such as DFN variants are becoming standard in designs where board real estate is constrained. Suppliers introducing robust, miniaturized packages gain preferential design-ins for portable and space-constrained applications.
- Automotive and reliability qualification: AEC-Q101 and PPAP capability are now de facto requirements for suppliers targeting automotive and certain industrial segments. Products with explicit automotive qualification reduce customer lead time to production and unlock higher-margin segments.
- Precision and low-noise variants: Tight-tolerance devices (±1%–±2%) and low-bias-current series are moving from niche to mainstream as sensor interfaces and high-speed digital front ends demand cleaner, more predictable clamping and regulation behavior.
- Supply chain pressure points: Recent industry data indicate dramatic lead-time inflation for certain suppliers—where single-digit-week leads stretched into the 48–52+ week band—while pricing rose materially (noted increases around 20% in affected lines). This dynamic is concentrated in components servicing AI compute and similar high-velocity markets, but the spillover affects broader supply availability and commercial terms.
- Process control and manufacturability: Suppliers demonstrating high maturity (for example, validated Cpk metrics in qualification runs) materially reduce qualification risk and offer a faster ramp to production. This is a decisive selection criterion for large OEMs.
Competitive landscape — what to watch in 2026
The competitive field mixes global diversified semiconductor houses with focused discrete specialists. Across the leading players we track, several capability tiers and strategic postures have emerged:
Zener Diodes Market
- Broad portfolio and systems play: Companies such as Texas Instruments and Microchip position Zener diodes within a broader protection and power-management portfolio. Their recent product introductions and data-sheet promotions in early 2026 underscore an integrated protection strategy that speaks to system architects seeking single-vendor simplicity.
- Form-factor and precision differentiation: Vishay and Diodes Incorporated are leveraging packaging and process improvements—leadless DFN packages, sidewall plating, and ion-implanted epitaxial processes—to offer smaller, tighter-tolerance devices. These moves address miniaturization and precision demands in consumer, industrial, and automotive segments.
- Automotive and reliability-focused specialists: Toshiba and Nexperia are pushing AEC-Q101-qualified lines, ±1% tolerance families, and low-bias/low-noise variants explicitly aimed at automotive and high-reliability industrial applications. Their product roadmaps shorten qualification cycles for customers that require PPAP-capable supply.
- Discrete and transient protection specialists: onsemi and other discrete-focused vendors continue to compete on transient robustness, multi-device configurations (e.g., dual common-cathode), and portfolio depth for power-management customers.
Recent product and portfolio moves bear attention: Texas Instruments’ 2026 introduction of Zener devices as part of an expanded protection lineup, Toshiba’s November 2025 CMZBxxA series for surge and switching protection, Vishay’s October 2025 DFN1006-2A package expansion, and Diodes Incorporated’s December 2025 tight-tolerance surface-mount updates all signal where customer demand and R&D investment are converging.
Zener Diodes Market
Strategic implications and recommended actions for 2026
- Supplier portfolio optimization: Blend a small set of high-capability, automotive-qualified suppliers with a flexible second-tier network to balance qualification speed and price leverage. Prioritize suppliers demonstrating mature process control metrics and who communicate lead-time transparency.
- Design-for-availability: Standardize on a limited set of package families and tolerance classes across platforms to ease cross-platform inventory pooling and allow rapid substitution if a supplier experiences capacity constraints.
- Qualification acceleration: Invest in concurrent qualification tracks (parallel lab, reliability and in-system testing) to reduce time-to-production. When suppliers offer AEC-Q101 or PPAP-capable parts, fast-track those options for automotive/industrial programs.
- Value-based pricing and cost-to-serve: For manufacturers, capture margin by offering differentiated variants (e.g., ±1% tolerance, low-noise lines, automotive-grade) at premium price points. For OEM buyers, conduct lifecycle TCO assessments—factoring yield improvements and MTBF benefits from higher-grade Zener solutions—rather than accepting unit-price as the sole procurement metric.
- M&A and partnership focus areas: Target capabilities that accelerate miniaturized packaging, advanced process technologies (ion implantation, planar silicon), or capacity for automotive-qualified runs. Strategic partnerships with wafer-foundries or packaging specialists can shorten lead-time volatility exposure.
- Scenario planning for compute-driven demand shocks: Model inventory and contractual terms around plausible AI/data-center procurement spikes. Hedging strategies, capacity pre-booking, and dual-sourcing are practical mitigants against the demonstrated risk of price and lead-time shocks.
What PW Consulting’s Zener Diodes Market report contains (practical, execution-focused)
This study is built for 2026 decision-makers who need both a strategic view and executable detail. The report combines:
- Market sizing and trend analysis across a 2020–2032 horizon with scenario variants calibrated to demand shocks and adoption accelerators.
- Supply-chain risk maps and mitigation playbooks (lead-time stress testing, contractual levers, inventory optimization heuristics).
- Product and technology roadmaps highlighting packaging, process, and tolerance innovations and their likely adoption timelines.
- Vendor benchmarking and heat maps (capability, qualification, vertical focus, and commercial behavior) with raw vendor data and contactable profiles for procurement teams.
- Actionable go-to-market modules: a buyer’s checklist for qualification, a supplier scorecard template, and a sample RFP language set tailored for automotive and high-reliability programs.
- Commercial scenarios and pricing elasticity models to support negotiation and sourcing strategies under volatile demand conditions.
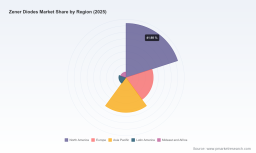
Note: this article intentionally omits the granular regional, type, and application splits and the full numerical segmentation tables that are included in the report. Those detailed breakdowns are critical for SKU-level sourcing and program planning and are available in the full report materials.
How to use these insights in 2026
- CEOs and business-unit leaders: Use the market trajectory and concentration metrics to set portfolio priorities—scale up investment where differentiation yields premium positioning, and de-emphasize commoditized low-margin offerings.
- Procurement and supply-chain leaders: Implement lead-time and price-stress scenarios drawn from the report to define contract terms, safety-stock levels, and dual-sourcing triggers.
- R&D and product teams: Prioritize development on tight-tolerance, low-noise, and automotive-qualified variants and choose packages aligned with customer roadmaps for miniaturization.
- M&A teams: Leverage the report’s gap analysis to identify acquisition targets that fill capability or capacity shortfalls—especially in packaging, process technology, or automotive qualification lanes.
Conclusion — an executive roadmap for 2026
The Zener diodes market in 2026 is characterized by steady growth, pockets of rapid demand-driven stress, and clear technical vectors—miniaturization, automotive qualification, and precision variants—that separate winners from the rest. With a market base approaching USD 800 million in 2025 and an expected climb to about USD 1.06 billion by 2032 at a 4.2% CAGR, companies must choose between chasing scale in a fragmented space or establishing defensible differentiation through qualification, packaging, and process excellence.
PW Consulting’s full Zener Diodes Market report provides the granular segmentation, supplier-level data, and scenario modeling necessary to operationalize these strategic choices. For teams that must convert insight into procurement tactics, product roadmaps, or M&A targets in 2026, the complete dataset and templates in the report are designed to accelerate decision velocity while de-risking execution.
Next step
To access the detailed segmentation tables, supplier scorecards, and executable playbooks referenced here, please consult the full report materials available on our publication page.
For detailed analysis of this topic, please visit the official page: Zener Diodes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


