



PW Consulting: EPS Market to Reach USD 397M by 2032 at 5.57% CAGR

Automotive Electronic Power Steering Market — Strategic Primer for 2026 Decision-Makers
By PW Consulting — Senior Strategy & Industry Analysis
Automotive Electronic Power Steering Market
Executive preview
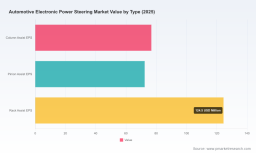
The transition to electric, software-defined, and safety-integrated steering architectures is no longer a distant industry storyline — it is the operating context for 2026 planning cycles. Our Automotive Electronic Power Steering (EPS) Market study (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes market sizing, supplier strategy, regulatory dynamics, technology inflection points and procurement playbooks into an actionable roadmap for OEMs, Tier‑1 suppliers, investors and policy teams. The market grew from approximately USD 198.0 Million in 2020 to USD 273.7 Million in 2025 and is forecast to expand to USD 286.6 Million in 2026 and reach roughly USD 397.0 Million by 2032, implying a compound annual growth rate (CAGR) of about 5.57% over the forecast horizon. Market concentration remains high: the top three firms control an estimated 78% of reported revenues, while the leading five account for around 90% — a structural characteristic that shapes negotiating power, innovation diffusion, and M&A dynamics.
Automotive Electronic Power Steering Market
Why this study matters for 2026 strategy
Two planning realities define urgency in 2026. First, regulatory and safety mandates are accelerating EPS adoption and functional complexity, converting what was a mechanical cost‑center into a strategic chassis and software development area. Second, architectural convergence (EPS + ADAS + steer‑by‑wire readiness) is creating winner-take-disproportionate returns for suppliers who can deliver integrated, validated systems at scale. Our research translates those realities into three pragmatic decision levers for 2026:
Automotive Electronic Power Steering Market
- Resource allocation: whether to build, buy, or partner for steer‑by‑wire and torque‑overlay capabilities;
- Supplier strategy: how to structure long‑term contracts, local footprint and co‑development terms to secure supply and update cycles; and
- Product and IP planning: where to invest in sensor fusion, solid‑state sensing, and software safety stacks to protect up‑front engineering spend and post‑launch margins.
Market trajectory and implications
The EPS market has demonstrated resilient expansion through 2020–2025, accelerated by electrification and CO2 compliance drivers. The modest but steady CAGR of 5.57% forecast for 2026–2032 masks important structural shifts: unit growth is being compounded by rising electronic content per vehicle, higher validation costs for safety-rated torque overlay, and the premium commanded by steer‑by‑wire subsystems. For 2026 boardrooms, the implication is clear — growth is not simply about volume; it is about value capture within the system stack (mechanical, electromechanical, power electronics, and software).
Regulatory and standards tailwinds
Recent regulatory moves materially reshape product roadmaps and procurement criteria. Notable policy inflection points include tightened CO2/efficiency regimes and new safety assessment protocols that implicitly favor electronic steering solutions over hydraulic systems. Additionally, vehicle safety rating bodies now treat lane‑keeping assistance functionality as a rated feature, which creates technical prerequisites (such as EPS torque overlay and redundancy) for OEMs seeking premium safety scores. These regulatory constraints convert product reliability and software determinism into commercial differentiators.
Technology convergence and supply‑chain effects
Material advances (higher‑strength gear materials, precision manufacturing) and sensor evolution (solid‑state and sensor‑fusion approaches) are simplifying architectures while improving NVH and durability. At the same time, steer‑by‑wire development is transitioning from lab demonstrations to series production — an inflection that carries new supplier roles (actuator integrators, backup power architects, safety‑certified software houses). This convergence amplifies two operational realities for 2026:
- Up‑front validation budgets and functional safety certification timelines will constitute a larger share of program CAPEX, necessitating earlier alignment between OEM system architects and chosen Tier‑1 partners;
- Sourcing strategies must incorporate software SLAs, cybersecurity roadmaps, and hardware redundancy plans in addition to traditional mechanical supply metrics.
Competitive landscape — what the leading players signal
The EPS supplier base shows a dual structure: a small group of global incumbents with system breadth and validation depth, and a broader tier of regional specialists focusing on cost and volume. Key global players include established system integrators and component specialists that are actively competing on system performance, ADAS integration and steer‑by‑wire readiness. Recent industry movements underline who is closest to commercialization and how competition is evolving:
- Nexteer Automotive: expanding its product suite for heavier vehicles and moving to series production for steer‑by‑wire programs — an indicator that full drive‑by‑wire is pushing into mainstream OEM platforms.
- Robert Bosch GmbH and ZF Friedrichshafen AG: continuing to iterate on integrated EPS+ADAS solutions and leveraging their systems know‑how to anchor OEM relationships across vehicle segments.
- Japanese incumbents (NSK, JTEKT, Denso): emphasise precision, force‑feedback and backup power solutions, with validated subsystems already embedded in premium BEV and PHEV programs.
- Asia‑Pacific suppliers (Mando, Hyundai Mobis, China Automotive Systems): pursuing aggressive volume and localization plays, evidenced by recent volume shipments and regional contract awards.
These dynamics produce a two‑track competitive field. Track one: system integrators that compete on validated steer‑by‑wire platforms and safety‑certified software ecosystems. Track two: high‑volume suppliers that deliver cost‑optimized EPS iterations for mainstream platforms but must now invest to remain relevant as content per vehicle rises.
Recent developments — what they reveal about timing and risk
Concrete examples from 2025–2026 reveal the timing of commercialization and the nature of contract opportunity windows:
- A leading supplier’s series production launch of a steer‑by‑wire system in 2026 signals that certification and OEM validation cycles are moving from multi‑year pilot phases into production ramps; procurement teams should expect new qualification gates on supply contracts.
- Product portfolio expansions and OEM validations in 2025–2026 show that suppliers are layering high‑output and backup solutions into existing product families, compressing the time between prototype and production readiness.
- Volume shipment contracts between regional suppliers and global OEMs demonstrate that localization and scale are win conditions in certain geographies — and that cost pressures remain front and center despite added electronic content.
Taken together, these moves indicate that 2026 is an inflection year where early movers will capture platform positions and late movers face elongated, more expensive catch‑up investments.
Actionable intelligence contained in the full study
The report provides operational tools designed to shorten decision cycles and de‑risk investments:
- Proprietary market sizing and scenario model (USD, revenue unit: Million) that allows users to run sensitivity analyses across regulatory, material cost, and pace‑of‑adoption assumptions for 2026–2032;
- Supplier scorecards and supplier SWOTs focused on systems delivery, functional safety track record, software capability and global footprint;
- Program playbooks covering build vs. buy thresholds, qualification milestones, and sample contract terms for tiering and co‑development;
- Risk heatmaps and mitigation blueprints for supply chain, IP, and regulatory compliance; and
- Financial impact snapshots for OEMs and suppliers showing margin implications of increased ESW (electronic steering weight) and validation overhead.
The full deliverables include an interactive Excel model, a procurement checklist for 2026 programs, and a buyer’s guide to structuring partnerships around steer‑by‑wire and torque‑overlay requirements.
Strategic recommendations for 2026 planning
Based on the synthesis of market growth, competitive positioning and regulatory pressures, PW Consulting advises stakeholders to prioritize the following actions this year:
- Establish a clear systems roadmap that aligns EPS hardware and software milestones with ADAS development timelines — treating steering as a joint mechanical‑software program rather than a discrete hardware procurement.
- Secure at least two qualified suppliers for critical EPS subsystems to mitigate single‑point risks, and negotiate staged IP/royalty sharing to balance upfront engineering costs with long‑term licensing exposure.
- Invest selectively in solid‑state sensing and actuator reliability testing facilities or partner with test houses to shorten validation cycles and improve time‑to‑market.
- For investors and M&A teams: prioritize targets that combine software safety stacks with scalable actuator manufacturing; for OEMs: favor suppliers with demonstrated series production capability for steer‑by‑wire if premium safety and autonomy packages are strategic priorities.
- Embed regulatory monitoring into project gating. With emission and safety protocols now directly influencing steering architecture decisions, early regulatory alignment avoids late redesigns and resale impact.
Closing — the strategic value of this research
The EPS ecosystem is evolving from a component market to a systems battleground. For 2026, decisions about engineering investment, supplier structure and platform differentiation will determine whether organizations capture the increased electronic content value, or become price takers in a concentrated supplier market. Our study offers a pragmatic, scenario‑based foundation for those decisions: robust market sizing (USD, revenue unit: Million), competitor diagnostics, regulatory impact mapping, and a practical set of procurement and engineering playbooks. This briefing demonstrates the depth of analysis you can expect; the full report contains the confidential, segment‑level data and interactive models necessary to operationalize strategy. Visit our source page to access the complete study and the supporting analytical toolkit.
For detailed analysis of this topic, please visit the official page: Automotive Electronic Power Steering Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


