



PW Consulting: Flexible Pipes for Oil & Gas Market Set to Reach USD 2,292M by 2032; 6.5% CAGR

Flexible Pipes for Oil & Gas: Strategic Imperatives for 2026 — A PW Consulting Executive Brief
As the global energy industry transitions into a more complex mix of conventional and low‑carbon strategies, flexible pipes retain an outsized strategic role. PW Consulting’s latest market study — anchored on a 2025 base year and validated across a 2020–2025 historical window — shows the industry growing at a compound annual growth rate (CAGR) of 6.5% through our 2026–2032 forecast. The total addressable market expanded materially in the first half of the decade and is projected to reach approximately USD 2.3 billion (Million-USD unit) by 2032. This brief distils the study’s executive takeaways and explains how the full analysis should inform capital allocations, supplier strategies, and technology bets in 2026.
Flexible Pipes for Oil and Gas Market
Why this study matters for 2026 decisions
- Timing of investment: The market’s steady mid‑single-digit CAGR and the uneven distribution of project awards mean that 2026 will be a decisive year for de‑risking supply and capacity commitments. Early movers who align procurement with validated demand scenarios will capture outsized share while preserving margin.
- Supplier selection & resilience: Consolidation dynamics and capacity constraints have concentrated market power among a few global vendors (our analysis shows the top three players capture a substantive share of market revenue, with the five largest firms controlling a clear majority). Procurement teams must balance performance, certification pedigree, and strategic optionality when selecting partners.
- Material & cost exposure: Polymer feedstock pricing — driven by petroleum derivatives — is a primary margin lever. Firms that adopt active raw‑material hedging, multi‑material qualification, and localized sourcing will protect margins through 2026’s procurement cycles.
- Regulatory and technical gating factors: Compliance with ISO 13628 series and API 17J remains non‑negotiable for unbonded flexible systems. Buyers and technology developers should prioritise certification roadmaps as milestones in R&D and delivery schedules.
What PW Consulting’s full study delivers (practical, actionable)
- Proprietary market sizing and validated historical series (2020–2025) plus scenario‑based forecasts to 2032, with transparent methodology and sensitivity parameters for price, CapEx cycles, and offshore activity.
- Supply‑chain and capacity maps highlighting manufacturing bottlenecks, lead‑time drivers, and logistics choke points for subsea and onshore deployments.
- Cost models down to raw‑material exposure (polymer cost curves), manufacturing overheads, and freight/installation imprints — delivered as downloadable Excel workbooks for quick internal modelling.
- Regulatory matrix and certification playbook outlining timelines and resource implications for ISO 13628 and API 17J compliance, including test‑matrix prioritisation for new materials.
- Vendor benchmarking and capability heatmaps covering technology stack, manufacturing footprint, project track record, and commercial playbooks (bid tactics, warranty structures, and liability exposure).
- M&A and partnership intelligence: target screens, valuation perimeter templates, and integration checklists tuned to flexible‑pipe technologies and composite alternatives.
- Commercial templates and negotiation levers for long‑lead equipment, including recommended contract clauses that protect buyers against polymer price and supply volatility.
- Scenario playbooks: stress‑tested plans for accelerated deepwater build‑out, CO2‑rich field development, and a slower demand path tied to energy transition outcomes.
Competitive landscape — who matters and why
The market is anchored by a set of global system integrators and specialised composite suppliers. Our competitive assessment combines technical capability, commercial footprint, and recent go‑to‑market moves to create an actionable picture for 2026 planning.
Flexible Pipes for Oil and Gas Market
- TechnipFMC (UK): A world leader in flexible-pipe design and supply for subsea risers and flowlines. Recent large contract awards for gas injection risers and combined riser/flowline packages underscore its continued strength on large, integrated offshore projects. For buyers, TechnipFMC represents a low‑execution‑risk partner for complex, deepwater scopes.
- National Oilwell Varco (NOV, USA): NOV has been aggressive on product development, launching high‑pressure flexible pipe lines and entering pre‑commercial agreements for CO2‑resistant solutions with major operators. NOV’s moves make it a technology‑centric option for fields with elevated CO2 or high‑pressure service requirements.
- Baker Hughes (USA): As an established supplier of risers, flowlines, and jumpers, Baker Hughes remains visible in trade shows and industry fora, signalling continued emphasis on system completeness and aftermarket services — a key differentiator for operators seeking single‑vendor accountability.
- Specialist composite players (Strohm, SoluForce, Magma): These firms are advancing bonded thermoplastic and carbon‑fibre composite alternatives. Their offerings are increasingly relevant for projects that prioritise weight reduction, fatigue performance, or aggressive chemical environments. Expect selective partnerships with majors on early‑adopter field trials.
- Established diversified suppliers (ContiTech, Shawcor, Prysmian): These vendors provide industrial‑scale manufacturing and broad product portfolios. They are often competitive on price and logistics for high‑volume onshore and nearshore applications.
Collectively, the top three players capture a significant slice of the market, while the top five widen that concentration further — a structure that shapes competitive dynamics, pricing, and procurement leverage.
Flexible Pipes for Oil and Gas Market
Key market dynamics and risks to monitor in 2026
- Material volatility: High‑density polyethylene remains the dominant raw material platform for flexible systems; material price swings directly alter production economics. Companies should model polymer price scenarios as a first‑order sensitivity in capex and pricing strategies.
- Deepwater acceleration and steel substitution: Continued deepwater developments and a preference for polymer/composite replacements for certain steel components are meaningful demand drivers, but they require demonstrable life‑cycle performance and qualification evidence.
- Standards and certification: ISO and API standards are gating factors for acceptance on many projects. Late or under‑resourced certification programs are a common cause of project slippage and cost overruns.
- CO2 and aggressive chemistries: Fields with high CO2 concentrations are catalysing innovation in CO2‑resistant flexible solutions. Early movers in material qualification will secure first‑mover advantage on niche but high‑value projects.
- Supply and capacity risks: Lead times for specialised manufacturing, coupled with concentrated fabrication capacity, create upside risk in a rapid demand cycle; conversely, a demand pause exposes high‑fixed‑cost producers to margin compression.
How executive teams should use the report in 2026
- Investment prioritisation: Use our scenario outputs to identify which project portfolios warrant bespoke flexible‑pipe investment, and which are better served by contracted supply or composite trials.
- Sourcing & contracting: Adopt our contract templates and supplier scorecards to lock down multi‑year supply with price‑adjustment mechanisms tied to polymer indices and milestone‑based acceptance tests.
- Technology strategy: Prioritise R&D spend on qualification areas with fastest path to commercial acceptance (CO2 resistance, fatigue life, and third‑party certification).
- M&A and partnerships: Leverage our target screens and integration playbooks to identify bolt‑on acquisitions that fill capability gaps (e.g., composite fabrication, testing labs, or regional spool capacity).
- Risk management: Integrate the report’s stress cases into CapEx approval processes and board reporting to ensure that downside scenarios are modeled in funding and contract structures.
What we intentionally withhold here — and why
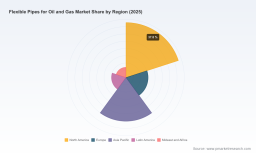
To preserve actionable value for decision makers, this executive brief demonstrates the study’s methodological rigor and strategic implications while intentionally refraining from publishing granular regional and application‑level splits or core segment dollar amounts. Those detailed breakdowns — including regional market allocations, type/application perfor‑mance, vendor scorecards with quantitative rankings, and the downloadable modelling workbooks — are contained in the full PW Consulting report and interactive dashboard. This “teaser” approach is designed to give you clear insight into the study’s conclusions and to protect the ready‑to‑use intelligence that will inform bidding, sourcing, and M&A activity.
Next steps — making the study work for your 2026 plan
- Request the full report and the accompanying Excel models to run company‑level scenario tests against our base, upside, and downside forecasts.
- Schedule a tailored workshop with our market and technical teams to align vendor strategies, certification roadmaps, and procurement timelines to your project milestones.
- Use our vendor benchmarking to short‑list partners for pilot programmes on CO2‑exposed or deepwater fields where material and fatigue performance are critical.
PW Consulting’s Flexible Pipes for Oil & Gas Market study is structured to be immediately operational for 2026 decision cycles — translating market forecasts, standards compliance, vendor positioning, and material economics into executable procurement, investment, and R&D choices. To access the full datasets, vendor scorecards, and downloadable modelling tools, please visit the PW Consulting report portal or contact our industry team to arrange a private briefing.
For detailed analysis of this topic, please visit the official page: Flexible Pipes for Oil and Gas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


