



PW Consulting: Convenience Store Software to hit USD 251.2M by 2032 at 4.19% CAGR

Convenience Store Software Market: Strategic Imperatives for 2026 — A PW Consulting Preview
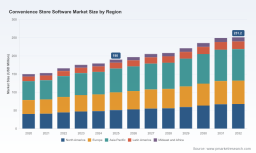
As convenience retail operators confront accelerating margin pressure, evolving consumer expectations, and heavier regulatory burden, software decisions are moving from tactical IT projects to central commercial strategy. PW Consulting’s latest market study — anchored to a 2025 base year and a 2026–2032 forecast window — quantifies that shift and translates it into executable choices for 2026. The global Convenience Store Software market grew from USD 150 million in 2020 to USD 190 million in 2025 and, under current trajectories, is projected to approach roughly USD 251 million by 2032, representing a compound annual growth path consistent with a mid-single-digit expansion (4.19% CAGR for the forecast interval).
Convenience Store Software Market
Why this research matters to executive decision-makers in 2026
-
Timing maturation vs. disruption: The market is no longer nascent. A steady multi-year climb confirms the technology stack for convenience stores is transitioning from pilot-stage capabilities to enterprise-grade platforms. Strategic buyers must decide in 2026 whether to adopt now to capture operational leverage or to defer and risk integration penalties later.
Convenience Store Software Market -
Investment calibration: With a predictable market growth path through 2032, capital planning can shift from ad-hoc modernization budgets to phased digital roadmaps aligned with revenue uplift, cost-to-serve reductions, and compliance risk mitigation.
Convenience Store Software Market -
Vendor differentiation is sharpening: Our analysis shows a field of specialized suppliers and platform-scale incumbents competing on cloud enablement, AI-driven automation, and verticalized workflows (fuel, tobacco, foodservice). Procurement strategies must therefore weigh feature fit, integration cost, and operational change management rather than price alone.
Key market dynamics shaping 2026 choices
-
Cloud adoption and composable architectures: Cloud-first deployments are accelerating replacement cycles for legacy on-premises systems. For most operators, the cloud promises faster feature delivery, lower upfront capital, and simpler compliance updates — especially pertinent where fiscal/tax complexities are endemic.
-
AI and automation moving beyond experimentation: Labor shortages and high turnover in the c-store workforce are pushing operators to adopt AI for scheduling, demand forecasting, and frontline decision support. Expect 2026 to be the year where pilots scale into working controls that materially reduce shrink and labor cost volatility.
-
Regulatory and data-privacy friction: Rising regulatory complexity — from health-safety mandates to regional privacy regimes — is creating product and process requirements that bind vendor choices. Software that embeds compliance-by-design will save operators substantial remediation costs.
-
Integration with fuel, loyalty, and foodservice ecosystems: Convenience stores are multi-proposition environments. Successful platforms are those that unify point-of-sale, inventory, loyalty, and fuel operations into coherent workflows, reducing reconciliation effort and improving basket-level analytics.
-
Moderate market concentration, active innovation: The landscape features both niche specialists and large retail-software providers. Competitive intensity is focused on ease of deployment, vertical feature sets, and partnership networks rather than pure price wars.
What the PW Consulting report delivers (practical, operational content)
-
Executive playbooks: Decision frameworks for selecting between cloud-first, hybrid, and legacy renewals mapped to operator size, site complexity, and risk appetite.
-
Vendor diagnostic and scorecards: Comparative assessments across product maturity, roadmap alignment, total cost of ownership (TCO) modeling, and integration readiness — with guided weighting templates you can reuse in vendor selection.
-
Implementation roadmaps: Phased migration timelines (pilot → regional rollout → enterprise) including realistic cutover windows, staging configurations for multi-site operators, and a catalog of common pitfalls and mitigations.
-
Operational KPIs and ROI levers: A focused set of metrics and short-run experiments that drive measurable improvements in shrink, labor productivity, and incremental sales from loyalty/foodservice upsell.
-
Compliance and data governance guide: Practical templates for privacy-impact assessments, vendor contract clauses for data residency, and employee training checklists tied to regulatory hot spots.
-
Scenario-based financial models: TCO and payback calculators that quantify choices across deployment types and integration complexity — designed for direct insertion into 2026 capex and operating budgets.
Note: In this preview we outline directions and strategic themes. The full report contains granular regional and application splits, vendor scorecards, and downloadable dashboards. We intentionally withhold those tables here to preserve the actionable exclusivity of the full dataset.
Competitive landscape — who to watch in 2026
The competitive field is defined by a mix of focused convenience retail specialists and broader retail-software incumbents. A short guided tour of representative players highlights how different strategies create differentiated value.
-
AccuPOS (US) — positions itself with c-store-tailored POS and inventory modules that appeal to smaller chains and franchise operators seeking rapid deployment and ease of use.
-
SSCS (US) — specialized in inventory accuracy and back-office controls; attractive to operators prioritizing shrink reduction and reconciliation automation.
-
PDI Technologies (US) — leverages deep fuel and back-office domain expertise to serve integrated fuel-and-convenience operations; differentiation stems from fuel-tax logic and retail accounting workflows.
-
POS Nation (US) — brings bundled POS-hardware solutions designed for rapid rollouts at scale where standardization and predictable support models matter.
-
ADD Systems (South Korea) — focused on wholesale inventory and logistics for fuel-centric convenience models, often chosen in regions where vertical integration matters.
-
DataMax (US) & CStorePro Inc. (US) — emphasize reporting, cloud POS, and operational analytics for chains that want quick insights without building internal BI teams.
-
SHENZHEN KEMAI (China) — competes on cost-effective POS hardware and integrated management suites in markets sensitive to price and speed of deployment.
-
Petrosoft (US), Paytronix (US), and GK Software (US) — represent adjacent value propositions: fuel/c-store operations, loyalty/customer engagement, and omnichannel retail systems respectively; each is extending into convenience retail via verticalized modules.
-
NCR Voyix (US), Oracle (US), and Toshiba Global Commerce Solutions (Japan) — global incumbents with enterprise-grade POS and ERP capabilities, attractive to the largest multi-national operators that require scale, SLAs, and global support networks.
-
Tote.ai (US) — notable for rapid innovation in AI-driven POS and kiosk solutions; recent strategic partnerships (announced in early 2026) highlight how AI-enabled front-end automation is moving into mainstream deployments.
Recent market activity underscores two dynamics in particular: (1) partnerships and pilots around AI POS and kiosks are graduating to commercial rollouts, and (2) trade-show demonstrations and provider roadmaps announced throughout 2025 are translating into 2026 procurement decisions. Operators should expect a wave of platform upgrades driven by both competitive necessity and regulatory demand.
Practical recommendations for 2026 strategy and execution
-
Prioritize compliance-first selections: Choose platforms that can demonstrably implement regional privacy and fiscal rules quickly. The cost of retrofitting compliance after deployment is typically higher than incremental premium paid at selection.
-
Adopt a phased modernization path: Start with pilot clusters that capture typical site complexity (fuel, foodservice, loyalty) to validate integration templates before broader rollouts.
-
Design integration around customer journeys: Ensure POS, loyalty, and inventory share a common data model; investments that improve “basket intelligence” yield disproportionately high ROI on marketing and assortment.
-
Factor in total cost and hidden switching costs: Evaluate vendors on migration tools, data migration support, and third-party ecosystem integrations rather than headline licensing fees alone.
-
Treat AI as operational augmentation: Automate routine tasks (scheduling, reorder triggers) first, and phase predictive models (demand forecasting, dynamic pricing) once data hygiene is proven.
-
Use procurement as a lever for partnerships: Negotiate pilot-to-rollout clauses, SLA-based payments, and performance incentives tied to measured shrink/lift impacts.
Methodology and confidence
PW Consulting’s study synthesizes historical market activity (2020–2025), primary interviews with operators, vendors, and systems integrators, quantitative vendor intelligence, and scenario-based forecasting across the 2026–2032 horizon. Our forecast incorporates rate-of-adoption assumptions validated against transaction-level metrics collected from operators across major markets. The resulting view balances near-term disruption risk with medium-term stabilization, reflecting a market that is large enough to matter to executive agendas but still fragmented enough to reward strategic clarity.
To preserve the commercial utility of the full dataset, this preview omits granular regional, type, and application splits — these are provided in interactive form in the full report along with downloadable vendor scorecards, implementation timelines, and TCO models.
Conclusion — the choice for 2026
For 2026, convenience store operators face a clear strategic fork: accelerate modernization now to capture operational uplift and competitive differentiation, or delay and accept higher future switching costs and regulatory exposure. PW Consulting’s research shows that, given a predictable growth trajectory and an increasingly capable vendor ecosystem, early movers who pair cloud-enabled platforms with disciplined integration and change management will realize the greatest economic upside through 2032.
For operators, investors, and solution providers preparing 2026 strategies, the full PW Consulting Convenience Store Software Market report provides the operational tools, vendor diagnostics, and scenario models needed to convert insight into measurable outcomes. Access the full findings and interactive datasets through PW Consulting’s report page to move from strategic intent to executable plans.
For detailed analysis of this topic, please visit the official page: Convenience Store Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


