



PW Consulting: Glass Recycling Market to hit USD 5.88B by 2032 at 5.66% CAGR

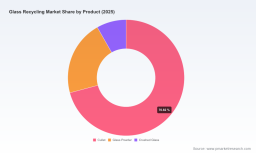
Glass Recycling Market — Strategic Briefing for 2026: Why PW Consulting’s Analysis Matters
Executive snapshot
Between 2020 and 2025 the global glass recycling market more than doubled in headline valuation, expanding from approximately USD 2.05 Billion to USD 4.01 Billion (base year 2025). Our forecast through 2032 points to continued, steady expansion — reaching roughly USD 5.88 Billion by 2032 — representing a compound annual growth rate of 5.66% across the 2026–2032 forecast window. These topline dynamics reflect an ecosystem responding simultaneously to policy pressure, energy-and-cost imperatives, and fast-evolving industrial use-cases for recycled glass feedstock.
Glass Recycling Market
As PW Consulting’s lead industry analyst, I prepared this briefing to explain the practical decision-making value of our full Glass Recycling Market study for corporate leadership and investors making choices in 2026. Consider this a high-fidelity preview: we will show the analytical thinking and the risk/return frameworks you need to trust our work, while preserving the tactical segment-level data behind our paywall so that you are incentivized to access the full study for execution.
Glass Recycling Market
Why this report turns 2026 decisions from reactive to strategic
- Investment timing and sizing: The market’s transition from USD ~4.0B in 2025 toward an anticipated ~USD 5.9B in 2032 creates windows for entry, scale-up, and tuck-in acquisitions. Our modelling identifies where near-term capacity constraints and demand pulls create premium spreads for high-quality cullet — critical for capex prioritisation.
- Cost-to-carbon optimization: Each incremental increase in cullet content meaningfully lowers furnace energy consumption (industry evidence shows a near 3% furnace energy drop for every 10% increase in cullet in the batch). The report translates those process efficiencies into EBITDA and capital-return implications for glassmakers and recyclers.
- Regulatory compliance planning: New legislation and target-setting — for example, the Packaging and Packaging Waste Regulation that sets aggressive glass packaging recycling targets — materially alter demand for certified recycled feedstock and create compliance-driven procurement markets. Our scenario maps show timing, likely compliance costs, and procurement options.
- Supply chain and feedstock security: Infrastructure realities, such as the fact that a meaningful share of collected glass is not accepted at material recovery facilities when commingled in single-stream systems, drive a two-track strategy: invest in separations & logistics vs. vertical integration into collection and processing. We quantify trade-offs for both approaches.
- M&A and competitive positioning: The market is consolidating (our concentration metrics place the top three and five players as material influencers on pricing and standards). The full report includes acquisition scorecards and integration playbooks to turn M&A into value creation rather than replacement spending.
What the full report contains — pragmatic, transaction-ready tools
PW Consulting’s Glass Recycling Market study is deliberately practical. It is designed to be used by corporate strategy teams, investors conducting due diligence, operations leaders sizing facilities, and procurement teams negotiating long-term offtake. Below are the core deliverables included in the full study:
Glass Recycling Market
- Bottom-up market sizing and forecast models (2020–2032) that link collection, processing throughput, and end-market demand. The model is provided in an editable workbook so clients can test bespoke scenarios.
- Unit economics and plant-level benchmarks — energy, yields, capex/opex ranges, and payback profiles for common processing routes (municipal MRFs, dedicated glass sorting facilities, cullet beneficiation plants).
- Regulatory impact scenarios that overlay near-term (2026) to medium-term (2032) policy changes on demand and pricing. This includes stress-tests for rising recycled-content mandates and extended producer responsibility (EPR) frameworks.
- Supply-chain playbooks — design options for collection, inbound logistics, and quality control to raise acceptable cullet yields from mixed-stream systems.
- Commercial and go-to-market templates — offtake contracting strategies, indexation recommendations, and quality specifications to reduce basis risk between recyclers and glassmakers.
- Competitive database and M&A playbook — high-level dossiers on strategic participants, capability maps, and an acquisition screening tool calibrated to valuation multiples observed in the sector.
- Risk heatmaps and mitigation plans — covering feedstock availability, contamination, energy price shocks, and litigation/regulatory shifts.
Competitive landscape — who matters and why
The market is shaped by a mix of global miners/processors, glassmakers with closed-loop ambitions, and regional specialist processors. Strategic moves over 2024–2025 illustrate industry intent: capacity investments by independent recyclers, partnerships between glassmakers and recyclers to secure high-quality cullet, and consolidation among larger material suppliers seeking scale and geographic reach.
- Sibelco — a global materials supplier with an established recycling network and many facilities across North America. Their strategic posture is scale plus vertical integration; in late 2025 they completed an acquisition that expands their North American glass recycling footprint and strengthens procurement links into container and fiberglass supply chains.
- Owens-Illinois (O-I) — the container glass giant has operational programmes to increase recycled feedstock utilization and runs corporate recycling initiatives that both reduce scope and create PR/ESG value. Such programmes illustrate how manufacturers can combine procurement discipline with consumer-facing collection efforts.
- Vetropack and Ardagh Group — regional container manufacturers that are leaning into partnerships and localised cullet supply models to insure feedstock quality and reduce transportation intensity.
- Specialist processors (Momentum Recycling, Strategic Materials, and equivalents) — these players supply high-quality cullet and often operate closer to municipal collection systems. Their agility makes them attractive partners or targets for larger manufacturers seeking feedstock security.
- Notable greenfield and expansion signals: recent facility openings and partnerships demonstrate that growth capital is available for projects that meaningfully improve yield and quality — a key signal for investors and corporates assessing timing for brownfield upgrades vs. new builds.
Policy and infrastructure: near-term constraints and long-term tailwinds
Regulation is the accelerant. The recent Packaging and Packaging Waste Regulation sets demanding recycling targets, and several subnational jurisdictions (notably some U.S. states) are already legislating higher recycled content or incentives for recycled-material use. At the same time, structural infrastructure challenges — such as the limited acceptance of glass at many material recovery facilities when commingled — create near-term bottlenecks. These two forces together mean the market’s growth is both policy-driven and engineering-limited: solving the operational constraints unlocks a rapid value uplift.
In practical terms, this creates three actionable priorities for 2026:
- Accelerate pilots that address contamination and separation losses at the collection stage; the delta between collected glass and processed cullet is where immediate margin is created.
- Invest in higher-quality downstream processing where furnace-ready cullet commands premium pricing and reduces energy costs in smelting operations.
- Engage proactively with policymakers and industry coalitions to influence standards for recycled-content verification and logistics incentives — shaping regulation is as valuable as adapting to it.
How to use our study in 2026 planning cycles
Leaders who will make consequential choices in 2026 should view our report as an implementation toolkit rather than a passive desk reference. Use the study to:
- Run multi-scenario investment appraisals that combine plant-level unit economics with policy-triggered demand scenarios.
- Screen acquisition targets using our valuation framework and integration checklist, prioritising targets that close collection-to-process gaps and add furnace-ready cullet capacity.
- Design procurement contracts with built-in quality indices and pass-through mechanisms that align recycler and glassmaker incentives.
- Benchmark operations against a global dataset to identify 6–18 month improvements that materially lower processing costs and raise saleable yield.
- Build stakeholder narratives for investors and regulators that quantify carbon, cost, and circularity benefits from recycled glass adoption.
Final note: what you’ll find behind the paywall
This briefing demonstrates the depth and practical orientation of PW Consulting’s Glass Recycling Market study while adhering to our “trailer” principle: we intentionally withhold the report’s detailed regional, product and application-level splits and the granular financial tables. Those segmented datasets, the editable forecasting workbook, deal comparables, and the facility-level benchmarking dataset are available in the full report and are the elements that deliver execution-ready value to strategy, operations, and M&A teams in 2026.
If your organisation is contemplating capital allocation, partnership selection, or procurement strategies in glass recycling this year, the full study will convert high-level signals into executable roadmaps. Contact PW Consulting to obtain the complete dataset, scenario workbooks, and bespoke advisory support to accelerate your 2026 strategy.
For detailed analysis of this topic, please visit the official page: Glass Recycling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


