



Diethanol Isopropanolamine (DEIPA) Market Set to Expand at 6.98% CAGR — PW Consulting

Diethanol Isopropanolamine (DEIPA) Market — 2026 Strategic Preview
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, this briefing is designed to equip senior executives, corporate strategists, and investment committees with the high‑level, decision‑focused intelligence they need entering 2026. Drawing on our 2025 base‑year analysis and our proprietary forecast through 2032, this preview highlights the structural forces, competitive dynamics, and tactical implications that will determine who captures value in the DEIPA market over the next investment cycle. The full study contains the granular segmentation, regional allocations, and vendor scorecards that underpin the conclusions offered here; those detailed datasets are intentionally gated to preserve commercial sensitivity and to direct stakeholders to the full report for transaction‑grade inputs.
Diethanol Isopropanolamine (DEIPA) Market
Snapshot: Market Trajectory and Structural Signal
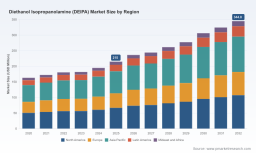
Our consolidated market sizing shows steady expansion over the 2020–2032 horizon. The DEIPA market grew from USD 163.15 Million (USD, Million unit) in 2020 to USD 215.0 Million in the 2025 base year, and our scenario‑validated forecast projects growth to approximately USD 344.8 Million by 2032. The compound annual growth rate (CAGR) implied across the forecast window is 6.98% — a pace that makes DEIPA a mid‑growth specialty chemical segment, attractive to both incumbent producers and adjacent chemical players seeking exposure to construction and performance‑chemicals demand chains.
Diethanol Isopropanolamine (DEIPA) Market
Why This Research Matters for 2026 Decisions
- Capital allocation and capacity planning: The mid‑single‑digit CAGR and predictable end‑market end‑use patterns warrant staged capacity investments and optioning rather than large upfront greenfield builds. Our analysis identifies where flexible, modular expansion will outperform single‑stage scale.
- M&A and partnership screening: A relatively low market concentration (CR3 ≈ 24.6, CR5 ≈ 26.2) signals a fragmented supply base — fertile ground for bolt‑on consolidation and route‑to‑market acquisitions, particularly for firms seeking to pair product portfolios with regional logistics footprints.
- Procurement and price risk management: Raw material volatility and tightening compliance costs mean purchasing strategies (fixed vs floating contracts, indexation, strategic stockpiles) materially affect margin. The report lays out hedging thresholds tied to feedstock price bands and utilization levels.
- Regulatory and sustainability roadmaps: Environmental compliance is a top‑line risk for manufacturers. Operators that invest early in emissions control and VOC mitigation technologies reduce both regulatory risk and future capex dislocation.
Key Market Dynamics Shaping 2026 Strategy
- Demand composition and end‑use resilience: DEIPA remains anchored in construction‑adjacent applications (cement grinding aids, concrete admixtures) while an increasing share of demand is linked to high‑value specialty applications. This demand mix produces a resilient base with episodic acceleration tied to infrastructure cycles and select industrial manufacturing ramps.
- Input cost volatility: The prices of core feedstocks for DEIPA — including isopropanolamine and diethanolamine — have shown periodic volatility linked to upstream energy markets and regional supply disruptions. Firms without disciplined input cost strategies experienced margin compression in 2024–2025; those with active procurement programs maintained spread.
- Regulatory tightening and compliance burden: Our industry outreach indicates increasing pressure in mature markets: over half of manufacturers report environmental compliance issues, with significant shares citing VOC restrictions and difficulty meeting emissions standards. These factors raise the effective cost of production, extend permitting cycles, and in some cases create practical barriers to new capacity.
- Fragmented supply base and specialization: The market structure favors small‑to‑mid sized regional producers and specialist formulators. Low concentration ratios mean national/regional champions can command premium routing advantages in logistics and customer service but lack the scale pricing power of large commodity players.
Competitive Landscape — Strategic Positions and Implications
Our competitive review concentrates on producers and distributors that shape customer choice, technology diffusion, and channel control. Below are strategic syntheses of the core players we evaluated (profiles in the full report include product grades, asset footprints, certifications, and supply‑agreement history):
Diethanol Isopropanolamine (DEIPA) Market
- Nanjing Hongbaoli Group Co., Ltd. (Nanjing, China): A vertically integrated manufacturer with a focused isopropanolamines series. Strengths include localized supply continuity for Chinese construction markets and integration into regional cement additive value chains. Strategic implication: attractive partner for off‑take agreements in Greater China but vulnerable to environmental capex requirements.
- Viswaat Chemicals Limited (India): Positioned as a cost‑competitive producer serving domestic and export construction chemical demand. Strengths include nimble production and existing trade relationships in South Asia; opportunity exists to move up the value chain through performance‑grade product development.
- Amines & Plasticizers Limited (Mumbai, India): One of the larger DEIPA producers in India with established supply to cement grinding aid markets. Strategic implication: potential consolidation target or strategic partner for players seeking scale in South and Southeast Asian markets.
- Bisley International LLC (Houston, USA): A prominent distributor with channel reach into North American industrial and construction segments. Value proposition centers on inventory service, technical support, and regulatory advisement — critical assets where upstream producers lack direct sales presence.
- Hebei InnoNew Material Technology Co., Ltd. and Shandong Inniolamine New Material (China): Both firms emphasize high‑purity DEIPA grades for performance‑critical applications. Their capabilities are strategically important for OEM customers and formulators requiring consistency and traceability.
Collectively, these participants demonstrate a market comprised of national champions, specialty producers, and channel specialists. The balance of bargaining power is situational — procurement teams with diversified supplier lists can command service and price concessions, whereas specialty end‑users depend on a small set of qualified suppliers for consistent quality.
Report Contents — Practical Deliverables
The full PW Consulting DEIPA study includes operationally actionable modules designed for 2026 decision cycles. Key deliverables include:
- Top‑down and bottom‑up market sizing (2020–2032) with scenario overlays and sensitivity bands tied to macroeconomic and construction indices.
- Demand drivers and elasticities by end‑use class, with prioritized use‑case maps for go‑to‑market planning (note: segment‑level tables and regional allocations are proprietary and available in the full report).
- Supply‑side cost models, including feedstock pass‑through mechanics, plant economics at different utilization levels, and margin levers by product grade.
- Regulatory risk matrix with jurisdictional hot spots, compliance capex estimates, and recommended mitigation levers for producers and downstream buyers.
- Vendor benchmarking and procurement due‑diligence checklists — tradeoffs between price, quality, lead time, and compliance.
- Playbooks for M&A screening, JV structuring, and off‑take negotiation templates calibrated to the market’s fragmentation profile.
How to Use This Intelligence in 2026
- For CEOs and corporate development: Use the market concentration and growth assumptions to prioritize inorganic growth in targeted regions or product grades. Pursue smaller, complementary assets that add technical capability and customer access rather than costly multinational platforms.
- For COO and supply chain leads: Implement dynamic purchasing frameworks tied to feedstock indices. Prioritize supplier redundancy in jurisdictions subject to regulatory tightening and build contingency warehousing for critical customers during permit or logistics disruptions.
- For R&D and product management: Invest in formulations and low‑VOC production methods that preempt likely regulation shifts in mature markets and that create differentiation for high‑value end uses.
- For investors and PE teams: Target bolt‑on acquisitions where operational improvement (procurement, quality systems, emissions control) can quickly unlock multiple expansion levers across a fragmented supplier base.
Risk and Scenario Considerations
- Upside scenario: Faster infrastructure spending and nearshoring of construction materials accelerate demand; producers with flexible capacity capture incremental margins.
- Downside scenario: Persistent feedstock price volatility and regulatory closures in mature markets depress capacity utilization and push marginal players to exit, creating short‑term supply squeezes.
- Mitigation levers: Contractual hedging, regulatory certification roadmaps, and strategic inventory layering are pragmatic defenses we recommend for 2026 operational planning.
Conclusion — The Strategic Imperative for 2026
DEIPA is a mid‑growth, structurally important specialty chemical with a clear nexus to construction and select industrial applications. The modestly aggressive CAGR and the fragmented competitive landscape create an environment where disciplined operators can outpace peers through focused product development, regulatory foresight, and targeted consolidation. In 2026, companies that align capital allocation to modular capacity, strengthen procurement governance, and proactively address environmental compliance will capture the outsized margins created by supply disruptions and premiumized product demand.
For transaction‑grade details — full segment breakdowns, regional tables, vendor scorecards, and the proprietary supply‑chain maps that support the recommendations above — please consult the full PW Consulting DEIPA Market report. The report contains the underlying datasets and executable tools necessary to convert these strategic insights into concrete 2026 actions.
For detailed analysis of this topic, please visit the official page: Diethanol Isopropanolamine (DEIPA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


