



PW Consulting: Captioning & Subtitling Market to Hit USD 6,150M in 2025

Captioning and Subtitling Solutions Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
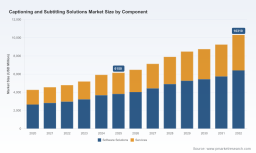
As organizations embed video into every customer, employee and compliance touchpoint, captioning and subtitling moved beyond an accessibility checkbox to become a mission-critical layer of content infrastructure. PW Consulting’s latest market study—anchored on a 2025 base year and projecting through 2032—maps how this transformation is translating into measurable market growth and new buying imperatives. The global market expands from a multi-billion USD base in 2020 to an estimated USD 6,150 Million in 2025, and is forecast to continue on a steady compound annual growth trajectory (CAGR 7.84%) through 2032, when our model projects a market above USD 10 billion (Million USD units throughout).
Captioning and Subtitling Solutions Market
Why this research matters for 2026 strategic planning
- Timing of investment decisions: 2026 is the first full planning cycle after recent regulatory shifts and a visible acceleration of AI-driven live-capabilities. Boards and CIOs who commit to a clear captioning and subtitling strategy this year capture outsized operational and compliance value over the next six years.
- Vendor selection risk-reward: The market shows healthy growth but also distinct specialization: pure-play captioning services, AI-first platforms, and enterprise software suites are coexisting and competing. Choosing the wrong partner risks integration drag, audit exposure, or overspend on bespoke services.
- Operational leverage: Organizations that standardize on cloud-first, auditable captioning pipelines and embed human-in-the-loop QA where it matters will reduce long-run costs while improving accessibility and searchability of video assets.
Macro dynamics shaping the market
Three structural forces are driving the market dynamics that buyers must incorporate into 2026 budgets and vendor roadmaps:
Captioning and Subtitling Solutions Market
- Regulation and standards: Recent regulatory activity—most notably new closed-captioning accessibility rules affecting hardware manufacturers and multichannel programmers—has raised the compliance bar. The regulatory environment now emphasizes developer-accessible display settings and broader obligations for IP-delivered programming. Simultaneously, security and quality certifications (e.g., ISO frameworks) are being positioned as de facto prerequisites for enterprise procurement, particularly for sensitive education, government, and corporate content.
- Real-time AI + human hybrid models: Advances in speech recognition and neural machine translation have made real‑time captioning commercially viable at scale. However, accuracy expectations in broadcast, legal, and academic settings still demand human post-editing or supervised workflows. The winners will be those who operationalize hybrid models that balance latency, accuracy and cost.
- Platformization and verticalization: Buyers are asking for captioning to be embedded within broader media workflows—encoding, OTT publishing, LMS integration, and archival search—rather than treated as a bolt-on. At the same time, vertical-specific feature sets (e.g., verbatim legal transcription, curriculum-aligned subtitle mapping for education, or multi-language dubbing for entertainment) are differentiators in procurement decisions.
Competitive landscape — who matters and why
The competitive field combines specialized captioning houses, AI-driven transcription platforms, and major software/technology vendors. The market’s structure rewards both deep domain expertise and scale of platform reach. Key strategic observations from our vendor analysis:
Captioning and Subtitling Solutions Market
- Specialist live-caption providers (e.g., VITAC, Verbit, Ai‑Media): These firms lead on live and broadcast workflows, low-latency streaming integrations, and service models that mix AI with professional editing. Their strength lies in operational maturity for large-scale events and regulatory compliance for broadcasters.
- AI-native platforms (e.g., Otter.ai, Trint, Amberscript): These vendors excel at developer-friendly APIs, rapid transcription for enterprise use-cases, and scalable cloud deployments. Some emphasize data governance and certification as a procurement differentiator; others trade higher automation for lower per-minute costs.
- Broad media and tech incumbents (e.g., Adobe, Microsoft, IBM): Their advantage is ecosystem integration—captioning as a feature inside creative suites, communication platforms, or cloud AI services. They appeal to customers seeking single-vendor simplicity and deep analytics integration across content pipelines.
- Localization and post-production specialists (e.g., TransPerfect, ZOO Digital, 3Play Media): These players target subtitling, translation and international distribution workflows where linguistic accuracy and quality control are paramount.
- Niche innovators (e.g., SyncWords, AppTek): Focused on specific technical gaps—real-time multi-language live subtitles, voice dubbing, or advanced speech models—these vendors often become tactical partners for broadcasters or event platforms.
Our competitive chapter evaluates each vendor against operational criteria (real-time latency, accuracy/QA model, platform integrations, compliance posture, data governance, pricing transparency, and go-to-market motion). It also maps partnership opportunities—where incumbent broadcasters and OTT platforms can thin-slice vendor capabilities through alliances rather than acquisitions.
Regulatory and standards implications
Regulation is no longer a background risk; it is a leading driver of procurement. Recent rules requiring accessible caption display settings and the expansion of closed-captioning obligations to IP-delivered programming are changing technical spec sheets and RFP checklists. For government and education buyers, the demand for auditable workflows, retention policies and certification-compliant vendors is already influencing vendor shortlists. PW Consulting’s report includes a compliance impact matrix that translates regulatory requirements into technical acceptance criteria and procurement clauses.
Practically useful deliverables inside the full report
This market brief is a trailer. The full PW Consulting study is designed as a hands-on playbook for practitioners and includes:
- Market sizing and a seven-year forecast model (2026–2032) with scenario analyses to stress-test demand drivers under alternative regulatory and technology adoption curves.
- Vendor benchmark framework with scored profiles across technical capabilities, vertical strengths, security posture and commercial terms.
- Procurement toolkit: RFP templates, proof-of-concept (PoC) scripts for live and post workflows, SOW language to protect data privacy and SLAs, and comparative TCO models.
- Implementation blueprints: Integration patterns for common stacks (media asset management, LMS, OTT/CDN), latency optimization playbooks for live events, and QA workflows for hybrid AI/human models.
- M&A and partnership playbook: Valuation multipliers we observe in recent transactions, integration risk checklists, and recommended carve-outs for IP and model licensing.
- Case studies and vendor negotiation guidance that distill lessons from broadcast, education, enterprise and government deployments.
Actionable recommendations for 2026
- Adopt a modular architecture: Treat captioning/subtitling as a callable service (API-first) rather than a standalone vendor tie. This reduces lock-in and makes it easier to apply specialized services where necessary.
- Build hybrid workflows: Standardize on AI-driven first-pass captions, augment with human review only for high-risk content, and instrument quality gates to optimize cost vs. accuracy.
- Prioritize certified providers: For enterprise, education and government use-cases, procurement should require auditable security certifications and contractual commitments on data residency and retention.
- Negotiate outcome-based SLAs: Move beyond uptime clauses to include accuracy bands, latency maximums for live events, and remediation processes to reduce operational disputes.
- Plan for consolidation: Expect an active M&A environment as platform players seek to bolt on live captioning capabilities or as specialists seek scale; prepare data/integration due diligence templates now.
What we intentionally withhold in this preview
Consistent with PW Consulting’s “trailer” approach, this article shares directional insights and the strategic implications of the market’s growth trajectory. We have intentionally not published detailed segment-level tables, regional/application percentage splits, contract-level pricing benchmarks or vendor scorecards here. These proprietary datasets and granular segmentation outputs are available in the full report and underlying models—designed to support procurement negotiations, CapEx approval decks and M&A diligence.
Final note — how to use this intelligence
For senior executives and functional leaders preparing 2026 budgets, the core conclusion is straightforward: captioning and subtitling are transitioning from a compliance/afterthought cost center into a platform-level capability that can unlock reach, discoverability and legal risk mitigation. The market’s projected expansion through 2032 creates both urgency and opportunity—buyers who act with a clear architecture, risk-managed vendor mix and outcome-oriented contracts will realize measurable ROI. PW Consulting’s full study provides the models, vendor intelligence and playbooks to execute that agenda with confidence.
To access the complete segmentation tables, vendor benchmarking, scenario models and procurement toolkits, consult the full PW Consulting report and dataset on the Captioning and Subtitling Solutions Market page.
For detailed analysis of this topic, please visit the official page: Captioning and Subtitling Solutions Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


