



PW Consulting: Petroleum Needle Coke Market Poised for 6.7% CAGR Through 2032

Petroleum Needle Coke Market — Strategic Outlook for 2026 Decision-Making
Executive trailer
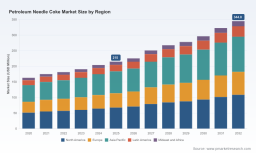
Petroleum needle coke (PNC) sits at the intersection of traditional refining economics and the fast-evolving carbon-materials chains that underpin modern electrification and steelmaking. Our newly completed PW Consulting study, using 2025 as the base year, tracks the market’s journey from historical dynamics (2020–2025) into a rigorous forecast window (2026–2032). The headline: the global market expanded from roughly USD 163.2 million in 2020 to USD 215.0 million in 2025, and is projected to grow at a 6.7% CAGR across 2026–2032, reaching an estimated USD 344.8 million by 2032. For corporate leaders planning investments, offtakes, or restructuring in 2026, this trajectory is both an opportunity and a call for disciplined strategy.
Petroleum Needle Coke Market
Why this study matters in 2026
-
Timing of demand inflection — The convergence of graphite-electrode replacement cycles and accelerating battery-anode capacity expansions creates a near-term window where securing high-quality PNC supply materially affects project economics for both incumbents and new entrants.
Petroleum Needle Coke Market -
Supply-side consolidation and concentration — The market shows meaningful concentration among a small number of integrated producers, shaping pricing power, contract structures, and capacity availability. Our work quantifies concentration and models realistic sourcing scenarios for 2026 procurement.
Petroleum Needle Coke Market -
Regulatory and feedstock uncertainty — Volatile crude and coal-tar derivative markets, combined with tightening environmental rules in several jurisdictions, add execution risk that must be stress-tested in every capital decision made in 2026.
Market trajectory — evidence you can act on
PW Consulting’s base-year analysis documents a steady post-pandemic recovery through 2025, with market value rising from USD 163.15 million in 2020 to USD 215.0 million in 2025. Our scenario-driven forecast then projects the market to continue expanding to USD 225.48 million in 2026, with intermediate milestones at approximately USD 296.4 million by 2030 and USD 344.8 million by 2032 under the central-case assumptions. A 6.7% compound annual growth rate across the forecast period encapsulates technical substitution, capacity additions, and policy-driven share shifts between feedstock routes.
Demand drivers and application dynamics
-
Graphite electrodes remain the backbone of near-term demand, driven by steel industry cycles and capacity rationalization in certain regions. The timing of restocking and electrode replacement schedules creates demand spikes that are highly lumpy and geographically concentrated.
-
Battery anode markets represent the structural growth vector. While battery-grade demand is still a smaller share today, its growth rate outpaces traditional applications and requires higher specification feedstocks and consistent quality over long horizons.
Supply fundamentals and feedstock volatility
PNC supply is fundamentally linked to aromatic-rich refinery residues, predominantly FCC decant oil and other heavy aromatic streams. Price swings in crude, coal tar, and slurry oils propagate quickly into producers’ cost bases; our sensitivity modules quantify how a 10–20% shift in feedstock cost affects cash margins across different plant configurations. Additionally, capacity additions tend to follow investment cycles in delayed-coking and calcination assets — capital-intensive projects that carry long lead times and operating complexity.
Regulation, sustainability, and the low-carbon premium
-
Regulatory tightening in major producing regions has already manifested in material capacity attrition. Notably, environmental enforcement in China led to substantive closures and output restrictions across graphite electrode facilities, creating short-term supply tightness and regional price divergence.
-
At the same time, evolving carbon accounting frameworks in the EU and customer procurement policies in downstream battery and specialty carbon markets are beginning to favor lower life-cycle-emission PNC routes (e.g., petroleum-based vs. coal-based). This creates a bifurcation: product quality remains important, but carbon-intensity profiles are rapidly becoming a second-order commercial requirement.
-
Our report includes an LCA-comparison framework and an EU-alignment heatmap to help buyers and producers quantify the commercial value of low-carbon certification in 2026 contracting rounds.
Competitive landscape — who matters and why
The market is dominated by a handful of integrated and regionally-specialized players whose strategic moves materially shift supply balances. PW Consulting’s competitive chapter profiles leading producers and assesses their strategic postures, investment trajectories, and downstream relationships.
-
Phillips 66 Company (Houston, TX) — An integrated refiner with delayed-coking operations and electrode-grade supply capability. Recent strategic moves include a substantial capacity expansion investment in Louisiana announced in February 2025, aimed at capturing growth from battery-anode demand. They have also concluded long-term supply agreements with anode manufacturers, indicating a vertical-supply strategy that secures demand for expanded output.
-
GrafTech International Ltd. (Brooklyn Heights, OH) — A vertically integrated electrode and specialty-carbon supplier operating petroleum needle coke capacity. GrafTech’s 2025 launch of a lower-carbon “Eco Graphite” product signals the industry’s pivot toward differentiated, sustainability-linked offerings and reflects an R&D and feedstock-diversification approach that de-risks regulatory exposure.
-
ENEOS Corporation (Tokyo) , Seadrift Coke L.P. (Seadrift, TX) , Petrocokes Japan Ltd. (Tokyo) , C-Chem Co., Ltd. (Japan) , and Chinese Petroleum & Chemical Development Company (Taiwan) — These producers combine regional refinery integration with calcination capability or specialized pitch-processing. Their strategic relevance varies by product grade focus (electrode vs. battery) and regional access to feedstocks.
Recent strategic moves—what they reveal
-
Feb 2025: Phillips 66 announced a multi-hundred-million-dollar expansion to increase PNC capacity in Louisiana by approximately 40% — a move explicitly tied to EV battery supply chains.
-
Apr 2025: GrafTech introduced a product produced from a significant recycled-feedstock component, pre-positioning itself for low-CO2 steelmaking contracts and demonstrating how product differentiation can create pricing and offtake advantages.
-
Sep 2025: Phillips 66 signed a long-term supply agreement to support a 30,000 tpa graphite-anode plant in the U.S. — an example of buyers and suppliers seeking to lock-in bilateral arrangements to de-risk critical upstream supply for battery projects.
Strategic implications for 2026 — prioritized actions
-
Secure supply through diversified contracting: For battery-anode projects planned or under construction in 2026, obtain multi-year offtake arrangements with staggered volume and quality clauses. Use price collars and pass-through mechanisms tied to transparent feedstock indices to protect margins.
-
De-risk feedstock exposure: Buyers and producers should model blended-feed scenarios (FCC decant oil, heavy cycle oils, and recycled aromatics) to quantify quality tradeoffs and margin impacts under commodity stress.
-
Invest in qualification pathways: Battery-grade PNC requires rigorous qualification. Allocate resources in 2026 to accelerate lab-to-pilot qualification programs and secure early supply slots with suppliers that have calcination and carbonization capabilities.
-
Pursue low-carbon differentiation: Producers should evaluate retrofits or feedstock blends that reduce cradle-to-gate emissions and develop verifiable LCA dossiers — these can command a commercial premium in tenders and reduce regulatory friction.
-
Prepare scenario-based capital plans: Given the market’s 6.7% CAGR central case and the lumpy nature of demand spikes, treat new greenfield capacity as contingent on confirmed offtake and include modular/capex-light designs where possible.
-
Consider strategic M&A and partnerships: With market concentration favoring a small number of players, targeted acquisitions of feedstock-processing assets or joint ventures with electrode and anode makers can secure margins and reduce exposure to spot volatility.
What PW Consulting’s full report delivers (practical, executable content)
-
Detailed historical and forecast market-sizing (2020–2032) with scenario runs (base, downside, upside) and sensitivity to feedstock and regulatory shocks.
-
Proprietary supply-demand balance models with plant-level capacity, lead times, and utilization assumptions mapped to likely contractual outcomes.
-
Price and margin stress tests linking crude/coal tar/slurry oil dynamics to producer cashflows under different contractual structures.
-
Operator scorecards and supplier capability matrices to support procurement shortlists, including qualification timelines for battery-grade supply.
-
Regulatory risk matrices (China, EU, North America) and a carbon-footprint playbook to help buyers and sellers align capex and procurement strategy with emerging standards.
-
Commercial templates: term-sheet clauses, sample offtake agreements, and negotiation playbooks tailored for 2026 contracting.
How decision-makers should use this study in 2026
Executives should treat the report as both an intelligence brief and a transactional tool. Use the market-sizing and scenario modules to validate internal assumptions; use supplier scorecards to compress qualification timelines; and use the commercial templates to move from intent to executed contracts before mid-2026 when capacity commitments and supply reallocations will crystallize. For investors and M&A teams, our valuation appendices and comparable-transactions analysis provide the levers to translate operational risk into purchase-price adjustments.
Final note — the trailer promise
This article has outlined the strategic contours and actionable directions embedded in PW Consulting’s Petroleum Needle Coke Market study. We have demonstrated the macro trajectory, the major strategic levers, and the competitive moves shaping supply and demand. To preserve the value of our proprietary segment-level models, regional splits, and granular supplier data — the precise inputs that drive deal-level outcomes — those detailed tables, interactive dashboards, and model instances are available exclusively in the full report and via our client portal. For procurement teams, investors, and corporate strategists preparing decisions in 2026, accessing the full dataset and scenario workbooks is the critical next step.
Contact PW Consulting to request the full Petroleum Needle Coke Market report, access the interactive forecast model, or commission a tailored deep-dive aligned to your project timelines and risk appetite.
For detailed analysis of this topic, please visit the official page: Petroleum Needle Coke Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


