



PW Consulting: White Fused Alumina — 2025 market USD 200M; CAGR 4.01% (2026–32)

White Fused Alumina Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive teaser
As manufacturers and downstream users reposition for a manufacturing rebound and an inflection in raw materials dynamics, white fused alumina (WFA) is re-emerging as a strategic commodity. PW Consulting’s White Fused Alumina Market study — built on a 2020–2025 historical base and a 2026–2032 forecast horizon — quantifies this re-emergence and translates it into actionable decision frameworks for 2026. The global WFA market, measured in USD Million, expanded from approximately USD 150.0 Million in 2020 to USD 200.0 Million in 2025 and is projected to continue growing at a compound annual growth rate (CAGR) of about 4.01% across our 2026–2032 forecast window, reaching roughly USD 263.3 Million by 2032.
White Fused Alumina Market
Why this matters in 2026
-
Annualized momentum: After multi-year recovery dynamics, 2026 represents a decision point — companies must translate medium-term demand certainty into supply-side commitments (contracts, capacity adjustments, and inventory strategies) that will lock in margins across a modest but steady growth trajectory.
White Fused Alumina Market -
Margin polarization across product grades: Purity-driven, specialty WFA (e.g., ultra-high Al2O3 for precision ceramics and technical polishing) differs materially in value proposition from cost-optimized grades targeted at mass abrasives and refractory linings. Strategic portfolio choices made in 2026 will determine whether firms capture premium segments or defend lower-margin volume.
White Fused Alumina Market -
Concentration & competitive dynamics: The market shows moderate concentration — the top three suppliers account for the low-to-mid thirty percent range, and the top five approach roughly half of global supply. This mix creates opportunities for both scale-driven competitors and niche specialists to shape regional and application-specific pricing and supply strategies.
What PW Consulting’s study delivers — practical, board-ready outputs
Our report is designed as an operational playbook for executives, procurement leaders, and corporate development teams. Highlights include:
-
Market sizing and validated forecasts: Annual market values from 2020 through 2032, with scenario-based outlooks that stress-test demand shocks and feedstock volatility. (Base year: 2025)
-
Supply-side architecture: Detailed mapping of production routes (electric-arc fusion of Bayer alumina, feedstock sensitivity, and furnacing profiles), plant-level capabilities, and capacity utilization frameworks to assess incremental expansion needs and timing.
-
Demand driver intelligence: A granular synthesis of end-market trends — refractories, abrasives, and ceramics — translated into purchase-behavior signals and procurement lead-time expectations.
-
Commercial frameworks: Go-to-market playbooks, price-elasticity models, contract templates (indexation recommendations, minimum take or pay guardrails), and negotiation levers to protect margin while securing volume through 2028.
-
Risk and resilience tools: Supply disruption matrices, geopolitical and trade-scenario stress tests, and hedging options for raw-material inputs and energy — with bespoke mitigation plans for critical nodes in the WFA value chain.
-
Transaction intelligence: A curated short-list of acquisition and partnership targets, valuation benchmarks, and synergy estimates to support inorganic growth or vertical integration plays.
-
Executive dashboards and KPIs: A ready-to-deploy set of metrics (e.g., realized ASP by grade band, purity-adjusted margins, furnace utilization, and time-to-fill) for weekly and monthly monitoring.
Competitive landscape — who matters and why
The WFA market features a mix of global branded manufacturers, national champions, and high-volume, cost-focused producers. Our analysis synthesizes capabilities across quality, scale, geographic reach, and customer intimacy.
-
Washington Mills (North Grafton, Massachusetts): A technology- and quality-led player noted for producing very high-purity WFA (>99% Al2O3). Their focus on engineered grains, powders, and bubbles via electric-arc fusion positions them to capture premium applications in advanced refractories and precision abrasives. For firms targeting performance differentiation, Washington Mills represents both a benchmark and a potential partner for co-development.
-
Imerys (Paris, France): Operating multiple production sites and offering branded fused alumina products under established portfolios, Imerys combines scale with global distribution. Their multi-site footprint supports customer continuity and shorter lead times in key industrial regions; they are a go-to supplier for customers seeking a balance of quality and geographic risk mitigation.
-
Rusal (Moscow, Russia): Vertical integration through alumina production and electric-arc fusion gives Rusal strategic control over feedstock and cost base. However, geopolitical and trade considerations create both risk and opportunity: buyers must weigh short‑term supply economics against long-term diversification and compliance strategies.
-
U.S. Electrofused Minerals (USEM) (Aliquippa, Pennsylvania): As a supplier in fused oxides, USEM competes on industrial-grade offerings and dependable supply to North American markets. Their value is strongest where localized, reliable logistics and technical support matter.
-
MOTIM Electrocorundum (Hungary): A specialist focused on high-quality corundum for refractories and abrasives. European and regional manufacturers targeting higher-purity product mixes will find MOTIM a credible technical partner.
-
Zhengzhou Yufa Group and Henan Ruishi Renewable Resources Group (China): Large-scale Chinese producers emphasize cost-efficient supply and high throughput. Their strategic advantage is price competitiveness and volume flexibility — a decisive factor for commoditized abrasive and refractory applications. Western buyers should consider a two-track sourcing approach that balances cost capture with supplier diversification and quality assurance.
Strategic implications and recommended 2026 actions
Based on the market trajectory and supplier dynamics documented in our study, PW Consulting recommends a set of prioritized actions for corporations planning for 2026 execution:
-
Segmentation-driven portfolio rationalization: Conduct a rapid review of product margins by grade and end-use. If your portfolio mixes across purity and volume-driven products, create clear routing rules for customers (premium SKUs via premium suppliers; commoditized volumes via cost-efficient partners).
-
Contract design & procurement cadence: Move from annual spot buying to hybrid contracts that combine a baseline of fixed-volume agreements with a smaller variable tranche indexed to observable raw-material or energy indices. This reduces exposure to furnace outages and energy-cost spikes while preserving upside participation.
-
Supply-risk hedging: Establish secondary-supplier relationships in at least two geographies to mitigate local disruption. Where possible, secure capacity commitments with manufacturers that have vertically integrated feedstock or a multi-site production model to reduce single-point-of-failure risk.
-
Premiumization & co-development: For firms targeting growth in technical ceramics and precision abrasives, prioritize co-development agreements with high-purity producers to secure early access to new grades and qualification pipelines.
-
M&A and JV scouting: With moderate market concentration and regional pockets of scale, 2026 remains an advantageous window to pursue bolt-on acquisitions or joint ventures that deliver immediate capacity, access to certified grades, or route-to-market expansion.
-
Sustainability roadmap: Energy intensity and raw-material traceability are emerging procurement requirements for many downstream customers. Begin supplier audits focused on energy sources, emissions per ton of WFA produced, and traceability of alumina feedstock to strengthen ESG credentials and defend price premia.
Data confidence and signal prioritization
Our base-year calibration uses 2025 as the reference point, with a five-year historical window (2020–2025) and scenario-driven forecasts through 2032. We apply triangulation across plant-level capacity, national trade flows, and downstream consumption models to arrive at our market totals and the 4.01% CAGR for 2026–2032. The report includes sensitivity ranges that capture feedstock shocks, energy-price volatility, and demand-side acceleration or deceleration.
What we are intentionally holding back — and why
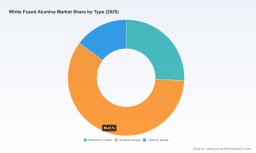
In this preview we purposely omit drill‑down tables and exact split figures across regions, types, and applications. Those core segmentation datasets and customer-level consumption profiles are included in the full PW Consulting report and are essential for transaction diligence, competitive tendering, and procurement tender design. This teaser is intended to demonstrate analytical depth while encouraging stakeholders to access the full intelligence pack for operational implementation.
Next steps — how to use this intelligence in Q1–Q2 2026
-
Procurement leaders: Request the full dataset to run supplier-optimization models and to reprice contracts using our recommended indexation clauses.
-
Corporate development: Use our target shortlist and valuation benchmarks to prioritize M&A conversations and to run rapid synergy screens.
-
Operations and R&D: Engage with identified premium suppliers to scope co-development trials for specialty grades and to secure qualification timelines aligned with product roadmaps.
Final thought
The White Fused Alumina market is neither hyper-booming nor stagnant; it is maturing into a market where quality differentiation, supply resilience, and commercial sophistication will decide winners and losers. Companies that act in 2026 — by aligning procurement structures, securing multi-geography supply, and selectively investing in premium-grade capabilities — will lock in advantaged positions through the remainder of this decade.
For the full report, including regional and application splits, supplier scorecards, and downloadable dashboards, visit the PW Consulting White Fused Alumina Market page to obtain the complete intelligence kit and operational annexes.
For detailed analysis of this topic, please visit the official page: White Fused Alumina Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


