



PW Consulting: SST Market to Reach USD 344.8 Million by 2032 at 6.98% CAGR

Strategic Preview: Solid State Transformers (SST) Market — Why PW Consulting’s 2026 Research Is a Boardroom Imperative
As organizations accelerate electrification, digital infrastructure expansion, and decarbonization initiatives, Solid State Transformers (SSTs) have moved from laboratory curiosity to near-term commercial reality. PW Consulting’s 2026 SST Market study — grounded on a 2025 base year and projecting through 2032 — synthesizes macro forecasts, technology economics, regulatory inflection points, and competitive positioning into an actionable playbook for executive teams, corporate strategy units, and infrastructure investors. The global SST market, measured in USD million, shows a clear upward trajectory: after crossing a notable milestone in our 2025 base year, the market is forecast to grow at a compound annual growth rate (CAGR) of 6.98% across the 2026–2032 horizon, reaching materially higher levels by 2032. This report is purpose-built to support high-stakes 2026 decision cycles — procurement, partnerships, factory investments, and regulatory engagement.
Solid State Transformers (SST) Market
What makes this research strategically valuable for 2026 decisions?
- Timely commercialization inflection: Multiple vendors have signaled product-readiness and early deployments for 2026, shifting SSTs from experimental to investable. That changes the profile of risk for supply chain investments, pilot capital, and utility integration pilots.
- Policy-driven demand windows: Large public programs and changing electrical equipment regulations are creating procurement windows and rate-case rationales that favor early movers. Our research maps these policy timelines to commercial opportunity, enabling advocacy and bid-timing precision.
- Capital allocation clarity: With quantified market growth and scenario-based TAM/SAM analyses, the study helps CFOs and corporate development teams size near-term investment needs and evaluate M&A targets with informed upside assumptions.
- Deployment playbooks: The report does more than forecast; it prescribes vendor selection criteria, validation protocols, and operational integration steps to de-risk first-of-a-kind commercial rollouts.
Market trajectory — headline numbers you can act on
PW Consulting’s base-year snapshot (2025) establishes the commercial market for SSTs and provides a reference for capital planning. From that base, our forecast models project consistent expansion driven by multi-sector demand and regulatory tailwinds. The market is projected to grow at a 6.98% CAGR through 2032, reflecting steady adoption across renewables, EV fast-charging, data center electrification, and advanced distribution applications. Near-term growth (2026–2028) is shaped by first-wave commercial deployments and policy-funded grid modernization programs; medium-term expansion (2029–2032) reflects scaling manufacturing, falling component costs, and integration into mainstream utility planning.
Solid State Transformers (SST) Market
Drivers, constraints, and the economics that matter
- Regulatory accelerants: Material public programs and regulatory decisions are actively reducing adoption barriers. Significant federal funding for grid resilience initiatives is creating grant- and incentive-funded pathways for SST pilots and distribution modernization. Likewise, equipment regulations that phase out legacy insulating gases are catalyzing demand for digital, gas-free alternatives.
- System-level value: SSTs offer capabilities beyond voltage conversion — dynamic power flow control, multi-port dispatching, and embedded power electronics that can materially improve asset utilization in microgrids, data centers, and charging hubs. Our valuation frameworks quantify incremental system benefits (capacity deferral, energy optimization, ramping services) and translate them into payback scenarios for utilities and large C&I customers.
- Cost structure friction: Wide-bandgap semiconductors (e.g., silicon carbide) are a double-edged sword — they enable compact, high-performance SST designs but currently account for a substantial share of BOM cost and remain several times more expensive than silicon alternatives. As a result, SST manufacturing costs today are multiple times higher on a per-kVA basis compared with conventional transformers; the report models cost-reduction trajectories based on anticipated SiC adoption curves, volume ramp assumptions, and supply concentration risks.
- Integration and standards gaps: Realizing full system value requires updates to protection schemes, distribution operations, and interconnection standards. We highlight the minimum set of interoperability, telemetry, and protection requirements to include in procurement RFPs to avoid costly retrofits.
Technology and supply chain implications
Transitioning from prototypes to volume SST production has cascading implications across the supply chain. Our report dissects a practical technology roadmap that buyers and manufacturers can use to align product roadmaps with the expected cost curve. Key areas covered include:
Solid State Transformers (SST) Market
- Component concentration risk for wide-bandgap semiconductors and the impact of long lead-times on factory scheduling.
- Design choices that materially affect serviceability and total lifecycle cost — modular power stages, thermal management approaches, and serviceability-by-design options for utility crews.
- Sourcing strategies for critical passive components, packaging, and thermal systems to avoid single-sourcing pitfalls.
- Quality and test regimes necessary for reliability targets in utility and data center environments, plus recommended acceptance testing templates.
Competitive landscape — who to watch (and why)
The SST supplier ecosystem is emerging with a mix of deep incumbents and specialized startups. PW Consulting’s vendor analysis combines product roadmaps, go-to-market strategies, and recent strategic moves to give corporate buyers and investors a concise competitive map.
- DG Matrix (Raleigh, NC) — A provider of multi-port SST platforms designed for AI data centers, microgrids, and electrification use cases. Recent strategic partnerships and Series A funding have accelerated commercialization pathways and validate customer interest in multi-port dispatchable solutions.
- Amperesand (Singapore) — Focused on medium-voltage platforms for critical infrastructure and industrial electrification, with manufacturing capability in the U.S. and targeted commercial deliveries in 2026 to hyperscalers and Fortune-scale customers.
- Eaton Corporation (Dublin, Ireland) — Leveraging acquisitions to internalize medium-voltage SST technology for data centers, energy storage, and EV charging ecosystems; their scale positions them as a mainstream integrator able to combine legacy switchgear and SST capabilities.
- WattEV (Long Beach, CA) — Building modular SSTs aimed at megawatt-class heavy-duty vehicle charging, with production-ready units targeted for imminent deployment and clear targeting of the heavy transport charging market.
Each of these players demonstrates a different go-to-market vector — from specialist platforms for AI/data center clients to incumbents leveraging established distribution channels. Our competitive profiles include vendor scorecards that assess manufacturability, integration readiness, service model, and commercial traction.
What the report contains — practical, operational deliverables
PW Consulting’s SST Market report is intentionally structured to be a working tool for teams contemplating near-term commitments. Highlights include:
- Market sizing and scenario forecasts (2026–2032) with sensitivity cases and unit-volume assumptions tied to policy and technology milestones.
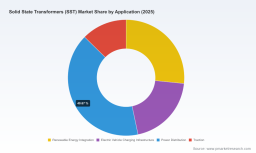
- Segmented demand narratives by application—renewables integration, EV fast-charging, data center electrification, distribution modernization—and a methodology for translating system-level value into procurement criteria (note: detailed segment tables and granular percentages are reserved for the full report to preserve commercial sensitivity).
- Vendor due diligence templates and an RFP checklist that include recommended test specifications, warranty constructs, and service-level expectations.
- CapEx/Opex modeling templates, including multi-year TCO comparisons that explicitly model SiC price trajectories, manufacturing yield assumptions, and secondary benefits like capacity deferral.
- Regulatory and incentive playbook that maps major federal and regional funding programs, standards timelines, and rate-case levers for utility deployment economics.
- Deployment playbooks for pilots and scale rollouts — procurement sequencing, interconnection coordination, and stakeholder engagement scripts for utilities, regulators, and large C&I customers.
How executives should use this intelligence in 2026
- Procurement timing: Use the report’s policy and vendor-readiness timelines to align RFPs with supplier capacity and incentive windows, minimizing carry costs and securing favorable terms.
- M&A and partnerships: Identify strategic acquisition targets or JV partners that fill capability gaps (power electronics, system integration, service ops) and use our valuation framework to size accretive deals.
- Factory and CAPEX planning: Apply the cost-crossover scenarios to decide whether to co-locate assembly near semiconductor suppliers, enter licensing agreements, or adopt a fabless model.
- Regulatory engagement: Target state and federal regulatory processes identified in the report to secure rate-basing approval, grid-interconnection waivers, or incentive qualification for early deployments.
Why this is a “trailer” and how to get the full picture
This article is a strategic preview: it demonstrates the depth of our analysis and highlights near-term decision levers while deliberately withholding granular segment-level tables and the full vendor-scorecard detail that materially inform procurement and investment selection. For teams preparing RFPs, CAPEX proposals, or M&A diligence in 2026, the complete report includes the detailed segmentation, down-to-kVA modeling, supplier cost curves, and downloadable templates necessary to execute with confidence.
Next steps
- For procurement and strategy leads: request the full report to obtain the RFP checklist, TCO model, and vendor scorecards tailored to your application mix.
- For investors and corporate development teams: engage PW Consulting for a targeted diligence package that overlays our forecast on your asset base and risk appetite.
- For utilities and regulators: leverage our policy playbook to craft rate-case narratives and pilot evaluation criteria that capture SST-specific system benefits.
PW Consulting’s 2026 SST Market study translates a nascent technology wave into executable strategy. If your 2026 capital and operational plans touch distribution modernization, fleet electrification, data center resilience, or grid-edge services, this research gives you the language, the scenarios, and the tactical tools to act — precisely when timing and positioning matter most.
For detailed analysis of this topic, please visit the official page: Solid State Transformers (SST) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


