



PW Consulting: Thermoplastic Edgeband Market Set to Grow at 7.2% CAGR Through 2032

Thermoplastic Edgeband Market: Strategic Outlook for 2026 Decision-Making
As PW Consulting’s lead industry analyst, I present a focused strategic primer on the Thermoplastic Edgeband market designed to inform executive decisions in 2026. This introduction synthesizes macro trajectories, competitive moves, supply-side shocks and regulatory currents to highlight where value will be created — and where risk will accumulate — over the 2026–2032 forecast horizon. To preserve the tactical edge of our subscribers, detailed segment breakdowns and raw tables are intentionally withheld from this preview; the full report contains the granular datasets, regional and application splits, and company scorecards that operational teams require.
Thermoplastic Edgeband Market
Market snapshot: scale and growth trajectory
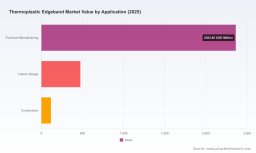
The market for thermoplastic edgebanding has demonstrated resilient expansion through the early 2020s, growing from approximately USD 2,100 Million in 2020 to about USD 2,955 Million in 2025 (base year). Our forecast projects continued expansion at a compound annual growth rate (CAGR) of 7.2% across 2026–2032, lifting total market value to roughly USD 4,817 Million by 2032. Early forecast years reflect steady demand continuity (2026 estimated at ~USD 3,104 Million), with acceleration in the latter half of the decade driven by material substitution, premiumization and digital decor adoption.
Thermoplastic Edgeband Market
Why this report matters for 2026 decisions
- Allocation of CAPEX and capacity timing: With visible capacity additions and plant investments announced across regions, the report helps manufacturing leaders decide where and when to expand, retrofit or idle extrusion lines to avoid overcapacity or missed demand windows.
- Product portfolio prioritization: As finishing technologies (laser edges, zero-joint systems, 3D haptics) move from niche to mainstream, providers must decide which product families (PVC, ABS, PP, PMMA, specialty) to scale or sunset. Our scenario models quantify the ROI of switching production trains under varying raw-material price and regulation cases.
- Sourcing and procurement hedging: Raw-material volatility is a primary margin lever. The report includes stress-tested cost scenarios and supplier concentration maps to guide forward contracts, local sourcing, and vertical integration decisions.
- M&A and partnership targets: With the industry exhibiting moderate consolidation (CR3 ~58%, CR5 ~68%), the study identifies the strategic rationales and valuation brackets for bolt-on acquisitions versus greenfield expansions.
- Compliance and sustainability planning: Anticipated regulatory shifts on PVC usage and end-of-life handling necessitate pre-emptive product and material strategies. We provide a regulatory-readiness checklist and certification roadmaps.
What’s in the full report (practical, actionable modules)
- Executive dashboard: one-page view of market size, growth drivers and downside scenarios calibrated to 2026 planning cycles.
- Demand model: bottom-up demand drivers by end-use and application with sensitivity to housing, furniture cycles and commercial fit-outs.
- Cost and margin simulator: raw-material (PVC, ABS, PP, PMMA) cost curves, freight and tariff overlays enabling margin forecasting at SKU-level.
- Competitive heatmaps and supplier scorecards: manufacturing footprint, product capabilities, channel strength and strategic intents (R&D, capacity moves).
- Go-to-market playbooks: channel strategies for OEM, distributor and direct-sell models, including price-pack architecture for premium vs. commodity tiers.
- Scenario planning compendium: three multi-factor scenarios (Base, Raw-Material Shock, Rapid-Substitution) with recommended tactical playbooks for each.
- Implementation toolkit: procurement clause templates, sample contract hedges, and an eight-week sprint plan for pilot launches of new edgeband SKUs.
Competitive landscape — who to watch and why
The market combines established global extrusion leaders with agile regional players. Key incumbents continue to invest selectively in capacity, digitization and premium finishes, while mid-sized manufacturers pursue volume growth via logistics and localized supply chains.
Thermoplastic Edgeband Market
- SURTECO (Buttenwiesen, Germany): A long-standing leader with deep extrusion experience and a broad portfolio spanning PVC and ABS, SURTECO’s international distribution reach and emphasis on circular/sustainable designs make it a go-to partner for multinational furniture manufacturers seeking consistent multi-region supply and décor matching.
- REHAU (Reinbek, Germany): REHAU’s strengths lie in advanced color-matching and laser-edge technologies. Recent investments expanding high-resolution inkjet printing for 3D-texture haptic edge bands indicate a push to capture higher-margin, design-driven segments where differentiation and shorter lead times matter.
- MKT (Germany): Specialist positioning in premium ABS and PP lines, along with finishes such as mirror gloss and anti-fingerprint, places MKT at the premium end of the market where design fidelity and processing compatibility enable price premiums.
- ROMA PLASTIK (Gebze, Turkey): A significant exporter with large decor catalogs, Roma Plastik’s continued investment in logistics and distribution is geared toward fast delivery to neighboring markets and cost-competitive supply to EU and MENA buyers.
- Döllken-Kunststoffverarbeitung (Gladbeck, Germany): Known for processing suitability and certifications (including Greenguard), Döllken’s product positioning addresses customers prioritizing low emissions and high process yields.
Recent corporate moves reinforce two near-term themes: capacity rebalancing and capability upgrading. For example, Wilsonart’s 2026 expansion in Texas targets ABS supply for healthcare furniture, signaling demand pockets where compliance and sterilization requirements favor specific polymers. REHAU’s additional inkjet lines underscore the commercial viability of high-resolution, tactile edge bands. Regional expansions from Asian and Turkish producers, plus logistics investments, point to intensifying competition on lead times and total delivered cost.
Market dynamics, headwinds and regulatory inflection points
- Raw-material volatility: Polypropylene, a core feedstock, rose ~19.2% between 2021–2023. Such swings materially affect production economics for PP-based edgebands and magnify the value of procurement hedges and flexible compounding capabilities.
- Regulatory pressure and material substitution: Environmental regulations and end-of-life concerns have elevated interest in non-chlorinated alternatives. ABS, being chlorine-free and incinerable under authorized conditions, is increasingly positioned as a strategic alternative to PVC in regulated markets.
- Trade and tariff friction: New tariff measures (including recent duties on certain imports) increase landed costs for cross-border suppliers and enhance the strategic case for nearshoring or local inventory hubs to serve sensitive verticals.
- Geopolitical supply disruptions: Sanctions and energy-market shocks stemming from the Russia–Ukraine conflict have amplified feedstock (ethylene/ethylene-derived PVC) cost volatility, necessitating contingency planning for polymer supply chains.
- Industry sentiment: Our sector canvass finds that roughly 42% of manufacturers cite raw-material price volatility and environmental regulation as top operational challenges — a material share that should shape both short-term procurement and longer-term product strategy.
Strategic imperatives for 2026
- Re-assess product mix through a regulatory lens: Accelerate ABS and specialty polymer capabilities where market access risks for PVC are rising, and evaluate recycling-ready formulations where certification yields commercial advantage.
- Invest selectively in digital decor and haptic finishes: Moves by market leaders to boost inkjet and texture capacity demonstrate clear margin upside in design-led segments — prioritize pilot projects tied to blue-chip furniture accounts.
- De-risk supply via regional sourcing hubs: Given tariff shifts and freight volatility, nearshoring and multi-sourcing lower the chance of production stoppages and protect gross margins.
- Embed cost-curve scenarios into pricing: Adopt dynamic pricing linked to polymer indices and freight to preserve margins while maintaining competitiveness in distributed markets.
- Scan M&A for capability and channel gaps: With medium concentration at the top, bolt-ons that add high-resolution decor, zero-joint tech or logistics networks deliver faster scale than organic builds in many cases.
Methodology and report credibility
The underlying study uses a 2025 base year, a historical window from 2020–2025 and a forecast period of 2026–2032. Estimates are derived from bottom-up market modeling calibrated against primary interviews with producers, distributors and end-users, and cross-checked against trade, customs and macroeconomic indicators. Market concentration is moderate at the top: CR3 approximates 58% and CR5 about 68%, reinforcing a market structure where leading players can shape technical standards and channel economics.
Next steps — how to use this intelligence
If you are preparing 2026 budgets, sizing capital projects, negotiating long-term polymer supply contracts, or evaluating M&A prospects in surface finishes and furniture supply chains, this study provides the decision-grade analytics and executable tools you need. The full report contains the complete segment tables, regional and application splits, SKU-level margin simulations and vendor scorecards that operational teams must access to execute confidently.
To request the full dataset, tailored scenario briefings or a 60-minute strategic workshop with our lead analyst team, please visit the PW Consulting research portal. This preview highlights the strategic imperatives and directional signal; the full intelligence unlocks the tactical playbooks your teams need to win in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Thermoplastic Edgeband Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


