



PW Consulting: Legal Practice Management Market Poised for 11.5% CAGR Through 2032

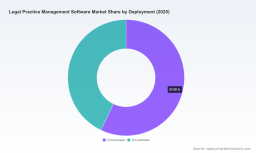
Legal Practice Management Software Market — Strategic Outlook for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market research positions Legal Practice Management Software (LPMS) as a high-growth enterprise software vertical with clear implications for law firms, technology vendors, and investors heading into 2026. Using 2025 as the base year, our top-line market model estimates the global LPMS market at approximately USD 2.68 Billion and projects expansion to roughly USD 5.74 Billion by 2032, representing a compound annual growth rate of 11.5% over the forecast horizon. This trajectory reflects accelerating cloud adoption, embedded AI, and renewed attention to automation across revenue operations and trust accounting.
Legal Practice Management Software Market
Why this research matters for 2026 strategic decisions
-
Timing: 2026 is a strategic inflection point. Buyers are moving from pilot deployments to firm-wide rollouts of cloud-native, AI-enabled platforms; vendors must convert feature parity into defensible platform value; and investors must evaluate consolidation potential within a market that remains moderately fragmented (our concentration metrics indicate meaningful presence of leading vendors but substantial room for consolidation).
Legal Practice Management Software Market -
Risk calibration: The interplay of regulatory expectations (data privacy, SOC 2, and jurisdictional ethics on AI) and operational risk (trust accounting, billing errors, client data security) creates a narrow window where technology choices materially affect regulatory exposure and client trust.
Legal Practice Management Software Market -
Value capture: Organizations that align product selection, vendor partnerships, and change management to measurable KPIs—billing cycle time, realization rates, client intake velocity, and administrative FTE reduction—stand to capture outsized ROI within 12–24 months.
Market dynamics — what is driving growth and disruption
The LPMS market growth is being driven by a combination of structural and tactical forces.
-
Cloud acceleration: The American Bar Association’s 2025 legal technology survey confirms widespread migration to cloud-based tooling. The effect is twofold: faster feature velocity from vendors and reduced capital friction for smaller firms that previously could not justify on-premises investments.
-
AI as a multiplier: Adoption of AI-driven features—automatic time capture, document summarization, precedent extraction, and predictive tasking—has jumped noticeably. ABA trend data shows AI usage among legal professionals rising sharply during 2024–2025, shifting AI from novelty to productivity enabler across practice sizes and specializations.
-
Operational pressure: Rising labor cost and the imperative to improve margin per partner push firms to automate billing, trust accounting, and matter workflows. Automated billing and integrated trust accounting reduce reconciliation errors and accelerate client collections; these operational gains translate directly into working capital improvements.
-
Regulatory overlay: Cloud platforms are increasingly evaluated on their compliance posture—SOC 2, data residency controls, and jurisdictional ethics guidelines for AI-assisted legal work. Vendors that bake in auditability and role-based controls create a durable commercial advantage, especially with mid-size and enterprise clients.
Competitive landscape — positioning the leaders and challengers
The LPMS vendor ecosystem in 2026 is a mix of specialist platforms, broader practice suites, and verticalized AI players. Below we summarize strategic profiles of the core vendors we evaluated.
-
Clio — A cloud-first incumbent that has moved aggressively to broaden platform scope through inorganic growth and premium product extensions. Clio’s recent acquisition of legal research capabilities and the launch of an enterprise-tier platform signal a shift from SMB dominance toward competing for larger, process-driven firms. Strategic implication: Clio is consolidating modular value into a platform play, increasing the importance of integration strategy for partners and customers.
-
MyCase — Positioned as an all-in-one, mid-market practical suite focused on ease of use and rapid time-to-value. Its strengths are customer experience and straightforward operational workflows; its challenge is defending against AI-enabled feature sets and deep integrations offered by larger platforms.
-
Rocket Matter — Having reimagined its product surface, Rocket Matter emphasizes modern UX and advanced practice management. The vendor is competing on performance and workflow sophistication, aiming to capture firms seeking an alternative to legacy incumbents.
-
Filevine — A serious contender on analytics and workflow orchestration. Filevine’s combination of case management and embedded analytics positions it well for practices that want operational intelligence alongside case handling.
-
Smokeball — Known for automatic time capture and document automation, Smokeball targets firms where granular matter-level productivity metrics drive fee capture. It exemplifies how task-level automation converts into higher realization.
-
PracticePanther , Centerbase , LeanLaw — These vendors skew toward specific segments: PracticePanther with broad SMB appeal, Centerbase toward mid-market integrated finance functions (recent AP automation partnership highlights this), and LeanLaw with a focused revenue operations approach built on QuickBooks integration.
-
Specialists (Lexzur, Supio, Caseflow) — Verticalized or practice-specific plays are gaining traction by automating highly repetitive litigation workflows, personal-injury workflows, or by providing in-house matter-management features that larger suites under-serve.
Recent market signals and what they reveal
-
Platform convergence: Major deals and feature rollouts during 2024–2025 show vendors layering research, advanced analytics, and enterprise-grade modules on top of core practice management—indicating vendors are moving from point-solution competition to platform differentiation.
-
Partnerships over point acquisitions: Some vendors prefer embedding third-party fintech capabilities (e.g., accounts payable, payments, or bank-feeds integration) through partnerships, accelerating time-to-market while preserving capital for strategic M&A.
-
Ethics and compliance as product features: New regulatory guidance around AI use in legal practice is driving demand for explainability, audit trails, and configurable human-in-the-loop gates. Vendors that explicitly productize compliance features reduce buyer friction.
What PW Consulting’s report contains — practical deliverables
Our report is designed for executives who need actionable insights rather than academic description. Key contents include:
-
A validated top-down and bottom-up market-sizing model (base year 2025) with scenario analysis across adoption rates, pricing evolution, and cloud migration curves.
-
Market structure and concentration assessment with implications for M&A, partnership, and go-to-market strategies.
-
Detailed vendor scorecards that map product capability, go-to-market fit, enterprise readiness, and integration posture—highlighting where each vendor wins and where they are vulnerable.
-
Commercial playbooks for buyers (evaluation checklists, procurement negotiation levers, change-management templates) and for vendors (partner ecosystems, pricing playbooks, API strategies).
-
Regulatory and ethics companion notes, detailing compliance checkpoints—particularly for trust accounting, client data security, and AI governance.
-
Forecast scenarios and an interactive model for subscribers, enabling “what-if” analysis around adoption, pricing, and consolidation waves.
Strategic implications and prioritized actions for 2026
Whether you represent a law firm, a vendor, or an investor, the following actions should be prioritized in 2026:
-
For law firms: Treat LPMS procurement as an enterprise transformation. Define success metrics tied to cash flow and realization, require SOC 2 and clear AI governance in contracts, and budget for a 12–18 month adoption program that includes workflow redesign and staff reskilling.
-
For vendors: Differentiate via platform interoperability and compliance-as-a-feature. Invest selectively in domain AI where you can demonstrate measurable FTE or margin improvement; pursue partnerships for finance automation rather than duplicative build efforts.
-
For investors and M&A teams: Look for target profiles that combine sticky customer bases, recurring revenue models, and modular APIs that facilitate ecosystem plays. The market’s fragmentation means bolt-on M&A can be value-accretive if integration risk is managed.
Data, methodology, and the limits of this preview
Our model synthesizes vendor disclosures, buyer surveys, pricing benchmarks, and primary interviews. The base year is 2025 and forecast granularity covers 2026–2032. Concentration metrics indicate a moderate degree of vendor dominance but significant pockets of opportunity for vertical specialists.
In line with our “preview” approach, this article presents the high-level market sizing, growth trajectory, competitive trends, and strategic recommendations. Detailed regional and application splits, vendor scorecard matrices, and full scenario model inputs are intentionally reserved for subscribers and report purchasers. Those datasets include the granular breakdowns, vendor revenue estimates, and adoption curves that are essential for transactional diligence and procurement negotiation.
Next steps — how to use this insight
-
If you are a buyer: Request the buyer’s checklist and the vendor comparison appendix to shorten procurement cycles and quantify expected ROI under your firm’s utilization assumptions.
-
If you are a vendor: Use our partner-readiness and API-maturity checkpoints to accelerate enterprise deals and reduce churn.
-
If you are an investor: Access the full forecast model and vendor valuation framework to stress-test acquisition scenarios across multiple deployment and pricing assumptions.
PW Consulting’s full Legal Practice Management Software Market report provides the granular metrics, vendor-by-vendor analysis, and downloadable models needed to convert the trends outlined here into executable strategies. For access to the model and the complete set of appendices, contact our research services team or visit the report page.
For detailed analysis of this topic, please visit the official page: Legal Practice Management Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


