



PW Consulting: Conductive Polymers Market to Hit $344.8M by 2032, 6.98% CAGR

Conductive Polymers Market: Strategic Briefing for 2026 Decision-Making
As PW Consulting’s lead industry analyst, I present a concise strategic briefing to frame why the conductive polymers market deserves board-level attention in 2026. This sector—bridging advanced materials science, electronics, textiles, and packaging—has evolved from a niche specialty to a strategically important category with clear commercial inflection points. Our new market study (base year 2025) synthesizes five years of historical performance (2020–2025) and provides a forward-looking roadmap through 2032 that is designed to inform investment, M&A, procurement, and innovation choices in the coming 18–36 months.
Conductive Polymers Market
Why this market matters in 2026
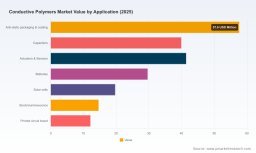
Conductive polymers are no longer an academic curiosity. Over the past half-decade the global market expanded materially—from an estimated USD 163 million in 2020 to about USD 215 million in 2025—driven by diversified end-use adoption across electronics, medical devices, smart textiles, and anti-static packaging. Our modelling projects continued growth through 2032, reaching roughly USD 345 million by the end of the forecast window, underpinned by a compound annual growth rate of approximately 7% during the forecast period. This pace positions conductive polymers as a high-value, mid-scale materials market where targeted investments can yield disproportionate strategic returns.
Conductive Polymers Market
For corporate leaders evaluating capital allocation in 2026, conductive polymers present three convergent opportunities: (1) product differentiation in high-growth electronics and wearable segments; (2) supply chain advantage through early control of specialty monomers and formulation expertise; and (3) value creation via M&A or strategic partnerships with technology-specialist suppliers.
Conductive Polymers Market
What the PW Consulting study delivers (practical, transaction-ready insights)
- Actionable market sizing and scenarios: A validated baseline (2020–2025) and three demand scenarios (conservative, baseline, accelerated) for 2026–2032 to stress-test capex and revenue plans without exposing our proprietary subsegment allocations.
- Commercial playbooks: Go-to-market strategies tailored to product players, compound formulators, and OEMs—covering pricing levers, tiered value propositions, and channel economics.
- Supply chain and sourcing diagnostics: Raw material risk matrices, alternative sourcing routes, and inventory/hedging strategies to protect margins against volatile monomer markets.
- Regulatory and sustainability roadmaps: Compliance pathways for REACH, Ecodesign/ESPR-related restrictions, and best-practice lifecycle reporting that minimize market access risk.
- Technology and IP landscape: Comparative R&D roadmaps, leading material platforms, and patent activity heatmaps to guide licensing and R&D collaboration choices.
- M&A and partnership targets: A short-list of acquisition and JV archetypes, plus valuation heuristics and integration checklists focused on rapid scale and capability acquisition.
- Commercial due diligence kits: Data room templates, key vendor interview guides, and a forensic checklist for validating supplier claims on conductivity, durability, and process repeatability.
Competitive landscape: what leading players are doing
The market shows moderate concentration: the top three suppliers account for a meaningful but not overwhelming share of the market, and the top five collectively hold roughly 30%—a structure that favors both specialized incumbents and nimble entrants. Several firms illustrate contrasting strategic postures that should be instructive to executives considering market entry or partnership.
- Premix Group (Finland) — Moving fast on scale and digital operations. Recent investments include a new U.S. manufacturing facility and deployment of an AI/ML platform (PERTTI 3.0) used to optimize recipes and enable real-time process control. These moves signal a playbook focused on supply chain proximity, automation, and data-driven quality assurance.
- Heraeus (via Heraeus Epurio, Germany) — Technology-driven incumbent with advanced conductive polymer platforms (notably PEDOT-based chemistries). The group’s expansion in China and emphasis on analytics-enabled capacity point to a dual strategy: protect premium electronics and display customers while scaling cost-effectively in APAC.
- Eeonyx Corporation (United States) — Specialist coatings and process know-how for e-textiles and industrial fabrics. Firms like Eeonyx underscore the importance of process competence (coating, deposition) alongside chemistry.
- Agfa-Gevaert Group (Belgium) — Supplier of conductive inks and films; representative of companies that combine materials science with printing/processing mastery to address flexible electronics and optical applications.
- SABIC (Saudi Arabia) — Major polymer conglomerates are entering the value chain through conductive blends and engineered compounds, offering scale advantages and distribution reach for industrial applications.
Recent corporate activities illustrate the near-term templates for success: capacity expansions in APAC, AI-enabled process control, and new high-performance grades showcased at leading industry exhibitions. These actions are not random—they reflect three strategic priorities that buyers and investors should internalize: proximity to growth markets, digitalization of formulation and production, and product-grade differentiation.
Market dynamics that will shape 2026 decisions
- Raw material and feedstock risk: The economics of conductive polymer manufacturing are sensitive to a small set of specialty monomers. For example, high-purity EDOT for PEDOT derivatives commands a premium and can materially affect unit economics. Volatility in aniline and other specialty monomer markets exerts acute short-term pressure—especially on APAC production nodes—requiring procurement strategies that include hedging, alternative chemistries, and supplier partnerships.
- Regulatory tailwinds and constraints: REACH registration requirements and the EU’s Ecodesign/ESPR frameworks are increasing the cost of market entry for chemically complex formulations. Companies that build compliant ingredient registries and circularity claims now will face lower commercial friction in 2027–2030.
- Manufacturing as a competitive moat: Investments in automation, inline conductivity monitoring, and recipe libraries (the kind illustrated by PERTTI 3.0 deployments) shorten time-to-spec and reduce scrap—translating into margin expansion for manufacturers that industrialize formulation science.
- Application diversification: While electronics and anti-static packaging remain core buyers, growing demand from wearables, electroluminescent devices, and energy storage niches is broadening the demand base and changing performance benchmarks (mechanical flexibility, long-term stability, and lower-temperature processing).
Implications for strategic choices in 2026
Executives should treat 2026 as an inflection year. The combination of revenue growth velocity (projected mid-single-digit CAGR across the forecast window), evolving regulatory constraints, and supplier digitization creates multiple decision points:
- Procurement and sourcing: Move from spot-based buying to strategic raw material partnerships or tolling arrangements for high-purity monomers. Consider regional stocking hubs to mitigate short-term supply shocks.
- Capex and capacity: Prioritize flexible, digitally instrumented capacity that can accommodate multiple conductive formulations. Greenfield expansion should be measured against tolling and JV options with established formulators.
- R&D and differentiation: Invest in formulation IP that targets the mechanical and environmental performance attributes demanded by next-generation wearables and flexible electronics. Shared R&D consortia can accelerate pre-competitive work while spreading cost.
- M&A and partnerships: Pursue bolt-on acquisitions that provide process know-how (coating, printing), regulatory dossiers, or access to proprietary monomers. Small-to-mid acquisitions can quickly lift both capability and customer access in a market where scale is balanced by specialized know-how.
- Regulatory and sustainability positioning: Build registries and lifecycle datasets now to avoid market access bottlenecks in the EU and to meet procurement thresholds from multinational OEMs.
How PW Consulting’s study supports your 2026 actions
The report is structured to be a working tool—suitable for corporate strategy teams, corporate development, procurement, and R&D leadership. It combines rigorous top-down market sizing with bottom-up checks, supplier intelligence, regulatory impact analysis, and a transaction-focused annex including diligence templates and valuation frameworks. Importantly, while the study demonstrates where growth pockets are developing, it purposely limits public disclosure of our granular segment-by-segment maps to preserve the commercial edge for subscribers.
In short: the conductive polymers market is entering a phase of professionalization. The winners will be those who align advanced materials IP with resilient supply chains, regulatory foresight, and digitally enabled manufacturing. Our analysis shows the pathway to capture value—whether through targeted partnerships, disciplined capacity plays, or selective M&A—without overpaying for surface-area growth.
Next steps
- Contact PW Consulting to schedule a tailored briefing and scenario workshop for your leadership team.
- Request the subscriber edition of the report to access detailed subsegment analyses, supplier scorecards, and the M&A target short-list.
We designed this briefing to give you directional clarity for 2026 while reserving the granular intelligence that will enable executable strategies. For companies seeking to translate the projected market momentum into defensible commercial advantage, the window to act is now.
For detailed analysis of this topic, please visit the official page: Conductive Polymers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


