



Digital Piano Market to Hit USD 2,025 Million in 2025, Poised for 5.0% CAGR — PW Consulting

Digital Piano Market 2026 — Strategic Preview for Corporate Decision-Makers
As PW Consulting’s senior strategy advisor and lead industry analyst, I present an executive preview of our Digital Piano Market study (base year: 2025). This piece is designed as a high-fidelity “trailer”: it surfaces the evidence-based trends, competitive dynamics, and decision levers that should shape boardroom priorities in 2026, while preserving the granular segmentation and proprietary datasets that drive transaction-level decisions for subscribers of the full report.
Digital Piano Market
Market snapshot — trajectory and scale
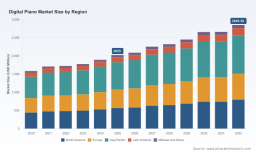
Our market model—anchored on historical performance from 2020–2025 and a detailed forecast through 2032—shows the digital piano market continuing a steady expansion at a compound annual growth rate of approximately 5.0% over the forecast window. All figures in this article are expressed in USD Million. After recovering from early-decade disruption, the global market recorded robust growth into 2025 and moves into 2026 with upward momentum. The market value in 2025 provides the strategic baseline for planning; our scenario-driven forecasts point to sustained scale-up through the early 2030s, reflecting steady demand across consumer learning, entertainment and performance use cases and ongoing product innovation.
Digital Piano Market
Key modelling levers: macro consumer spending trajectories, channel evolution (bricks-and-clicks), product cycle refresh rates, and supplier cost dynamics. These inputs combine to produce a forward view that is constructive but nuanced—growth is consistent rather than explosive, which means 2026 will be a year for strategic positioning rather than an all‑out market grab.
Digital Piano Market
Why this study matters for 2026 decisions
Five strategic implications should guide executive agendas this year.
- Product tiering and R&D allocation. With demand growth steady, the highest ROI will come from clear differentiation: premium sound engines and hybrid actions for high-end buyers, and durable, affordable designs for entry-level segments. Investment should prioritize perceptible features—acoustic modeling, expressive key action, and software integration—that influence purchase decisions and justify price premiums.
- Pricing governance and response capability. The market is sensitive to pricing moves from incumbents. Notably, a recent price adjustment by a major player in mid‑2026 underscores how strategic repricing can resegment value perceptions and open share opportunities for agile competitors. Companies must establish rapid competitive reaction frameworks and test elasticities by channel and SKU.
- Channel mix optimization. Omnichannel orchestration (direct-to-consumer, specialty retailers, institutional sales to schools and conservatories) will determine share shifts. Digital-first marketing and software-mediated product demos are increasingly decisive for conversion and aftermarket monetization.
- Supply chain resilience and compliance. Operational continuity hinges on vendor diversification, environmental certification, and duty-aware logistics. HS code clarity and absence of new export controls in 2026 reduce tariff uncertainty, but manufacturers should maintain ISO 14001 alignment and monitor component inputs (acoustic woods, specialized electronic components) for sourcing concentration and quality risk.
- M&A and partnership playbooks. With top-three concentration that is meaningful but not dominant and a top-five footprint that controls a majority of the market, there is room for targeted acquisitions, white-label partnerships, and OEM/ODM strategies to accelerate scale—particularly for entrants seeking distribution depth or for incumbents looking to bolt on technology or cost advantages.
What the full PW Consulting report delivers (practical outputs)
This study is structured to convert market intelligence into executable plans. Highlights include:
- Proprietary market size and growth model (historical 2020–2025, forecast 2026–2032) with scenario sensitivities and policy shock simulations.
- Segment-level playbooks: market opportunity maps by type, channel, and application with prioritized initiatives and quick-win tactics (note: full segment tables and numeric splits are available only in the subscriber report).
- Competitive scorecards and capability matrices for leading manufacturers, complemented by product benchmarking across sound engines, key action technology, software ecosystems, and price tiers.
- Go-to-market templates tailored for OEMs, D2C brands, and specialty retailers—covering assortment strategy, channel incentives, digital trials, and service propositions.
- Supply chain heatmaps and supplier risk dashboards showing component concentration, environmental compliance checkpoints, and logistic scenarios.
- Investment and M&A dossiers—target identification criteria, valuation heuristics, and integration red flags for acquirers or JV partners.
- Regulatory and sustainability tracker: duty classifications, certification requirements, and environmental management expectations for manufacturing operations.
Competitive landscape — what to watch
The market’s competitive architecture is characterized by a handful of established players with strong brand equity and technological IP, meaningful mid‑tier specialists, and a broad base of entry-level OEM/ODM manufacturers. Market concentration metrics indicate that the top three firms collectively hold a notable share of industry revenues while the top five cross the majority threshold—this creates a balance between incumbent strength and margin for challengers with the right playbooks.
- Yamaha Corporation (Hamamatsu, Japan) — Signature offerings such as Clavinova and Arius combine sophisticated sound engines with seamless app ecosystems. Yamaha’s pricing and positioning moves have immediate spillover effects across premium and education channels; the supplier’s May 2026 price change is an example of how legacy brands can reshape competitive dynamics and margin pools.
- Roland Corporation (Hamamatsu, Japan) — The FP and GP series emphasize portability and immersive acoustics via PureAcoustic technologies. Roland’s early-2026 collaboration with Karimoku (artisan cabinetry) to launch artisan digital pianos signals a focused premiumization strategy that blends heritage craftsmanship with modern electronics, increasing differentiation in the upper-end market.
- Kawai — Known for Harmonic Imaging and refined key actions, Kawai is a technical stalwart in the high-fidelity segment. The firm’s investments in acoustic emulation warrant attention from competitors seeking parity in expressive performance.
- Casio — Competes on price-performance with innovations in hybrid hammer action and compact form factors. Casio’s technology focus makes it a persistent threat in volume channels and in emerging digital-native buyer cohorts.
- Korg and Clavia (Nord) — Korg’s portable lines and Clavia’s AI sampling/modeling strengths cater to niche performers and studio professionals; both underscore the importance of software and modeling excellence as points of differentiation.
- Williams and Lida — Williams leverages US distribution and value-focused console design, while Lida (China-based OEM/ODM) plays a critical role in cost-competitive entry segments and private-label supply. Their positioning highlights the bifurcation of the market between brand-led premium and cost-efficient volume supply chains.
Regulatory, materials and operational considerations
Operational decision-makers should note four practical dynamics:
- Customs and duty stability: the HS classification for digital pianos provides clarity for cross-border logistics; no targeted tariff updates were identified in 2026, reducing one axis of near-term trade risk.
- Environmental management: ISO 14001 continues to be a de facto expectation for manufacturing sites; buyers and institutional customers increasingly require documented environmental management practices.
- Raw material complexity: premium models depend on acoustic woods and specialized soundboard materials. While no new material controls emerged in 2026, procurement teams should maintain supplier diversification and monitor availability/quality variance.
- Compliance discipline: absence of new export controls is positive, but firms must keep legal and supply teams aligned with shifting national requirements and voluntary sustainability standards demanded by key retail partners.
Strategic playbook for 2026 — five priority actions
- Execute a two-track product strategy: accelerate premium feature rollouts for affluent and institutional buyers while protecting margins on entry models through cost engineering and bundled services.
- Recalibrate pricing helmets and elasticities; use targeted promotions and differentiated finance options rather than blunt across-the-board discounts.
- Invest in software ecosystems and subscription services (lesson: hardware differentiation is necessary but not sufficient; recurring revenue enhances lifetime value).
- Strengthen supply chain visibility with a dual-sourcing mandate for critical components and a supplier scorecard tied to environmental metrics.
- Scan the acquisition landscape for capability gaps—particularly in modeling engines, voice/sound IP, and distribution assets—where tuck-ins can accelerate market access at lower risk than greenfield builds.
Conclusion — positioning for measured growth
2026 is a year to consolidate strategic positioning rather than chase unsustainable volume. The market’s steady 5.0% growth profile rewards disciplined investment in perceived value drivers—sound authenticity, action realism, and integrated digital experiences—while cost and supply chain management protect margins. Competitive moves by legacy brands and specialty entrants will continue to create localized dislocations; success will go to players who combine product excellence, nimble pricing, and a resilient, compliant supply base.
To convert these insights into executable plans, access to the full PW Consulting Digital Piano Market report is required—the subscription edition contains the complete segment-level datasets, regional and application splits, detailed competitor scorecards, and the reproducible financial model that underpins our forecasts. Those datasets are intentionally withheld here to preserve the report’s commercial value and to ensure decision-makers have a single authoritative source for transactional use.
For inquiries about licensing the dataset, custom benchmarking, or a tailored decision workshop based on the report, PW Consulting’s strategy team is available to support immediate 2026 planning cycles.
For detailed analysis of this topic, please visit the official page: Digital Piano Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


