



PW Consulting: Fiber Optic Cable Assembly Market to Reach USD 11,130M by 2032 at 6.9% CAGR

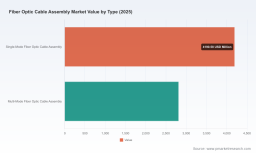
Fiber Optic Cable Assembly Market — A Strategic Preview for 2026 Decision‑Makers
As PW Consulting’s lead industry analyst, I present a focused, executive‑grade preview of our new Fiber Optic Cable Assembly Market study. This briefing highlights the strategic lines of force that will determine winners and losers through 2026 and beyond, while deliberately preserving the granular segmentation tables and proprietary scorecards that deliver competitive advantage — those are reserved for the full report.
Fiber Optic Cable Assembly Market
Why this research matters in 2026
The fiber optic cable assembly market is no longer a niche component market: it is a foundational enabler for data‑rich economies, defense systems, and decarbonization infrastructures. In our base year (2025), the market sized at USD 7,000 Million. After recovering steadily from 2020 levels, the industry enters a period of sustained expansion; our forecast (2026–2032) projects a compound annual growth rate of 6.9%, taking the market to roughly USD 11,130 Million by 2032. These macro dynamics — combined with regulatory shifts and concentrated pockets of technological differentiation — make 2026 a decisive year for capital allocation, sourcing strategy, and M&A activity.
Fiber Optic Cable Assembly Market
Analytical framework and what's inside the full report
- Proven methodology: demand‑side and supply‑side triangulation using bottom‑up vendor modelling, project pipelines, and installation cost curves.
- Historical baseline (2020–2025) and forward scenarios (2026–2032) with sensitivity to CAPEX cycles, component shortages, and tariff events.
- Practical deliverables: supplier heatmaps, procurement negotiation templates, total cost of ownership (TCO) calculators for prefabricated vs. field‑terminated assemblies, and a manufacturing checklist for ISO 5–ISO 7 cleanroom readiness.
- Vendor due diligence materials: comparable scorecards, margin benchmarks, and a shortlist of acquisition targets by strategic objective.
- Regulatory and policy playbooks: compliance checklists and scenario responses for emerging rules affecting safety, export controls, and subsea security.
Note: this executive summary surfaces the strategic insights you need to steer 2026 decisions. Detailed regional and application‑level tables, unit economics, and proprietary vendor rankings are excluded here to protect the commercial value of the study; access to the full dataset is available through our report portal.
Fiber Optic Cable Assembly Market
Key themes shaping strategies in 2026
- Volume growth with asymmetric value pools. Aggregate demand is expanding steadily, but value accrues unevenly: high‑precision assemblies for defense, space, and hyperscale datacenters command premium margins relative to commodity patch cords.
- Manufacturing quality and regulatory qualification are strategic differentiators. Cleanroom assembly (ISO 5–ISO 7) and validated qualification pathways are increasingly mandatory for mission‑critical applications; early compliance investments lower certification risk and speed time‑to‑contract.
- Infrastructure projects drive localized demand spikes. Public works and transportation projects are catalyzing installation activity in specific corridors, producing opportunities for contractors and preterminated solutions that reduce field labor.
- Geopolitics and trade policy fragment sourcing choices. Tariffs and new government programs focused on subsea security and supply‑chain resilience raise the cost of single‑region sourcing and tilt procurement toward diversification and nearshoring.
- Market structure: a fragmented core with specialist leaders. Market concentration remains modest — the top three firms account for roughly one quarter of market value, with the top five reaching about thirty percent — leaving substantial room for vertical specialists and regional champions to thrive.
Competitive landscape — who matters and why
The supplier set spans full‑spectrum manufacturers, precision boutique producers, ruggedized specialists, and broad‑reach distributors. Understanding each type is essential for aligning sourcing and partnership strategy.
- Optical Cable Corporation (Roanoke, VA) — A pioneer in military/tactical and enterprise assemblies, OCC’s breadth includes pre‑terminated and custom variants. Its recent strategic collaboration (July 2025) with a systems partner underscores an intent to expand into enterprise and data‑center verticals through combined product and channel plays.
- Diamond SA (Switzerland) — Recognized for high‑precision interconnects and cleanroom production, Diamond is an archetype for firms that command premium pricing in space, aerospace, and laboratory markets where contamination control and traceable processes are contract prerequisites.
- L‑com Global Connectivity (North Andover, MA) — Focused on ruggedized, pre‑terminated assemblies and patch cords, L‑com is positioned where industrial reliability and rapid deployment matter, particularly in verticals that value plug‑and‑play field solutions.
- Fiber Instruments Sales, Inc. (USA) — A distributor and manufacturing support player, this firm is valuable for buyers seeking breadth of catalog, fusion‑splice capability and field‑installable options, reducing lead times on low‑to‑mid complexity requirements.
- fiberone, llc (USA) — A specialist in custom multi‑fiber assemblies; its updated 2026 product catalog highlights the importance of configurability and rapid prototyping for bespoke customer requirements.
Strategic takeaway: partnering with a single global vendor is rarely optimal in 2026. A modular supplier strategy — pairing high‑precision producers for mission‑critical assemblies with regional fabricators or distributors for scale and responsiveness — reduces certification risk and shortens lead times.
Regulatory and geopolitical developments that change the playbook
- Certification and safety standards. New regulatory guidance for qualification of fiber components in safety‑critical systems raises the bar for suppliers wishing to compete in nuclear, aviation, and energy markets. Early adoption of qualification programs converts into long‑term contract advantages.
- Subsea security and export controls. Legislative attention to subsea cable security and maintenance elevates national‑interest considerations, potentially altering who can bid on sensitive projects and increasing the role of government stakeholders in procurement decisions.
- Trade policy and tariffs. Persistent tariffs on certain imports remain a non‑trivial cost factor for sourcing strategies; procurement teams must model tariff scenarios into landed cost and supplier total cost analyses.
Concrete actions for executives in 2026
- Chief Procurement Officer: Implement a three‑tier sourcing model (strategic/qualified partners; regional fulfillment partners; contingency suppliers) and adopt TCO calculators that incorporate tariffs and qualification lead times.
- Head of Network/Infrastructure: Prioritize pre‑terminated assemblies for new buildouts to lower field labor exposure; require supplier qualification evidence for safety‑critical segments.
- Head of Manufacturing/Operations: Evaluate targeted investments in cleanroom capability (or contract partnerships with certified facilities) to access high‑value aerospace/defense contracts.
- Corporate Strategy & M&A: Screen acquisition targets that fill capability gaps (cleanroom production, specialty multi‑fiber designs, or regional fulfillment) and favor targets with validated customer qualifications.
- Compliance & Legal: Build a watchlist of regulatory developments (safety qualification guides, subsea policy, trade actions) and design contractual clauses that allocate certification and tariff risks appropriately.
Why purchase the full PW Consulting report
This preview explains the strategic stakes but omits the detailed segmentation, unit economics, and proprietary vendor scoring that you need to execute with confidence. The full study delivers:
- Detailed breakouts by region, type, and application with historical and forecasted values;
- Vendor financial and capability benchmarking, including contract references and supply‑risk ratings;
- Installation cost plots and TCO models by project type; and
- Playbooks for procurement negotiations, qualification programs, and M&A integration.
Purchasing the full report gives you the defensible data to justify capital budgets, the supplier matrices to rapidly identify preferred partners, and the scenario models to stress‑test strategic plans in the face of tariff and regulatory volatility.
For 2026, the central strategic question for executives is simple: will you treat fiber assemblies as a commodity to be optimized on price, or as a strategic lever that secures differentiated performance and recurring revenue? Our work shows that companies taking the latter view — investing selectively in qualification, modular sourcing, and cleanroom capability — are the most likely to capture outsized returns as the market scales toward USD 11,130 Million by 2032.
To access the complete dataset, vendor matrices, and tactical playbooks, visit the PW Consulting report page and download the full Fiber Optic Cable Assembly Market study.
For detailed analysis of this topic, please visit the official page: Fiber Optic Cable Assembly Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


