



PW Consulting: Compact Construction Equipment Market Poised for 5.1% CAGR (2026-2032)

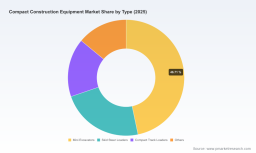
Compact Construction Equipment Market — Strategic Imperatives for 2026
Executive snapshot
As PW Consulting’s latest market study (base year 2025) shows, the compact construction equipment market has moved from recovery into steady expansion. After a post-pandemic ramp from 2020 through 2025, the market reached an important inflection in 2025 and is forecast across our 2026–2032 planning window to grow at a compound annual growth rate (CAGR) of 5.1%. By 2032 the market is projected to approach the low hundreds of millions USD scale — a level that makes targeted investments and strategic repositioning materially consequential for manufacturers, distributors, financiers, and large fleet owners in 2026.
Compact Construction Equipment Market
Why this study is strategically valuable for 2026 decision-making
-
Timing matters: 2026 is the year in which recent regulatory shifts, trade frictions, and new product waves converge. Executives who align 2026 capital allocation and go-to-market plans with the structural dynamics identified in this study will capture disproportionate share gains over the next investment cycle.
Compact Construction Equipment Market -
De-risking investments: Our forecast and scenario modules translate market momentum and downside stress into actionable capital and inventory decisions — allowing CFOs to size financing facilities and CAPEX with confidence while preserving optionality.
Compact Construction Equipment Market -
Road-mapping product portfolios: Product teams can use the study to prioritize electrification, automation, and modularity investments that will improve time-to-value for end customers and accelerate aftermarket revenue growth.
-
Channel optimization: Dealers and OEMs can operationalize the report’s dealer performance and network efficiency analyses to improve availability, reduce days-to-deployment, and lift incremental margin.
Market dynamics driving 2026 strategic choices
-
Labor availability and productivity. Persistent skilled labor shortages across construction segments are accelerating demand for machines that reduce operator onboarding time, integrate automation-assist features, and simplify maintenance. Equipment with intuitive controls and remote diagnostics can shorten project timelines and materially improve utilization.
-
Regulatory acceleration. The regulatory environment is tightening in several major markets — from Europe’s updated construction product compliance requirements to state-level energy codes in the United States. These rules are shifting product specifications, supplier documentation requirements, and time-to-market constraints. Companies that embed compliance workflows into engineering and quality assurance will shorten certification cycles and gain first-mover advantages.
-
Raw-material and supply-chain pressure. Volatility in steel and aluminum costs, compounded by tariff patterns and geopolitical trade frictions, continues to compress margins and complicate inventory strategies. Manufacturers that adopt advanced alloys strategically and redesign components for multi-sourcing reduce exposure and improve lifecycle costs.
-
Electrification and materials engineering. New uses of high-strength steels and advanced alloys on booms and chassis are already extending service intervals and reducing total cost of ownership. At the same time, OEMs are accelerating electric and hybrid introductions — with multiple OEMs demonstrating electric mini-excavator and compact loader concepts at major trade shows in early 2026.
-
Financing and procurement innovations. Flexible financing offers and OEM-led financing programs are changing the buyer decision matrix. Competitive financing windows allow OEMs to shorten sales cycles and lock in fleet conversions; procurement teams should be ready to quantify the PV of financing incentives when evaluating supplier bids.
Competitive landscape — what OEM moves tell us about next steps
The market shows a moderate level of concentration, with the top three players controlling just over half of demand and the top five commanding nearly two-thirds — a structure that supports both scale advantages and tactical openings for focused challengers. Our qualitative and quantitative assessments of leading OEM behavior highlight five strategic playbooks in operation today:
-
Platform modernization by legacy leaders. Established OEMs continue to leverage product depth and service networks while modernizing platforms for electrification and telematics integration. These firms prioritize reliability, parts availability, and dealer training to protect installed-base value.
-
Strategic financing as a growth lever. Financing packages tied to limited-time APR incentives have become a tool for market share acceleration and inventory turnover. Such offers directly influence fleet renewal cycles and should be modeled into demand elasticity assessments.
-
Regional expansion from cost-effective entrants. Several international OEMs have amplified trade-show participation and targeted product launches to accelerate channel entry into North America and Europe, using multi-brand strategies to achieve quick scale.
-
Product differentiation via automation and smart features. New concepts and next-generation compact machines emphasize operator-assist functions and simplified telematics. Early adopters of these features can capture higher aftermarket software and services revenue.
-
Electrification pilots and demonstrators. Multiple OEMs launched electric mini-excavator and compact loader variants at 2026 industry events, signaling an imminent shift in product road maps and aftermarket ecosystems.
Collectively, these moves mean that competitive positioning in 2026 will be decided by who can best integrate product, service, financing, and compliance into a coherent value proposition — not just by scale alone.
Recent industry signals (Q1 2026) worth noting
-
Major trade-show momentum: Several OEMs used CONEXPO-CON/AGG 2026 to launch electric mini-excavators, next-generation smart skidsteers, and region-specific product lineups. These demonstrations are precursors to near-term commercial rollouts and rental-fleet trials.
-
Channel and entry plays: New booth strategies and hands-on demos by international manufacturers point to aggressive market-entry priorities for 2026 and a higher likelihood of localized distribution partnerships.
-
Service and demo investments: Exhibitor strategies emphasizing hands-on demonstrations reflect a shift toward experiential selling — buyers increasingly require proof of productivity, not just specification sheets.
What the PW Consulting report delivers — practical, executable content
This study is intentionally practitioner-focused. It is structured to convert insight into action by offering:
-
Market sizing and forecast model (2020–2032) with drillable assumptions and scenario toggles so finance teams can run sensitivity analyses against price, material cost, and regulatory shock scenarios.
-
Demand-driver analytics that link macro construction activity, labor supply, and financing availability to unit displacement rates and replacement cycles.
-
Supply-chain and input-cost heatmaps that identify single-source risks and recommend mitigation strategies — from strategic safety stock and hedging to dual-sourcing and near-shore options.
-
Competitive benchmarking and playbook templates for product launches, dealer network optimization, and aftermarket monetization.
-
Regulatory compliance checklists and engineering change roadmaps tailored to imminent legal requirements and certification timelines relevant to North American and European markets.
-
Go-to-market templates, including segmented buyer personas, lead-conversion playbooks for dealer networks, and experiment protocols for piloting electric fleets with rental partners.
-
M&A and partnership screeners that flag targets by capability (telematics, battery systems, regional distribution) and quantify expected synergies under conservative and aggressive integration assumptions.
-
Tools for operational teams: dealer scorecards, service-level KPIs, TCO calculators, and a prioritized roadmap for digitizing service operations to reduce downtime and extend asset life.
How executives should use the study in 2026 — recommended actions by function
-
CEO / Strategy: Reassess portfolio bets — prioritize platforms that can be modularized for electric and hybrid powertrains and accelerate partnerships with telematics providers.
-
CFO: Recalculate cash-flow scenarios including financing incentives and inventory hedges; deploy stress tests against raw-material shocks and regulatory-driven rework costs.
-
COO / Supply Chain: Implement targeted dual-sourcing and flexible manufacturing options for high-risk components; optimize lead-times using the report’s supplier-risk matrix.
-
CTO / R&D: Sequence investment in electrification and automation features using the short-list of customer use cases and ROI thresholds provided in the study.
-
Head of Sales / Distribution: Rework dealer economics to reward quicker demo-to-deal conversion and integrate OEM financing tools into pricing negotiations.
-
CHRO: Deploy training programs aligned to automation-augmented operating models to lower operator onboarding time and support higher utilization.
Closing — the strategic take
The compact construction equipment market in 2026 is no longer a niche adjunct to heavy construction; it is a core battleground for productivity gains, margin expansion, and new service revenues. With the market on a steady multi-year growth trajectory and competitive concentration that favors the nimble as much as the large, companies that combine disciplined capital allocation, targeted product investments, and dealer-centric execution will secure outsized returns.
PW Consulting’s full report provides the granular regional, product-type, and application-level intelligence — along with downloadable models and scenario tools — needed to translate these insights into tactical 90-day and 18-month programs. To review the complete breakdowns, interactive dashboards, and model assumptions that underpin our 2026 recommendations, download the full study on our website.
For detailed analysis of this topic, please visit the official page: Compact Construction Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


