



PW Consulting: Isothermal Packaging to reach USD134.8M by 2032 at 5.7% CAGR

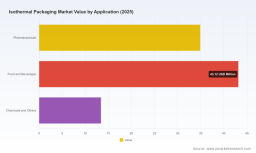
Isothermal Packaging Market — Strategic Briefing for 2026 Decisions
As PW Consulting’s Chief Industry Analyst, I present a compact, decision-focused introduction to our Isothermal Packaging Market study. This briefing distills the structural forces, competitive postures, and scenario-ready choices that corporate leaders must consider as they set strategy for 2026. The full report (base year 2025; historical window 2020–2025; forecast 2026–2032) contains the granular segment intelligence and transaction-level models that underpin the recommendations summarized below.
Isothermal Packaging Market
Executive snapshot
The isothermal packaging market has demonstrated consistent expansion through the first half of the decade and, on our base projections, continues to grow at a compound annual growth rate (CAGR) of approximately 5.7% across the forecast window. In revenue terms (USD, Million), the market roughly doubles over the 2020–2032 horizon under a business-as-usual scenario, reflecting structural demand from life sciences, pharma logistics, and temperature-sensitive food and beverage distribution.
Isothermal Packaging Market
Why this matters for 2026 strategic planning
- Timing of capacity and capability investments: With mid-single-digit CAGR persistence, 2026 is a critical year for firms to decide whether to scale manufacturing lines, expand reusable programs, or pivot to higher-margin engineered solutions. Small timing errors compound quickly over multi-year product lifecycles.
- Capital allocation and partnership choices: Growth is not evenly distributed by technology or go-to-market model. Firms that lock in manufacturing relationships, material supply agreements, or reverse-logistics partnerships early in 2026 will capture advantaged cost positions.
- Regulatory and EPR readiness: Emerging Extended Producer Responsibility (EPR) requirements and UN temperature-sensitive shipment rules are making compliance an operational imperative; preparedness will determine market access and tender eligibility in major pharma and clinical-trial accounts.
Market trajectory — what the macro picture tells us
Over the historical window, the market expanded steadily as pharmaceutical cold chain needs intensified and food supply chains upgraded temperature control. Our forecast continues that upward trend: the market scales further through 2032, driven by rising biologics volumes, expanded clinical trial activity that demands reliable single-use and reusable thermal shippers, and growing demand for sustainable solutions that balance insulation performance with lifecycle emissions. The combination of steady market expansion and moderate concentration (the top three and top five firms account for material, but not dominant, shares) creates both scale opportunities and white spaces for focused entrants.
Isothermal Packaging Market
Competitive landscape — strategic postures to watch
We examined the profiles and strategic behaviors of leading incumbents and strong regional specialists. The competitive dynamic splits along several axes: engineering depth (high-performance passive systems), circular-program capability (reuse + reverse logistics), raw-material integration, and compliance/digital-enablement. Key archetypes in the market include:
- High-performance life-sciences specialists: Firms with design and engineering focus on vaccine and biologics shipments emphasize validated thermal performance and temperature excursion risk management. These players often package reuse programs and reverse logistics services to capture lifecycle value.
- Sustainable, lightweight innovators: Companies that prioritize low-weight, low-carbon materials (including increased use of recycled fibers and low-impact insulation) are winning tenders where sustainability metrics feed procurement decisions.
- Full-solution cold-chain providers: Providers that combine insulated containers, phase-change materials, monitoring electronics, and program management create friction for fragmented competitors by offering end-to-end guarantees and logistics integration.
Representative companies examined in the report include established life-sciences specialists, sustainable European manufacturers, and North American integrators. Their strategic moves—productization of reusable systems, investments in reverse-logistics, and alignment with pharmaceutical cold-chain service providers—illustrate the market’s evolution from commodity shippers to program-based commercial models.
Supply chain, raw materials, and cost dynamics
Raw-material dynamics are central to cost and sustainability outcomes. Polyurethane-based insulation remains a primary workhorse for many high-performance solutions, while post-industrial recycled cardboard and other recycled content are increasingly integrated to meet sustainability targets and manage cost volatility. Material price swings, container reuse logistics, and secondary-market availability of recycled inputs will be key levers for margin management in 2026. Firms that structure long-term supply agreements, invest in validated recycled-material formulations, or secure diversified suppliers will be better insulated from input shocks.
Regulation and sustainability — risk turned into advantage
- Regulatory guardrails: Temperature-sensitive shipments must conform to industry and UN standards; compliance is non-negotiable for access to regulated pharma channels. Companies that embed compliance validation into product offerings and sales propositions shorten procurement cycles and reduce deployment friction.
- EPR and circularity: Extended Producer Responsibility schemes targeting plastic components are creating both costs and strategic opportunities. Early adopters of takeback and refurbishment programs can reduce lifecyle costs and capture reuse-margin pools, while those that lag will face escalating disposal liabilities and procurement exclusion risks.
- Decarbonization demands: Buyers increasingly evaluate lifecycle emissions and supplier sustainability credentials; packaging providers that can quantify and certify lower-impact solutions gain a commercial edge.
Where segmentation matters — and what we deliberately withhold
Segmentation by region, insulation type, and application drives portfolio choices and go-to-market tactics. The full PW Consulting report provides validated, granular splits and growth profiles across these dimensions—and those segment-level figures are critical for tactical choices such as plant location, SKU rationalization, and targeted sales plays. In this briefing I intentionally withhold the detailed segment percentages and transaction-level figures to preserve the strategic value of the full dataset and to encourage direct engagement with the source study for deal or investment work.
Strategic implications and recommended actions for 2026
Below are prioritized, pragmatic moves that executives should consider in 2026. These are structured to be implementable within 90–180 days and scaled into multi-year programs.
- Validate product–customer fit for reusable programs: Run 2–3 pilot reverse-logistics routes with anchor life-sciences customers. Use pilots to quantify end-to-end cost-to-serve, carbon reductions, and SKU turnover.
- Lock material supply and test recycled-content formulations: Secure multi-year supply contracts for critical insulation feedstocks and validate formulations that incorporate post-industrial recycled fibers to meet buyer sustainability thresholds.
- Build regulatory-ready propositions: Invest in UN-compliance validation and develop standardized documentation bundles for pharma procurement teams. Consider third-party certifications to shorten sales cycles.
- Digitize the value chain: Integrate temperature monitoring, telematics, and shipment analytics into product offerings to move from component sales to subscription-style assurance services.
- Pursue adjacency partnerships: Negotiate distribution or co-development agreements with cold-chain logistics providers and clinical-trial service firms to secure preferred-supplier status for high-value account flows.
What the PW Consulting report delivers (practical contents)
The study synthesizes primary interviews, supplier cost models, validated performance matrices, and demand simulations to produce actionable outputs for decision-makers:
- Market sizes and forecasts (historical 2020–2025; forecast 2026–2032) with scenario analyses and sensitivity to raw-material pricing and reuse-uptake rates.
- Competitive playbooks: capability maps, investment heatmaps, and acquisition targets scored by strategic fit.
- Regulatory and sustainability roadmaps: compliance checklists, EPR impact models, and product redesign cost estimates.
- Commercial templates: tender response playbooks, reuse-program P&L models, and digital-service monetization frameworks.
- Manufacturing and logistics blueprint: capacity planning tools and suggested network configurations aligned to demand clusters.
How to use this briefing in board-level decision-making
For 2026 planning cycles, elevate isothermal packaging from an operational procurement line item to a strategic option set. Use the report to:
- Inform capital allocation and M&A screening by applying scenario P&Ls to proposed plant expansions or bolt-on acquisitions.
- Prioritize product development investments—insulation R&D, validated reusable platforms, and digital assurance—by matching capability gaps to targeted customers.
- Design go-to-market pilots with measurable KPIs (cost per shipment, carbon per shipment, percentage reused) to create evidence for full-scale rollouts.
Closing and next steps
The isothermal packaging market in 2026 is characterized by steady expansion, meaningful opportunities for differentiation, and intensifying regulatory and sustainability pressures that will reallocate value across the chain. Executives who act early on validated reuse programs, material strategy, and digital guarantees will convert structural market growth into durable competitive advantage.
For clients and partners requiring the segmented datasets, company-level benchmarking tables, and our interactive scenario model, please consult the full PW Consulting Isothermal Packaging Market report. The report contains the detailed regional, type, and application splits, supplier scorecards, and investment-case templates necessary to convert the strategic direction outlined here into concrete operational and M&A moves.
For detailed analysis of this topic, please visit the official page: Isothermal Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


