



Back Glue Market to Reach USD 252.4M by 2032 at 5.67% CAGR — PW Consulting

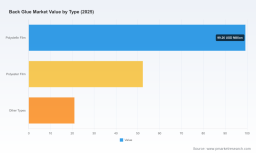
Back Glue Market 2026: Strategic Preview for Executive Decision-Making
As companies plan investments and product strategies for 2026, the Back Glue market presents a distinct mix of steady, technically-driven growth and accelerating strategic complexity. Our latest PW Consulting market study — built on a 2025 base year, a five-year historical window (2020–2025) and an explicit forecast through 2032 — shows a market trajectory that warrants deliberate, prioritized action now. The market expanded appreciably from 2020 to 2025 and is projected to continue growing at a compound annual growth rate (CAGR) of 5.67% through the forecast horizon. By 2032 the global market is expected to exceed the mid‑double‑hundred million USD mark, underscoring that back glue is no longer a commoditized footnote in construction and semiconductor value chains but a strategic enabler of product performance and regulatory compliance.
Back Glue Market
Why 2026 Is a Pivotal Year
Three converging forces make 2026 a decision inflection point for manufacturers, formulators, OEMs and institutional buyers:
Back Glue Market
- Technical differentiation matters: Advances in polymer emulsions, inorganic silicate composites and bio‑derived binders are raising the bar for adhesion performance, moisture resistance and thermal stability across tile, flooring and electronic applications.
- Regulation and sustainability are operational constraints: VOC limits, lifecycle disclosure requirements and seismic/environmental installation standards are reshaping acceptable formulations and supply chains.
- Buyer sophistication is increasing: Procurement leaders expect validated performance data, supplier risk analytics and tailored service models (formulation customization, installation training, after‑sales support).
For executives, the practical implication is clear: 2026 should be the year to convert market awareness into decisive portfolio and commercial moves. Delaying action risks margin erosion as higher‑performance, lower‑emissions alternatives cross price parity thresholds and as digital solutions begin to enable customized adhesives at scale.
Back Glue Market
Market Trajectory: From Stability to Strategic Opportunity
Our historical analysis (2020–2025) documents steady expansion and improving unit economics driven by increasing adoption in high‑value applications. The 5.67% CAGR embedded in our forecast to 2032 reflects a balance of ongoing demand from construction and electronics assembly against periodic raw material cyclicality and localized regulatory variation. By 2026 the market enters a phase where growth is less about volume alone and more about value capture — premium formulations, bundled system sales (adhesives + primers + training), and service differentiation.
Key implications:
- Revenue growth opportunities are increasingly concentrated in performance upgrades rather than basic replacement demand.
- Supply chain control over critical feedstocks — polymer emulsions and silicate composites — becomes a competitive advantage for margins and product reliability.
- Cost pass‑through ability will depend on demonstrable, certified benefits (e.g., VOC elimination, improved installation efficiency, reduced rework rates).
Competitive Landscape: Who’s Setting the Pace
The Back Glue sector remains fragmented enough to reward both scale and specialized innovation. Leading industrial and construction adhesive providers are pursuing multi‑pronged strategies: product launches, M&A to acquire niche capabilities, strategic partnerships for raw material innovation, and digital platforms to enable customization. Among the companies shaping the market:
- Henkel continues to leverage brand and formulation expertise, introducing removable construction adhesives and VOC‑free lines that address indoor air quality and sustainability demands.
- 3M deploys its broad industrial adhesive portfolio and materials science competency to support mounting and back‑glue solutions for both construction and industrial applications.
- Bostik (Arkema Group) is moving toward bio‑based chemistry partnerships to reduce reliance on fossil‑derived feedstocks while maintaining high performance in challenging installations.
- Sika is actively consolidating niche capabilities through acquisitions to broaden its portfolio of high‑performance adhesives and infrastructure‑grade formulations.
- Mapei has invested in digital platforms that enable AI‑driven customized formulations and compliance workflows, illustrating how software and materials science are converging.
- Laticrete and several regional specialists (notably players based in China) compete on application know‑how, local production scale and OEM supply relationships.
Recent corporate moves — product launches emphasizing removability and low VOCs, acquisitions to secure specialty chemistries, partnerships to develop bio‑based feedstocks, and AI platforms for formulation customization — collectively indicate the strategic playbook for 2026: combine materials innovation with regulatory alignment and commercial platforms that lower buyer switching costs.
Regulatory and Raw Material Dynamics
Material and regulatory dynamics are fast becoming primary determinants of competitive positioning. Two facts matter in 2026:
- Polymer emulsion and inorganic silicate composites remain the foundational feedstocks; control and diversification of these inputs help firms manage price volatility and ensure formulation consistency.
- Regulatory expectations — from indoor VOC standards to industry‑specific seismic and environmental compliance — are elevating the cost of non‑conformance. Successful suppliers now couple certified product attributes with installation guidance and documentation to simplify compliance for buyers.
Practically, this means R&D and procurement must be tightly linked: R&D defines acceptable alternative chemistries; procurement secures the upstream access and hedging strategies; and regulatory teams translate compliance into product claims and certifications that sales and channel partners can use.
What the PW Consulting Report Gives You (Operationally Actionable)
Our full report is designed as an executive toolkit for 2026 — not an academic exercise. Key, actionable deliverables include:
- Market sizing and validated growth scenarios by application class and type, rooted in field‑verified adoption rates and installation economics (base year 2025; forecast 2026–2032).
- Supply‑side intelligence: supplier scorecards, raw material exposure matrices, and cost‑scenario models that let procurement stress‑test supplier mixes under different price and regulatory shocks.
- Go‑to‑market playbooks: channel segmentation, margin maps, and service bundles that increase lifetime value (LTV) with installers, distributors and OEMs.
- Product strategy frameworks: prioritized R&D roadmaps, certification pathways (VOC, ISO, seismic compliance) and time‑to‑market estimates for formulation variants (bio‑based, VOC‑free, high‑temperature).
- M&A & partnership screening: an actionable target list and diligence checklist for acquiring specialty chemistries, digital capabilities or regional manufacturing footprints.
- Scenario planning templates and stress tests for three disruptive pathways: raw material price shocks, accelerated regulatory tightening, and digital customization adoption curves.
- KPIs and monitoring dashboards you can operationalize immediately to track share shifts across premium vs. commodity segments, margins by formulation family and channel conversion rates.
Note: In keeping with our “trailer” approach, the executive summary above outlines the strategic levers available. The full PW Consulting report contains the detailed segmentation tables, regional and application splits, supplier financial benchmarks and price sensitivity matrices needed to execute these levers; those granular datasets are available on the full report page.
Five Strategic Moves for 2026
Based on our integrated market, competitor and regulatory analysis, PW Consulting recommends five priority moves for firms that intend to lead in the 2026 back glue landscape:
- Lock in strategic feedstocks: Secure contracts and alternate supply routes for polymer emulsions and silicate composites with contingency clauses for regulatory shifts.
- Accelerate certified low‑emissions offerings: Fast‑track VOC‑free and bio‑derived lines paired with credible certification to enable premium pricing and specification inclusion.
- Invest in digital formulation platforms: Enable on‑demand customization and compliance documentation for large commercial accounts and OEMs to raise switching costs.
- Targeted M&A and partnerships: Acquire niche specialty adhesive makers, or form joint ventures with raw‑material innovators to keep cost curves favorable without sacrificing performance.
- Embed installer economics into value propositions: Sell system solutions (adhesive + primer + training) that demonstrably reduce installation time, rework and liability — metrics that procurement teams can quantify.
Final Considerations for Executive Teams
The Back Glue market in 2026 is characterized by measured growth at scale and rapid tactical shifts at the margins. The CAGR and market trajectory provide the macro permission to invest; the competitive and regulatory detail determines where those investments will pay off. Organizations that align procurement, R&D and go‑to‑market around validated performance claims and supply resilience will capture disproportionate value as the market matures.
PW Consulting’s full Back Glue Market report delivers the datasets, supplier dossiers and scenario tools you need to turn strategy into executed advantage. For teams prioritizing 2026 decisions — whether product launches, regional expansions, procurement renegotiations or M&A — the report provides the actionable intelligence to minimize risk and accelerate value realization. Access the full intelligence package to see the detailed segmentation, regional and application breakdowns, supplier financials and the precise scenario outputs that inform board‑level decisions.
For detailed analysis of this topic, please visit the official page: Back Glue Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


