



PW Consulting: DJ software market hits USD 155.8M in 2025, set for 5.25% CAGR

DJ Software Market 2026: Strategic Imperatives and Executive Briefing
As PW Consulting’s senior strategic advisor and lead industry analyst, I present a focused briefing designed to inform executive decisions in 2026. This piece distills the directional insights from our full DJ Software Market study — a comprehensive, data-driven resource that blends historical performance, technology trends, vendor dynamics, and scenario-based guidance. It is written to help C-suite and investment committees prioritize bets across product development, partnerships, M&A, and commercial models — while intentionally withholding granular segment tables to drive subscription-level engagement with the complete report.
DJ Software Market
Macro trajectory: what the numbers tell us
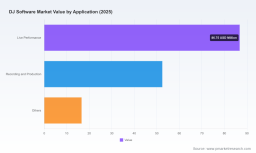
The DJ software market has moved from early digital adoption to a mature, innovation-driven phase. Our base-year analysis (2025) anchors the market at USD 155.75 Million (revenue, Million USD), following steady expansion from 2020. Between 2026 and 2032 we project the market to continue growing at a compound annual growth rate of roughly 5.25%, reaching an estimated USD 219.75 Million by 2032. This trajectory reflects a blend of steady professional demand, wider consumerization enabled by mobile and cloud platforms, and technology-led upsell — particularly via AI and streaming integrations.
DJ Software Market
For executives, two immediate takeaways emerge from these macro dynamics: (1) this is a growth market large enough to sustain multiple focused players, and (2) growth is increasingly driven by product differentiation rather than pure price competition. Those two facts reframe how you should invest in product, partnerships, and distribution in 2026.
DJ Software Market
Why 2026 is a strategic hinge year
-
Technology inflection: Real-time stem separation, AI-assisted harmonic mixing, and cross-device synchronization are shifting perceived product value from UI/feature checklists to creative augmentation and reliability under live conditions.
-
Platform convergence: Streaming integrations and broad hardware compatibility have created ecosystems where software choice influences hardware purchase and vice versa. Bundles and pre-installed suites are now powerful distribution levers.
-
Commercial sophistication: Subscription models, tiered feature access, and enterprise licensing for venues/events are maturing; monetization resilience is now as important as new-user acquisition.
Competitive landscape — positioning and strategic moves
Our competitive analysis covers both incumbents and emergent challengers. Each player occupies a distinct strategic space defined by product architecture, ecosystem ties, and go-to-market motion. Below are high-level, decision-oriented profiles that emphasize positioning (not market share minutiae):
-
Serato Limited (Auckland) — Serato DJ Pro is the professional stalwart, prized for stability, studio-to-stage fidelity, and streaming integrations. Its recent release cycle has focused on broad hardware backward-compatibility, reinforcing Serato’s relationship with legacy professional setups. Strategic implication: Serato remains a prime target for partnerships around backward compatibility and for enterprises that require predictable, proven performance in live events.
-
Algoriddim GmbH (Munich) — With djay Pro, Algoriddim competes on cross-platform reach and AI-driven features. Their strength is accessibility paired with real-time effects and an intuitive UX that accelerates adoption among both enthusiasts and mobile-first performers. Strategic implication: Algoriddim is well positioned for volume growth and OEM/consumer bundling; competitors must match AI/UX capabilities to remain relevant in consumer segments.
-
Native Instruments (Berlin) — Traktor continues to bridge production and performance workflows. Native Instruments’ advantage is deep integration with production ecosystems, which makes it attractive to hybrid creators who move fluidly between studio and stage. Strategic implication: Partnerships or product extensions that connect DAW workflows to live DJing can unlock cross-sell opportunities.
-
AlphaTheta Corporation (Japan) — The Rekordbox ecosystem exemplifies the hardware-software bundle strategy: tight CDJ/mixer compatibility plus event and library tools. Recent product updates (next-gen mixers and firmware enhancements) and an acquisition that strengthens KUVO-related capabilities signal a consolidation play toward owning more of the live ecosystem stack. Strategic implication: Expect increased platform lock-in; competing vendors will need compensating differentiators, such as open integrations or superior cloud services.
-
inMusic Brands (US) — The Engine DJ ecosystem centers on consistent desktop tools and controller support, often linked to hardware brands within the group. Strategic implication: an attractive partner for hardware manufacturers that seek integrated, branded software experiences.
-
Atomix Productions / VirtualDJ (Dubai) — VirtualDJ’s longevity and feature breadth makes it a go-to for DJs who value library scale and extensibility. Strategic implication: VirtualDJ is a critical competitor for aggregated library and streaming capabilities.
-
DJ.Studio (Netherlands) — An emergent, AI-first contender with advanced stem separation and timeline editing aimed at mashup and radio workflows. Strategic implication: an acquisition target for incumbents seeking to accelerate AI competence.
-
Mixvibes (Paris) — Cross DJ competes on cross-platform real-time stem separation and effects; a niche innovator with strong European roots. Strategic implication: tactical partnerships in regional markets or licensing deals for algorithmic IP are viable plays.
Recent industry moves and their strategic meanings
-
AlphaTheta’s product refreshes and a KUVO-related acquisition signal a push to own more of the live-event telemetry and social sharing stack. This strengthens hardware-software lock-in and creates opportunities for data-driven services (analytics, fan engagement).
-
Serato’s continued updates to support legacy Pioneer mixers reflect the persistent value of backward compatibility in the professional segment — a reminder that modernization must coexist with legacy support strategies.
-
Across the sector, investments in AI features, streaming partnerships, and cross-platform support (including mobile and emerging AR/VR devices) are the dominant R&D themes — not surprising, but vital when prioritizing product roadmaps.
Key demand drivers and operational constraints
-
AI and creative augmentation: Demand is now as much about creative enablement (automix, stems, harmonic suggestions) as it is about library access.
-
Streaming and licensing: Deep integrations with major streaming services broaden library choice but introduce licensing complexity and revenue-share trade-offs.
-
Hardware dependency: Professional use-cases require high-performance compute. DJs increasingly expect software that performs reliably with high track counts and low-latency stem processing — raising QA, minimum specs, and support cost considerations.
-
Cross-platform reach: macOS, Windows, iOS/Android — and nascent Vision Pro support — create additional development and testing burdens, but also new distribution vectors.
Strategic recommendations for 2026 decision-makers
Use these action-oriented levers to convert market growth into durable competitive advantage:
-
Prioritize AI capability, but treat it as a feature suite, not a product : Invest in robust, low-latency stem separation and AI-assisted workflows, but embed these features into broader artist workflows and UX that reduce cognitive load during live sets.
-
Make hardware partnerships non-negotiable : Negotiate deeper bundle economics with controller/mixer OEMs and pursue firmware-level integrations where possible. The winners will be those who offer seamless out-of-the-box experiences.
-
Design subscription tiers aligned to use-case economics : Offer clear, role-based plans (e.g., hobbyist, pro, venue/enterprise) and create add-ons for library streaming and cloud sync. Scenario-model multiple churn/ARPU outcomes before locking into a pricing architecture.
-
Pursue targeted M&A for missing capabilities : Focus acquisitions on AI audio startups, cloud streaming middleware, and real-time analytics. Smaller bolt-ons can accelerate roadmaps and defensible IP positions.
-
Operationalize cross-platform QA : Establish device labs and event-runway testing for low-latency environments; invest in remote telemetry to detect performance regressions under real-world loads.
-
Build adjacent services : Explore vendor-managed library migration, event licensing suites, and analytics-as-a-service for venues and promoters to diversify revenue and lock customers into the ecosystem.
What the full PW Consulting report delivers (practical, non-generic content)
-
Transparent market sizing methodology and validated historical series spanning 2020–2025, plus scenario-based forecasts through 2032.
-
Technology adoption maps and performance benchmarks for AI features, latency, and cross-platform compatibility requirements.
-
Vendor scorecards with strategic SWOTs, partnership matrices, and M&A targets prioritized by impact and integration risk.
-
Commercial levers playbook: pricing simulations, channel economics, OEM bundling templates, and enterprise licensing drafting guidance.
-
Operational readiness checklist and an event-runway test plan that product and QA teams can implement immediately.
-
Executive-ready scenario models (Bull / Base / Bear) that let boards stress-test revenue and margin implications before committing capital.
Risk matrix — what keeps executives awake
-
Licensing & royalty volatility tied to streaming partners.
-
Platform lock-in by dominant hardware vendors that can tilt distribution economics.
-
Performance regressions under live conditions that can damage brand trust quickly.
-
Regulatory or rights-management changes impacting sample-based workflows and streaming availability.
Final note — how to use this briefing in your 2026 plan
Treat 2026 as a year to convert technological capability into commercial defensibility. This means accelerating select AI investments, solidifying hardware alliances, and diversifying monetization beyond single-seat licenses. For boards and investors, the tactical questions are: where do you want to sit on the value chain (software platform, hardware-integrated ecosystem, or service-led operator), and what is your preferred pace for inorganic capability acquisition?
Our full DJ Software Market report contains the granular segmentation, pricing scenarios, vendor scorecards, and downloadable models that will allow you to translate this strategy into budgets and KPIs. To access the complete dataset, methodology notes, and the operational playbooks referenced above, please visit the PW Consulting report portal.
For detailed analysis of this topic, please visit the official page: DJ Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


