



PW Consulting: Luncheon Meat Market to Reach USD 276.5M by 2032 at 5.8% CAGR

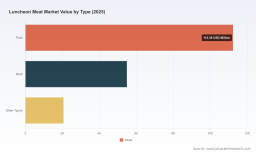
Luncheon Meat Market 2026: Strategic Imperatives from PW Consulting’s Market Intelligence
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present an executive introduction to our Luncheon Meat Market study — a decision-grade intelligence product crafted to inform 2026 corporate strategy, portfolio prioritization, and M&A screening. The research uses 2025 as its base year, traces historical performance across 2020–2025, and projects the market through a seven‑year forecast window (2026–2032). The headline: the global luncheon meat market is a resilient, mid-growth category with a compound annual growth rate (CAGR) of 5.8% across our forecast horizon (USD, Revenue unit: Million). Our analysis is deliberately deep in causation and implication; core subsegment figures and granular splits are reserved for the full report to preserve competitive value and to invite a targeted read of the source study.
Luncheon Meat Market
Why this study matters for 2026 decision-makers
-
Macro predictability with tactical volatility: While the market trajectory shows steady expansion from the mid‑six‑figure range in 2025 into higher levels through 2032 under a 5.8% CAGR, short‑term operating conditions in 2026 will be shaped by input cost swings, safety events, and evolving consumer preferences. Executives who align near‑term operations to the longer‑term demand envelope will preserve margins and optionality.
Luncheon Meat Market -
Margin and volume playbooks diverge: Large-scale producers and retailers can exploit scale to manage raw‑material cycles and ensure distribution, while agile premium and niche players can extract margin via formulation, provenance, and convenience innovations. Our study maps strategic choices against quantified outcomes to inform channel and SKU rationalization decisions.
Luncheon Meat Market -
Regulatory and food‑safety events materially change risk profiles: The market’s concentrated core (CR3 ~45%, CR5 ~56%) means that recalls or alerts involving any sizable supplier can propagate to category demand and trading dynamics. Our risk scenarios model the financial and operational impact of such events and the mitigants that buy time and credibility.
Market trajectory and structural context
Our topline sizing shows the category’s recovery and expansion path through the base year and into the forecast window. The market expanded consistently between 2020 and 2025 and, under steady demand and product innovation, is projected to continue growing across 2026–2032 under a 5.8% CAGR. This pace reflects a balance between persistent consumer demand for convenience proteins and headwinds from higher‑value protein competition, cost pressure on raw materials, and intermittent food‑safety episodes that periodically reset shopper behavior.
From a structural perspective, the category is neither a commodity pure play nor a niche artisanal market. It is a hybrid: scale favors lower‑cost producers and private‑label suppliers, while premiumization and health‑oriented product innovation create profitable niches. The concentration metrics (CR3 and CR5) confirm that several global players exert significant influence on pricing, retail negotiations, and supply security — a dynamic that informs both defensive playbooks (inventory and supply redundancy) and offensive options (brand differentiation and exclusive formats).
Key demand and supply drivers in 2026
-
Consumer trends: Convenience, snacking occasions, and format innovation continue to drive demand. Health and label clarity (reduced sodium, “no nitrates added,” clean‑label recipes) are critical for new product acceptance. Premium deli positioning and limited‑edition flavors generate disproportionate attention and trial.
-
Raw‑material cycles: USDA data through early 2026 indicate divergent supply signals for primary inputs — pork production is forecast higher in 2026 relative to prior year, putting mild downward pressure on hog prices, whereas beef production is forecast lower, supporting elevated cattle prices. These divergent trajectories require differentiated hedging and category pricing strategies per protein type.
-
Food safety and regulation: Recent recalls and public health alerts highlight downside tail risk from contamination or mislabeling. Even isolated events can reshape retailer stocking decisions and consumer trust for a category, particularly in regions with strong cold‑chain dependence.
-
Channel dynamics: Brick‑and‑mortar channels remain primary volume drivers, but online and direct‑to‑consumer formats are accelerating innovation in packaging, multipack formats, and subscription models. Retailer assortment optimization (fewer SKUs, higher rotation) favors SKUs that deliver higher sales velocity or margin per square foot.
Competitive landscape: strategic positions and near‑term plays
Our competitive synthesis concentrates on the firms that shape pricing, innovation cadence, and distribution. Below, I summarize strategic posture and implications for competitors, customers, and potential entrants. Full competitive scorecards, capability matrices, and scenario models are contained in the full report.
-
Hormel Foods Corporation — Strength: iconic heritage brands and a broad pork‑led portfolio that includes lower‑sodium and lite variants. Strategic implication: Hormel leverages brand equity and scale to pursue incremental premiumization while defending core value segments. For competitors, the counterplay is targeted differentiation on provenance and health attributes where scale is less decisive.
-
Tyson Foods, Inc. — Strength: diversified protein supply chains and rapid NPD cadence in sandwich‑style lunch meats. Recent flavor launches (e.g., bold sandwich style variants) illustrate a playbook focused on occasion expansion and flavor innovation to drive frequency. Retail partners should evaluate co‑development opportunities to accelerate exclusivity and shelf differentiation.
-
JBS USA Holdings, LLC — Strength: end‑to‑end scale across beef, pork, and poultry. Strategic implication: JBS’s scale underpins competitive pricing and private‑label wins; challengers must focus on agility, product story, and channel intimacy to compete effectively.
-
Cargill, Incorporated — Strength: supply‑chain integration and bulk/pre‑sliced solutions for retail and foodservice. Strategic implication: Cargill is a counterparty of choice for retailers seeking supply continuity and custom formulations; branded players must invest in consumer marketing to defend shelf space.
-
Boar’s Head Provisions Co. — Strength: premium deli positioning and craftsmanship narrative. Strategic implication: premium players can extend margin by leveraging foodservice partnerships and premium retail placements; the challenge is scaling without diluting brand authenticity.
-
Kraft Heinz Company — Strength: powerful legacy brands and broad distribution through Oscar Mayer and related lines. Strategic implication: brand reach supports rapid new‑product rollouts; smaller competitors can win niche loyalty through sharper positioning on health and provenance.
-
Deli Brands of America & Farmland Foods — Strength: specialized product portfolios and retailer relationships focused on traditional sliced deli and lunch meats. Strategic implication: these firms excel in meeting retailer assortment needs; broader competitors must balance SKU rationalization against localized consumer tastes.
Recent events that recalibrate 2026 strategy
-
Product innovation continues to be a high‑impact lever: flavor innovation and sandwich‑ready formats (notably launches in 2025–2026 by major brands) are proving effective at increasing basket penetration and frequency.
-
Food safety and labeling incidents remain an acute operational risk: recalls and public health alerts in the recent period underscore the need for rigorous supplier governance, traceability, and rapid crisis‑communications playbooks. Retailers and manufacturers with transparent traceability systems have a measurable brand‑value advantage in post‑event recovery.
-
Input volatility requires active risk management: USDA forecasts for 2026 show asymmetric supply movements across pork and beef that will alter input cost curves. Firms should update procurement hedging, contract structures, and pricing cadence in light of the new supply outlook.
What the PW Consulting report delivers (operational highlights)
The full Luncheon Meat Market study is intentionally structured to move leaders from insight to action. Key deliverables include:
-
A validated market model: topline historicals (2020–2025) and a scenario‑based forecast (2026–2032) with sensitivity levers tied to raw‑material price bands and structural demand shifts.
-
Commercial playbooks: SKU rationalization templates, retail assortment decision trees, and pricing elasticity matrices to quantify the profit impact of format and label changes.
-
Competitive scorecards: capability assessments, product mapping, and go‑to‑market gap analyses for the leading global players — enabling rapid benchmarking and partner selection.
-
Supply‑chain & risk toolkit: supplier risk heatmaps, recall preparedness checklists, and traceability investment ROIs that help prioritize capital allocation for resilience.
-
M&A and portfolio scenarios: thematic targets, concentration safeguards, and accretion/dilution modeling for roll‑up and capability acquisition strategies.
-
Implementation roadmap: 90‑, 180‑, and 365‑day action plans aligned to capability gaps, with measurable KPIs that link operational changes to margin and volume outcomes.
How to use this intelligence in 2026
-
Prioritize quick wins that reduce exposure to input swings (e.g., targeted hedges, alternate protein mixes, and contractual indexation) while investing in the consumer propositions that sustain premium margins.
-
Accelerate product and channel experiments (limited‑edition flavors, sandwich‑ready formats, DTC pilots) with rapid learning loops; our playbooks show which experiments scale and which dilute margins.
-
Strengthen supplier governance and traceability now — the cost of inaction after a recall is disproportionately higher than proactive investment in cold‑chain audits and labeling assurance.
-
Use concentration dynamics to your advantage — scale actors should lock distribution and capacity, while mid‑sized and niche players should carve defensible positions around brand authenticity, health claims, and retail partnerships.
PW Consulting’s Luncheon Meat Market study is crafted to support CEO, CFO, and Head of Commercial decisions for 2026 and beyond. The executive summary and methodological notes are public; proprietary segment matrices, company scorecards, and downloadable datasets are available in the full report. For access to the complete dataset, scenario models, and a tailored briefing aligned to your strategic questions, please visit the full report page or contact PW Consulting directly.
For detailed analysis of this topic, please visit the official page: Luncheon Meat Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


