



PW Consulting: Button Cell Market Poised for 6.5% CAGR Through 2032

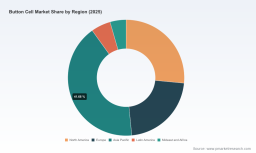
Button Cell Market 2026: Strategic Preview for Decision‑Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused preview of our Button Cell Market research — a practical intelligence brief crafted for executives who must make high‑stakes decisions in 2026. This preview synthesizes the macro trajectory, structural dynamics, regulatory inflection points, and competitor archetypes that will shape supplier strategies, procurement plans, and M&A activity over the coming cycle. It intentionally showcases analytical depth while preserving the granular segment tables and model outputs for subscribers — think of this as the trailer that proves the film is worth seeing.
Button Cell Market
Why this market matters in 2026
The global button cell market is no longer a niche industrial input — it is a foundational component for a wide range of miniaturized electronics across medical, consumer, industrial and automotive applications. Between the start of the historical baseline (2020) and our base year (2025), the market expanded steadily, rising from approximately USD 3.4 billion to about USD 4.55 billion. From 2026 through 2032 we model a continued compound annual growth rate (CAGR) of 6.5%, culminating in a market value that reaches roughly USD 7.0 billion by 2032. That pace of growth, combined with concentrated supply chains and regulatory pressures, creates both opportunity and operational risk for manufacturers, OEMs and investors.
Button Cell Market
Key demand drivers and structural dynamics
- Miniaturization and functionality creep: As devices demand more features per unit volume (sensors, connectivity, secure elements), button cells are increasingly viewed as enablers for product differentiation. This is especially true in medical wearables and certain consumer IoT endpoints.
- Medical and safety‑critical adoption: Growing use in implantables, monitoring devices and hearing aids raises the bar for reliability, certification and traceability. Buyers are paying a premium for validated supply chains and documented qualification processes.
- Portfolio bifurcation: The market is bifurcating between commoditized commodity formats and engineered, application‑specific variants that command margins and locked‑in design wins. Strategy choices here determine whether a firm competes on cost or on integrated solutions.
- Supply chain tightness and lead times: Our sector analysis shows lead times for standard lithium coin cell formats can range between 8 and 16 weeks, with raw material cost volatility — particularly lithium and manganese dioxide — impacting procurement cycles and hedging strategies.
Regulatory and logistics inflection points
- Transport classifications and handling: The IATA 2026 Battery Guidance Document introduced updated classification pathways for lithium and sodium‑ion batteries, including button cell types. Manufacturers and shippers must revisit their logistics playbooks to avoid delays and compliance failures.
- Safety and product standards: Enforcement of ANSI/UL 4200A‑2023 for button cell and coin battery systems (effective enforcement since March 19, 2024) is already reshaping product verification protocols. For 2026 purchasers and product managers, proof of compliance will increasingly become a prerequisite for qualification.
- Operational implications: Certification timelines, test lab capacity and documentation requirements now feature in time‑to‑market calculations. Firms that internalize these non‑negotiables into R&D and procurement roadmaps reduce program risk and preserve launch windows.
Supply side and competitive archetypes
The competitive field comprises long‑established global brands, regionally strong manufacturers, and agile private players that specialize in niche medical or military segments. Market concentration metrics indicate material clustering at the top end of the market: the top three firms account for roughly a third of global supply, and the top five for under half — enough concentration to influence pricing dynamics, but not so consolidated that new entrants or scale‑fast followers cannot disrupt.
Button Cell Market
- Major multinational incumbents: Firms such as Energizer, Duracell, Panasonic Energy, Sony, and Renata deploy global channels, deep R&D reservoirs and broad brand equity. Their strength is in scale, regulatory capability, and end‑market relationships (e.g., watch, automotive key‑fob, consumer electronics OEMs).
- Japanese precision specialists: Seiko Instruments, Toshiba Battery, Maxell (recently the recipient of a transferred micro battery business), and others compete on high‑reliability, small‑form‑factor cells for timing, medical and precision applications. They bring very high product and process discipline, which is attractive for regulated medical designs.
- Chinese manufacturers and OEM suppliers: EVE Energy, PKCELL, Omnergy, Vtery, Great Power Energy and peers combine cost competitiveness with rapid scale‑up capabilities. Several also target design wins in consumer electronics and lab equipment where speed and price matter most.
- Specialists and solutions providers: ZEUS Battery Products (US) and a number of smaller US and European outfits emphasize customization — tailored chemistries, packaging and qualification for military, medical and industrial customers. Their go‑to‑market is built around co‑engineering and performance guarantees.
Notably, the March 2026 transfer of a major Japanese micro battery business changes supplier maps for specific medical and hearing‑aid niches. Buyers and investors should evaluate how this reallocation of IP and production capacity alters qualification roadmaps and competitive dynamics in those subsegments.
Risk map: what to watch in 2026
- Certification bottlenecks: Growing demand for UL and sector‑specific approvals is colliding with finite third‑party test capacity; programs that ignore this timing risk face delayed launches.
- Raw material swings: Lithium and manganese dioxide price and availability remain the foremost near‑term cost variables; procurement teams must add layered hedges and dual‑sourcing where practicable.
- Logistics compliance risk: Updated IATA classification and packaging requirements mean cross‑border shipments require more documentation and pre‑approval — unexpected noncompliance disrupts product flows.
- Concentration leverage: With top suppliers holding meaningful share, strategic buyers should evaluate lock‑in risk and design for supply flexibility (alternative formats, redesign windows, or multi‑vendor sourcing).
Strategic implications for 2026 decision‑makers
For executives calibrating 2026 strategy, four practical implications should guide choices:
- Prioritize qualification lead time as a KPI: When choosing a supplier or planning product launches, the calendar for certification and logistical approvals must be treated as a hard constraint equal to unit cost.
- Differentiate between commodity and engineered plays: Decide whether your firm competes on unit economics (price, scale) or on integrated solutions (custom chemistries, extended life, safety traceability). Each path requires different capex, R&D focus and channel strategies.
- Design for supply redundancy: Given lead‑time volatility and material swings, modularizing designs to accept multiple coin cell formats or alternative chemistries reduces program fragility.
- Use M&A and partnerships tactically: Small, targeted acquisitions (IP, niche manufacturing assets, or test labs) can accelerate time to compliance and protect margin in medical and safety‑critical segments.
What our full report delivers (operationally focused)
The full PW Consulting Button Cell Market report is designed to be immediately actionable for procurement, product and corporate strategy teams. Highlights include:
- Forward‑looking market model (2026–2032) with scenario toggles and sensitivity analysis so you can stress test volume, price and raw material paths;
- Detailed supplier scorecards and a procurement playbook that ranks vendors on quality systems, regulatory readiness, geographic risk and scalability;
- Regulatory compliance matrix with timelines and a practical gap‑remediation checklist for ANSI/UL and IATA updates;
- Cost build‑up templates and margin desks for different chemistries and cell formats, enabling competitive pricing benchmarks;
- Market concentration and competitive positioning maps, plus a prioritized M&A heatmap and integration checklists;
- Supply chain resilience toolkit: dual‑sourcing strategies, inventory policy simulations, and lead‑time hedging frameworks;
- Executive decision aids: board‑ready one‑page strategy briefs, supplier negotiation playbooks, and a capital allocation decision matrix.
We intentionally withhold core subsegment tables and granular region‑by‑application breakdowns from this preview. Those granular splits are embedded in the interactive model included in the full report and are essential for investment memos, supplier scorecards and product‑level margin planning.
How to use this intelligence in 2026
- If you are a product manager launching a regulated device in 2026 — incorporate UL compliance and transport classification milestones into your Gantt, and lock supplier audits early.
- If you lead procurement — focus immediately on establishing parallel supply options for critical cell formats and negotiate clauses for raw material pass‑through and lead‑time commitments.
- If you are an investor or corporate development leader — target tuck‑ins that provide regulatory test capacity, niche medical production lines, or IP that accelerates certification.
Next steps
PW Consulting’s full Button Cell Market study provides the granular segmentation, revenue tables, vendor profiles and the Excel model needed to operationalize the strategies outlined here. If your 2026 decisions hinge on supplier selection, product timing, or capital commitments in this space, request the full report and model to move from strategic intent to executable plans.
For direct access to the report, data exports and a tailored briefing that maps the findings to your portfolio, contact PW Consulting’s market intelligence desk. The macro signals are clear; the local operating decisions will determine who captures the margin premium as the market scales toward 2032.
For detailed analysis of this topic, please visit the official page: Button Cell Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


