



PW Consulting: Tractor Market Set to Expand at a 5.8% CAGR Through 2032

Tractor Market 2026 Strategic Outlook — Why PW Consulting’s Research Is Mission-Critical for Your Next Move
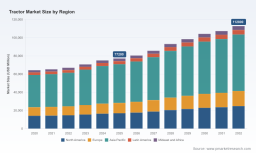
The tractor industry stands at a strategic inflection point. After a steady recovery through the early 2020s, the global tractor market reached an estimated USD 77,200 million in our 2025 base year and is projected to expand at a compound annual growth rate (CAGR) of 5.8% across our 2026–2032 forecast window, reaching roughly USD 112,800 million by 2032. Those headline numbers tell a simple story of scale and momentum; the real strategic value for executives lies in the granular dynamics — demand shocks, input-cost pressure, regulatory shifts, and technology adoption curves — that will determine who captures tomorrow’s value.
Tractor Market
Why this study matters for decisions made in 2026
-
Capital allocation under uncertainty — The report translates high-level growth into investment priorities. We map product-level returns across propulsion mixes (diesel, electric, hybrid), horsepower tiers, and use cases, allowing capital planners to compare near-term ROI versus strategic positioning for 2030+ demand profiles.
Tractor Market -
Go-to-market and network optimization — Dealers, distributors and OEMs will need to rebalance inventory, service capability and training for electrified and high-horsepower lines. The study provides playbooks to right-size dealer footprints and service-skill matrices aligned to regional demand patterns.
Tractor Market -
Supply-chain resilience and sourcing strategy — With raw-material and tariff volatility persisting, procurement leaders can use our scenario-based cost models to stress-test supplier contracts, hedge strategies and nearshoring options that preserve gross margins without sacrificing time-to-market.
-
M&A and partnership targeting — For strategic buyers and PE sponsors, the study surfaces the capability gaps that justify bolt-on versus transformational deals, and prioritizes target archetypes by strategic fit and valuation sensitivity.
-
Regulatory and trade compliance planning — OEMs face tightening emission standards and evolving testing codes. The research converts regulatory trajectories into product compliance roadmaps and market-entry constraints, which are essential to plan certification timelines and capex.
What’s inside the report — practical, useable modules
-
Transparent market sizing and forecast methodology — Historical series (2020–2025), a clearly articulated base year (2025) and scenario-based forecasts to 2032. We disclose model assumptions, sensitivity levers and confidence intervals so users can re-run outcomes under alternative macroeconomic or commodity inputs.
-
Demand-driver analysis and scenarios — Deep dives on drivers such as mechanization trends, commodity prices, farm consolidation, infrastructure investment and climate adaptation. Each driver is scored for directional impact and timing to support strategic timing decisions.
-
Granular segmentation — Multi-dimensional segmentation across region, application, horsepower bands, drive-type and propulsion. Note: this summary highlights structure and trends; the full report contains the proprietary segmentation tables and time-series datasets necessary for transaction and operating decisions.
-
Competitive playbooks and company scorecards — Benchmarked operating models, product roadmaps, R&D pipelines, go-to-market strengths and weaknesses for leading OEMs. Proprietary scoring weights strategic importance to help identify where competitors are vulnerable or dominant.
-
Supply-chain mapping and margin impact analysis — Bill-of-material concentration, supplier risk heatmaps, and tariff/commodity sensitivity models tailored to tractor manufacturing footprints.
-
Regulation & standards intelligence — A practical guide to emission requirements, testing certification and trade compliance implications for export strategies and product homologation schedules.
-
Commercial playbooks — Pricing strategy under cost-pressure, service-led revenue models, fleet-leasing and subscription frameworks that improve lifetime customer economics.
-
Financial toolkits — Discounted cash flow templates, valuation comparables and M&A due-diligence checklists calibrated to tractor-specific dynamics.
Competitive landscape — what the largest OEMs are placing their bets on
-
John Deere (Moline, IL) — Continues to push the envelope on high-horsepower capability and integrated precision systems. Recent product activity has reinforced their leadership posture in advanced powertrain and high-horsepower segments. The brand’s scale and integrated services create both margin advantage and higher R&D amortization, but exposure to commodity and tariff-driven input-costs remains a material operating risk.
-
CNH Industrial (Amsterdam) — CNH’s Case IH and New Holland portfolios emphasize operator comfort and efficiency. Recent model introductions underscore a strategy of steady platform evolution and dealer experience upgrades to protect share in mature markets.
-
AGCO Corporation (Atlanta, GA) — AGCO is accelerating electrification efforts while leveraging established brands (including Fendt) to commercialize battery-powered solutions. Early mover activity in compact electric tracors signals a dual-track approach: defend traditional powertrains while incubating low-emission offerings.
-
Kubota Corporation (Osaka) — Market-leading in compact and utility segments, Kubota’s advantage lies in small-farm optimization and high-density dealer networks. Their product mixes are engineered for precision-agriculture integration on smaller acreage footprints.
-
Mahindra & Mahindra (Mumbai) — Mahindra’s global reach and lightweight 4WD models are tailored to both domestic and export demand. Competitive pricing and localized supply chains underpin their volume-oriented strategy in price-sensitive markets.
-
Escorts Kubota (Gurgaon) — Focused on compact utility applications with product features tuned to local implement compatibility. Their strategy emphasizes local engineering, aftermarket integration and cost-competitive production.
Collectively, the market shows notable concentration among the top OEMs (top-three and top-five concentration metrics point to a market where a small set of global incumbents capture a majority of revenue), but sizeable opportunity pockets remain for niche players and new entrants that can deliver differentiated technology or localized value propositions.
Key industry dynamics to watch in 2026
-
Input-cost volatility and tariff impacts — Elevated steel and aluminum cost exposure and trade-policy instruments are increasing manufacturing cost baselines. Manufacturers and suppliers must assume partial cost pass-through to end-users while exploring material substitution and supply-chain reconfiguration.
-
Regulatory acceleration toward low-emission powertrains — Tightening emission standards for off-road engines and more stringent state-level requirements are shortening the window for transition, driving capital into electrification and aftertreatment technologies.
-
Standards and export compliance — International testing codes and homologation requirements are raising the bar for cross-border product sales; firms must budget time and certification spend into product launch timelines.
-
Electrification and autonomy trajectories — Two parallel trends dominate: electrification of low- and mid-power segments (driven by regulation and operational cost advantages) and increased automation/integration across horsepower tiers to support labor-constrained farming regions.
How executives should translate the report into action in 2026
-
Prioritize product investments by expected margin uplift and regulatory urgency. Use our scenario outputs to sequence electrification and high-horsepower investments to optimize payback periods.
-
Rework procurement strategies now. Hedge material exposure, accelerate dual-sourcing for critical inputs and evaluate nearshoring for high-risk components to contain lead-time and cost shocks.
-
Reconfigure dealer and service networks to support new powertrains and telematics-enabled service models. Training and spare-parts strategies will define aftermarket economics as EV fleets grow.
-
Treat regulation as a product-development input. Advance certification timelines, and organize cross-functional squads to translate emission and safety standards into requirements for engineering, QA and supply chain.
-
Adopt a portfolio approach to M&A: protect market share through bolt-ons that expand service and digital capabilities, but consider transformational buys where internal development is too slow or capital intensive.
Concluding note — what this “trailer” reveals and what it withholds
This executive briefing highlights why the tractor market’s growth trajectory and structural shifts make 2026 a pivotal year for strategic repositioning. We have surfaced the growth baseline, the fundamental forces at work, and a tactical menu of responses that leaders must consider this year. To preserve the tactical advantage for our clients, detailed segmentation tables, time-series datasets, company scorecards with granular KPIs, and our proprietary financial models are reserved for the full report and accompanying data deliverables.
To access the complete market models, downloadable datasets and the actionable playbooks that underpin these conclusions, please visit the PW Consulting Tractor Market report page or contact your PW Consulting representative. Senior teams using the full suite will gain the specific directional inputs and ready-to-run tools required to convert market growth into sustainable competitive advantage in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Tractor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


