



PW Consulting: Forged Alloy Aluminum Wheel Market - USD 3,050M in 2025 (6.11% CAGR)

Forged Alloy Aluminum Wheel Market: Strategic Outlook for 2026 Decision-Making
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise, practice-oriented introduction to our full Forged Alloy Aluminum Wheel Market study. This briefing articulates the strategic imperatives that corporate leaders, OEM procurement teams, private equity investors, and operations heads must weigh as they set priorities in 2026. It is structured to demonstrate the analytical depth of our work while preserving the detailed proprietary segmentation that we reserve for the full report.
Forged Alloy Aluminum Wheel Market
Why this study matters for 2026
-
Macro momentum: After a recovery phase across 2020–2025, the forged alloy aluminum wheel market has reached an estimated USD 3,050 Million in the base year 2025, and our forecast models indicate continued expansion to roughly USD 4,605 Million by 2032 at a compound annual growth rate (CAGR) of approximately 6.11% (forecast period 2026–2032). These headline metrics frame a market that is sizable, investable, and structurally shifting.
Forged Alloy Aluminum Wheel Market -
Decision time horizon: 2026 will be the pivot year for many strategic moves—greenfield capacity choices, sourcing re-shoring, tariff mitigation strategies, and product roadmap shifts—because near-term supply and cost dynamics will materially affect medium-term margins and competitive positioning.
Forged Alloy Aluminum Wheel Market -
Consolidation and concentration: The topology of supplier concentration signals both opportunity and risk. The market shows a moderately concentrated supplier base (with the top-three and top-five players accounting for material shares of the market), which drives differentiated pricing power and creates both barriers and levers for newer entrants and tier-two suppliers.
Core drivers and structural dynamics
-
Premiumization and vehicle architecture: Weight reduction, fuel efficiency, and EV-range optimization continue to push OEMs toward lightweight forged solutions where acceptable on cost and certification grounds. Design-led differentiation—performance alloys, bespoke finishes, and integrated wheel systems—remains a competitive frontier.
-
Cost and supply volatility: Forged production carries materially higher unit costs versus cast or steel alternatives due to specialized machinery, premium aluminum blanks, and precision finishing. In early 2026, aluminum ingot prices spiked to multi-year highs following supply risks tied to geopolitical tensions in the Middle East, further compressing margins for manufacturers and downstream buyers alike.
-
Regulatory and market access considerations: Elevated trade policy risk reshapes sourcing strategies. Notably, recent tariff actions increased duties on aluminum derivatives in certain jurisdictions, and compliance regimes (ECE, DOT, and equivalent national standards) impose certification timelines that must be managed as part of product launches and cross-border supply strategies.
-
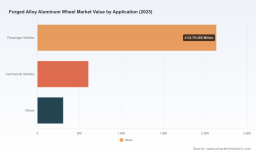
Application mix and OEM procurement cycles: Passenger vehicle premium segments and performance-focused light commercial use cases are the primary demand anchors for forged wheels. However, increasing productization tailored to heavier commercial vehicle applications is emerging as a strategic growth vector for suppliers seeking scale and diversified orderbooks.
Competitive landscape — what to watch in 2026
Our competitive analysis profiles incumbent global and regional leaders, assessing relative strengths across manufacturing footprint, technology, customer relationships, and product portfolios. Key firms covered include Superior Industries, CITIC Dicastal, Enkei Corporation, Maxion Wheels, Ronal Group, Alcoa Wheels, Borbet, and Topy Group.
-
Superior Industries (United States): Well entrenched with aluminum wheel portfolios targeted at passenger vehicle OEMs. Strengths include established OEM contracts and integration capabilities within aluminum system offerings.
-
CITIC Dicastal (China): A major cost-competitive producer with scale across passenger and commercial vehicle applications, leveraging vertical integration and proximity to key Asian supply chains.
-
Enkei Corporation (Japan): Technologically advanced in alloy design and performance-oriented wheel solutions, with a strong brand association in premium and motorsport-derived segments.
-
Maxion Wheels (Brazil): Noteworthy for expanding into forged commercial vehicle wheels. A near-term production launch at a new Manisa, Türkiye facility sets a strategic benchmark for capacity scaling and near-market manufacturing for regional demand.
-
Ronal Group (Switzerland): Specializes in high-end passenger and light commercial applications, with capabilities in customized finishes and engineering services.
-
Alcoa Wheels (United States): Positions forged products within broader aluminum wheel systems and leverages deep OEM relationships, especially where integrated weight-reduction solutions are pursued.
-
Borbet (Belgium): Focused on passenger and light truck markets with European manufacturing strengths and responsiveness to regional certification demands.
-
Topy Group (Japan): Entering 2026 with new commercial vehicle alloy lines and a branded product push, combining steel wheel expertise with a differentiated paint/process technology to address durability and aesthetics in heavier applications.
Recent tactical moves underscore two strategic themes: (1) capacity and capability expansion in commercial vehicle applications (e.g., greenfield launches targeting truck wheels), and (2) product platform differentiation via coatings, finishes, and alloy innovations. These moves are essential to monitor when assessing supplier selection, JV partners, or acquisition targets in 2026.
What the full PW Consulting report delivers (practical contents)
-
Robust market sizing: Year-by-year historicals (2020–2025) and a transparent forecast (2026–2032) with sensitivity bands tied to raw material and trade-policy scenarios.
-
Methodology appendix: Replicable approach combining bottom-up capacity build-ups, OEM vehicle production ramps, and demand elasticity models—valuable for corporate planning and board-level scenario stress tests.
-
Price and cost models: Unit-level cost build-ups for forging vs casting vs steel alternatives, including CAPEX profiles for new forging lines, tooling cycles, yield assumptions, and projected cost curves under different aluminum price scenarios.
-
Supply chain and localization playbook: Mapping of critical suppliers, logistics risk zones, recommended hedge strategies, and tariff mitigation options (contract structuring, tariff engineering, FTAs, nearshoring).
-
Competitive benchmarking: Capability matrices across technology, capacity, geographic reach, certification timelines, and R&D pipelines—enabling objective M&A screening and partnership scouting.
-
Commercial strategies: Go-to-market templates for OEM engagement, value-based pricing approaches, and aftermarket monetization frameworks that preserve margin while scaling volumes.
-
Operational readiness checklists: Site selection criteria, workforce skill requirements for precision forging, anticipated quality control regimes, and capital planning for 2026–2028 ramp phases.
-
Risk heatmap and mitigation: Prioritized risks—from commodity shocks and tariff shifts to certification bottlenecks—with tactical mitigation matrices and contingency triggers suitable for executive decision playbooks.
Actionable strategic recommendations for 2026
-
Prioritize flexible capacity over aggressive scale: Given raw material volatility and tariff unpredictability, staged capacity buildouts with modular forging lines and contract manufacturing options reduce downside risk while preserving optionality.
-
Pursue differentiated product routes: Invest in finish/process differentiation (coatings, paint systems, corrosion protection) and alloy innovations that create defendable margin pools outside pure price competition.
-
Re-evaluate sourcing strategies with tariff-aware models: The mid-2025 tariff adjustments materially change landed cost math. Closure of long-term contracts, nearshoring, or local JV structures can be decisive in preserving competitiveness.
-
Embed certification pathways into product development: ECE and DOT approvals can add months to time-to-market. Integrating compliance milestones into product and production plans is non-negotiable for 2026 launches.
-
Monitor consolidation windows: Market concentration suggests windows for bolt-on acquisitions or technology partnerships. Use CR3/CR5 concentration metrics and capability gaps to target M&A that accelerates entry into commercial vehicle forged segments.
How PW Consulting supports your 2026 planning
We translate this market intelligence into executable outputs: investment memos, supplier due-diligence templates, plant-location scorecards, and transaction-ready financial models. Our scenario frameworks allow clients to stress-test investments against aluminum price shocks, tariff escalations, and demand shifts across vehicle segments.
For stakeholders preparing capital allocation, supplier contracting, or market entry in 2026, the full PW Consulting Forged Alloy Aluminum Wheel Market report provides the data, diagnostics, and decision tools to act confidently. This introduction has showcased our analytical posture and the types of insights you will find in depth. To access the detailed, segment-specific tables, supplier scorecards, and our actionable playbooks, consult the full report and its appendices—where we disclose the granular intelligence that operational teams need to execute successfully in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Forged Alloy Aluminum Wheel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


