



Panthenol Market: 6% CAGR to USD 439.85M by 2032 — PW Consulting

Panthenol Market 2026: Strategic Intelligence Briefing
As PW Consulting’s Lead Industry Analyst, I present this executive industry briefing to orient strategists, business development leaders, and C-suite executives on the strategic stakes as they approach 2026. Our Panthenol Market study synthesizes historical performance, competitive dynamics, supply-side drivers, regulatory inflection points and forward-looking scenarios to inform commercial decisions across product development, sourcing, manufacturing footprint and M&A activity.
Panthenol Market
Why Panthenol matters in 2026
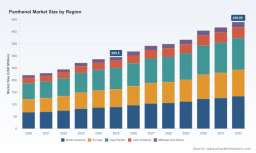
Panthenol has evolved from a niche active into a multi-use functional ingredient embedded across personal care, pharmaceutical and nutrition value chains. Our research shows the global market expanded from approximately USD 220.8 Million in 2020 to about USD 295.5 Million in 2025, reflecting steady recovery and reinvestment after pandemic-era volatility. Looking forward, the market is projected to grow to roughly USD 439.9 Million by 2032, underpinned by a 6.0% compound annual growth rate across the 2026–2032 forecast window. These macro dynamics create an investment calculus that differs materially from other specialty chemistries: steady, mid-single-digit growth; concentration among a handful of global suppliers; and recurring demand from regulated downstream users that value reliability and provenance.
Panthenol Market
What this study delivers (practical outputs)
- Actionable supply-demand model calibrated to 2020–2025 history and stress-tested across three demand scenarios for 2026–2032.
- Price and margin sensitivity analysis that maps feedstock and energy shocks to manufacturer EBITDA under plausible near-term disruptions.
- Regulatory impact matrix that translates recent cosmetics and healthcare rules into reformulation risk, time-to-market changes and labeling costs for manufacturers and brand owners.
- Go-to-market playbooks for incumbents and new entrants covering route-to-market, distribution partnerships, and formulation support services.
- M&A and capacity investment decision framework, including valuation multipliers, integration risks and synergies based on asset type (API-grade vs cosmetic-grade manufacturing).
- Supplier risk heatmap and sourcing optimization toolkit to reduce single-source exposure while meeting quality, sustainability and regulatory specifications.
Market structure and competitive snapshot
The panthenol market exhibits moderate concentration, with the top three suppliers controlling a meaningful majority of global supply and the top five consolidating clear market power. This structure drives a competitive landscape where scale, regulatory credentials and formulation support capabilities determine commercial leverage.
Panthenol Market
- BASF SE: A global leader with deep capabilities in D-Panthenol USP for personal care and pharmaceutical applications. BASF’s recent product line emphasizing renewably sourced panthenol amplifies its sustainability positioning and offers margin and go-to-market advantages among premium personal care brands.
- Royal DSM (dsm-firmenich): A major integrated player across nutritional and health ingredients with pharmaceutical-grade offerings. Their strength lies in cross-category customer relationships and regulatory know-how in high-purity grades.
- Evonik Industries AG: Focused on care solutions and sustainability; the company expanded production capacity in Germany in late 2025 to meet rising demand—an operational response that tightens supply-side dynamics for competitors.
- Lonza Group Ltd and Croda International Plc: Specialty suppliers that blend high-purity production with formulation systems and co-development services, appealing to cosmeceutical and regulated pharmaceutical customers.
- TRI-K Industries, RITA Corporation and select Chinese producers (e.g., Brother Enterprises, Fengchen Group, Jing Jing Pharmaceutical): Providers that compete on high-purity grades, price competitiveness and local market access, particularly for regional formulators and distributors.
Recent corporate activity—capacity expansions by established majors and product launches focused on renewable feedstocks—signals a market where quality, provenance and sustainability claims are differentiating factors, not just price.
Key regulatory and market dynamics shaping 2026 decisions
- Regulatory resets in Europe: Amendments to the EU cosmetics regime that formalize concentration and labeling requirements for panthenol in leave-on formulations take effect in 2026. This will generate near-term reformulation demand and create compliance costs for brands, advantaging suppliers with certified documentation and regulatory support.
- Trade and customs friction: New import declaration requirements in markets such as Mexico introduce administrative complexity for medical and healthcare products. Supply chain teams must update import protocols and contingency plans to avoid delivery slippage for regulated customers.
- Feedstock and pricing noise: Regional feedstock and energy cost pressures produced moderate price volatility in Europe and an upward trend in Asia Pacific during 2025; North American markets experienced end-of-year restocking effects that tightened prompt availability. These episodic movements highlight the need for active price-risk management and flexible sourcing strategies.
Strategic implications for 2026 planning
Our study identifies several strategic imperatives for players across the value chain as they set priorities for 2026 budgets, capital allocation and commercial strategy.
- Sourcing resiliency and dual-sourcing: Given episodic feedstock-driven price moves and regional restocking dynamics, firms should adopt dual-sourcing where certification alignment is required and maintain strategic buffer inventory for critical SKUs serving pharmaceutical and baby-care customers.
- Regulatory-forward product development: Brands and ingredient suppliers must accelerate reformulation and labeling review cycles to align with 2026 EU rules. Suppliers that offer regulatory dossiers, stability data and co-development support will capture outsized share of reformulation spend.
- Segment-focused premiumization: With demand growth steady but not explosive, value capture will come from premiumization—sustainably sourced grades, documented supply chains and performance-backed claims. Multinationals with scale can bundle sustainability credentials with supply guarantees to win enterprise customers.
- Capacity timing and partnership models: The recent capacity expansion by major producers underscores that timing investments matter. New entrants should prioritize tolling, joint ventures or offtake agreements rather than greenfield build-outs unless they can secure advantaged feedstock or technology.
- M&A and bolt-on plays: Given a market where the top players command a substantial share, strategic acquisitions of specialty producers or formulation houses offer faster routes to capability and market access than organic growth—provided integration captures cost and regulatory synergies.
Operational playbook — concrete 90/180/360 day moves
- 0–90 days: Run a supply-chain exposure assessment; validate import documentation and local compliance (e.g., Mexico RFC requirements); renegotiate short-term contracts to include flexibility clauses for feedstock price swings.
- 90–180 days: Execute parallel development tracks for reformulation of impacted SKUs; secure conditional offtake agreements with multiple certified suppliers; begin customer communications on labeling and compliance timelines.
- 180–360 days: Finalize medium-term capacity or partnership decisions; deploy pricing mechanisms with indexation to key feedstock inputs; evaluate M&A targets and integration plans aligned to desired market segments (API-grade vs cosmetic-grade).
Implications by player archetype
- Global majors: Focus on consolidating premium positions through sustainability-credentialed products, global supply guarantees and regulatory services. Prioritize converting capacity into higher-margin, certified grades.
- Specialty formulators/ingredient houses: Differentiate via formulation support and bundled regulatory dossiers. These players benefit by deepening relationships with personal care and pharma customers who face reformulation demands.
- Regional manufacturers and distributors: Compete on responsiveness and cost but invest selectively in certification and quality systems to capture regulated demand. Partnering with global players for co-manufacturing can unlock higher-value customers.
- New entrants: De-risk entry with toll-manufacturing or licensing arrangements and target niche premium claims (e.g., bio-based feedstocks) rather than scale-driven commodity supply.
What we are watching into 2026
- Feedstock and energy price trajectories across major producing regions, and the degree to which costs pass through to formulators.
- Adoption pace of the EU regulatory changes and how quickly brands reformulate leave-on products to meet concentration and labeling requirements.
- Commercial impact of capacity additions by incumbents—whether they will relieve supply tightness broadly, or be absorbed by premium segments.
- Consolidation activity among specialty chemical players and whether strategic buyers target downstream formulation assets or upstream capacity for integration synergies.
Closing — the strategic value of this report for 2026 decisions
For executives planning 2026 investments, this Panthenol Market research is a decision-grade resource: it quantifies the size and trajectory of the market (historical and forecast), identifies the structural levers that determine margin capture, maps regulatory and trade disruption risks, and prescribes near-term operational moves. We intentionally surface directional segment insights and supplier power dynamics while reserving detailed sub-segment figures and granular regional/application splits for the full report—this approach ensures you receive a high-trust, evidence-based strategic preview while preserving the granular datasets that underpin investment and commercial execution.
To convert these insights into a tailored action plan—whether you are prioritizing sourcing resilience, evaluating an M&A target, or redesigning your product portfolio for regulatory compliance—our extended dataset and scenario models provide the necessary quantitative backing. Access to the full report will enable you to run custom scenarios using our demand, pricing and cost modules and to download the supplier matrix and M&A playbook that underlie the recommendations summarized here.
For detailed analysis of this topic, please visit the official page: Panthenol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


