



PW Consulting: Cast Resin Transformers Market to Reach USD 6.42 Billion by 2032 at 9.5% CAGR

Cast Resin Transformers Market — Strategic Preview for 2026 Decision-Making
As energy systems turn denser, more electrified and increasingly safety-conscious, cast resin dry‑type transformers have moved from niche application stacks into strategic procurement and product-innovation agendas. PW Consulting’s latest Cast Resin Transformers Market study (base year 2025; historical window 2020–2025; forecast 2026–2032) synthesizes validated market sizing, trend vectors and competitive playbooks designed to inform board-level and operational decisions in 2026. This preview highlights the strategic value of the study while deliberately reserving core segmented tables and granular company valuations for subscribers who access the full analysis.
Cast Resin Transformers Market
Macro trajectory and what it implies for 2026
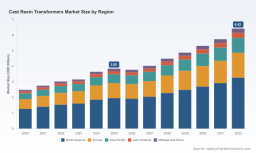
We track the market from a 2020 baseline through a 2025 reconciliation and then through a seven‑year forecast horizon. The cast resin transformers market expanded notably in the early 2020s — reflecting accelerating electrification of buildings, industrial reconfiguration and heightened safety requirements — rising from approximately USD 2.5 billion in 2020 to a reconciled base‑year figure of USD 3.85 billion in 2025. Our forecast begins in 2026 with a modest near‑term adjustment, followed by an average compound annual growth rate (CAGR) of 9.5% across the forecast period, culminating in a market size of roughly USD 6.4 billion by 2032.
Cast Resin Transformers Market
For 2026 decision-makers this trajectory is meaningful for three reasons: (1) growth is robust but non‑linear — implying timing sensitivity to product launches and capacity expansion; (2) an elevated safety and retrofit market exists alongside new-build demand, creating distinct product‑market fits; and (3) rising unit values and serviceable lifecycle revenues make aftermarket and digital monitoring services increasingly attractive profit pools.
Cast Resin Transformers Market
Critical dynamics shaping 2026 choices
-
Regulatory and fire‑safety demands — Standards such as IEC 60076‑11 and high‑fire‑safety certifications (Trihal and equivalent schemes) are shifting procurement specifications for indoor and critical installations. Compliance is now a baseline requirement in many urban and mission‑critical projects, raising the technical bar for product certification and third‑party testing.
-
Technology differentiation — Expect product features to bifurcate along two axes: enhanced safety (fire‑retardant systems, improved potting and reduced flammability) and digitalization (IoT thermal monitoring, remote diagnostics). Vendors demonstrating both will capture premium project pipelines.
-
Supply‑chain volatility — Cast resin production relies on epoxy systems with feedstocks sensitive to global chemical markets (notably bisphenol A and epichlorohydrin). Price and availability of these inputs materially influence unit economics and inventory strategies; firms must move from reactive procurement to hedged or partnered sourcing models.
-
Manufacturing footprint and labour considerations — Specialist producers operate with compact, skilled workforces and concentrated capabilities. Manufacturing and staffing models (for example, mid‑sized facilities with 200–500 employees) affect scale, customization capability and cost basis — critical when evaluating near‑term capacity expansion or contract manufacturing options.
-
Market concentration — The market exhibits mid‑level concentration among incumbents (our competitive concentration metrics indicate a meaningful share for top players), leaving room for specialization, targeted consolidation and strategic partnerships rather than dominant market control.
Competitive positioning — strategic takeaways
Industry incumbents fall into two archetypes: global platform players with broad portfolios and international manufacturing footprints, and regional specialists focused on niche performance, bespoke engineering and local market penetration. Examples that exemplify these archetypes include established international suppliers investing in digital and sustainable product variants, and specialist manufacturers promoting engineered dry‑type solutions for demanding applications.
-
Global platforms (broad service, global footprint): These firms bundle system integration, certification and aftermarket service. Their playbook centers on cross‑sell into larger accounts and leveraging global delivery networks to underwrite large tenders.
-
Regional specialists (custom engineering, focused segments): These producers emphasize application‑specific solutions — for rail, marine, data centres and industrial clients — and often lead with fast customization, local support and tight supply‑chain control.
Recent market developments underline these positioning strategies: product launches that combine advanced fire‑safety and bio‑based resins; new on‑load tap‑changer configurations for dry‑type units; and consistent exhibition and marketing activity aimed at sectors such as renewables and data centres. These moves are early indicators of where margin expansion and order‑book growth will originate.
Strategic themes for executive agendas in 2026
-
Certification as go‑to‑market currency — Prioritize product certification (fire safety and environmental standards) as an entry and pricing lever for indoor and mission‑critical projects. Certification timelines must be integrated into product roadmaps and procurement cycles.
-
Digitalization and lifecycle revenue — Embed condition monitoring and thermal analytics into product offers to convert equipment sales into recurring service revenues and to differentiate on total cost of ownership (TCO).
-
Supply‑chain resilience — Lock in strategic feedstock agreements, explore resin substitution pathways and assess nearshoring or dual‑sourcing to mitigate epichlorohydrin and bisphenol A volatility.
-
Product modularity and retrofit pathways — Develop modular portfolios that enable staged upgrades (e.g., retrofits for fire containment, IoT sensing or OLTC integration) which appeal to utilities and urban operators constrained by CAPEX budgets.
-
Service and aftermarket scale‑up — Build service organisations capable of supporting predictive maintenance and safety audits; the aftermarket is a major lever for margin improvement as installed bases age.
-
Targeted M&A and alliance plays — Given mid‑market concentration, opportunistic acquisitions of regionally strong specialists can accelerate technology access and local market entry without replicating manufacturing investments.
What PW Consulting’s full study delivers (operationally focused)
The full report is structured to move quickly from insight to execution. Key components include:
-
Validated market sizing and reconciled historicals (2020–2025) and an editable forecast model (2026–2032) with scenario toggles for resin price shocks, regulatory acceleration and urban electrification trajectories.
-
Technology and product benchmark: comparative scorecards across electrical performance, fire safety, maintainability and digital readiness, including UX‑driven deployment notes for installers and OEMs.
-
Supply‑chain exposure mapping and procurement playbook: supplier heatmaps, single‑sourced component risks, and recommended contracting strategies to stabilise input costs.
-
Competitive intelligence module: strategic profiles, capability grids and M&A heatmaps for incumbent and challenger manufacturers (detailed scorecards and financial proxies available in the full report).
-
Regulatory impact matrix and compliance pathways to support product development timelines and market access planning.
-
Commercial playbooks and 90/180/365‑day action plans aligned to business objectives (growth, margin improvement, risk reduction) including KPI templates and investment threshold guidance.
90/180/365-day tactical checklist for executives
-
0–90 days: Initiate supplier risk audits for resin feedstocks; accelerate certification gap assessments for indoor and critical‑site offerings; pilot a telemetry retrofit on a controlled installed base.
-
90–180 days: Finalize strategic procurement contracts with hedging clauses; launch a certified product upgrade program targeted to large urban utilities; appoint a cross‑functional digital services lead.
-
180–365 days: Evaluate M&A targets or JV partners that offer either specialized engineering capability or regional manufacturing presence; scale aftermarket services with bundled SLAs and predictive maintenance contracts.
Why this intelligence will matter for your 2026 planning
Decisions taken in 2026 will lock in product roadmaps, sourcing arrangements and service models that define competitiveness over the next decade. The market’s combination of steady near‑term demand, mid‑to‑high forecast growth (9.5% CAGR through 2032), evolving safety standards and supply‑chain sensitivity creates both upside and execution risk. PW Consulting’s study converts these macro signals into actionable playbooks: prioritised investments, quantified supply contingencies and competitive strategies that protect margin while enabling share capture.
Next steps
This preview intentionally highlights the strategic contours while withholding detailed segmentation tables and company financial proxies to preserve the research’s commercial core. Subscribers to the full report receive the complete quantitative model, granular segment breakouts, vendor scorecards and executable templates for procurement, product and M&A teams. For access to the full dataset, model licence and bespoke advisory support aligned to your portfolio, contact PW Consulting through our research portal.
For detailed analysis of this topic, please visit the official page: Cast Resin Transformers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


