



PW Consulting: Supermarket Lockers Market to Reach USD 239M by 2032 at 5.65% CAGR

Supermarket Lockers Market — Strategic Briefing for 2026 Decision Makers
Executive Summary
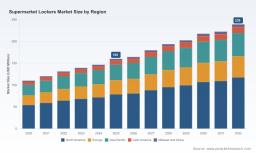
Between 2020 and 2025 the supermarket lockers market moved from a niche operational convenience to a strategic fulfillment asset. Our analysis shows total market value expanding from approximately USD 110 million in 2020 to USD 160 million in 2025. Under current demand drivers and technology adoption pathways the market is forecast to grow at a compound annual growth rate (CAGR) of 5.65% through a 2026–2032 forecast window, reaching roughly USD 239 million by 2032. Market concentration is moderate: the three largest players account for a significant share of revenue (CR3 ~45.6%), and the top five approach two-thirds of the market (CR5 ~62.3%).
Supermarket Lockers Market
For corporate leaders planning allocation of capital and operational redesigns in 2026, this report functions as both a map and a toolkit: it explains where demand is maturing, which technology and service strategies de-risk rollout, how regulatory and labor pressures alter ROI, and what execution options preserve optionality as the market matures.
Supermarket Lockers Market
Why this matters for 2026 planning
- Operational leverage: Self-service locker implementations materially reduce front-line labor requirements in supermarket pickup operations. Our sector analysis models indicate labor-savings lift that can meaningfully shorten payback periods on in-store automation investments.
- Network economics: As installations scale, per-unit economics and software/telemetry amortization change. The market’s steady CAGR through 2032 implies a clear runway for incremental deployments rather than one-time waves — an important factor for multi-year CAPEX planning.
- Competitive positioning: Locker networks are increasingly battlefield terrain for click-and-collect, third-party delivery integrations, and perishable-handling differentiation. Early adopters that align locker strategy with broader omnichannel fulfillment can convert a logistics cost center into a customer-acquisition and retention channel.
Market trajectory & implications
The historical trajectory (2020–2025) reflects both pragmatic deployments in high-traffic supermarkets and early rollouts of temperature-controlled and smart-locker variants. The projected expansion to 2032 at a mid-single-digit CAGR signals steady mainstreaming rather than explosive disruption — a profile that favors disciplined, staged investment strategies.
Supermarket Lockers Market
Key implications for 2026:
- Prioritize pilots that replicate the edge case economics of your core stores rather than chasing headline installations. The maturity curve rewards proof points that demonstrate consistent throughput and customer adoption.
- Design contracts and procurement windows to capture cost declines in modular electronics and standardized connectivity without locking into legacy, proprietary ecosystems.
- Factor regulatory compliance and data localization into vendor selection and IT integration plans.
Dynamics shaping demand and supply
- Labor and cost pressure — Automation reduces front-line pickup staffing needs; our sector workbench shows meaningful reductions in staffing expense for grocery pickup workflows, shortening TCO timelines where throughput is sufficient.
- CAPEX and unit economics — Initial capital outlay per locker varies by size and feature set. Procurement strategies focused on modularity, upgradeability, and energy-efficient electronics materially reduce lifecycle maintenance and replacement costs.
- Regulatory environment — Data sovereignty and e‑commerce last-mile regulations are active constraints. Operators should expect requirements for localized user-data storage and always-on, contactless access mechanisms when designing solution architecture.
- Sustainability and materials — Modular designs that incorporate recyclable components and low-energy electronics are becoming best practice for high-traffic environments, reducing both operating costs and ESG risk.
Competitive landscape — strategic takeaways
The market features a mix of specialized locker manufacturers, logistics platform players, and robotics-integrated providers. Five firms are noteworthy for their combination of product breadth, route-to-market, and recent momentum:
- Cleveron AS (Viljandi, Estonia) — Known for combining robotic automation with traditional locker designs. Strength: modular robotics that support higher throughput click-and-collect scenarios. Strategic fit: retailers aiming at high-volume, automated pickups and those testing robotics at scale.
- Luxer One (McClellan, California) — Focused on smart package locker systems optimized for BOPIS and third-party grocery delivery. Recent product rollouts and trade-show visibility underline a push for retail-market mindshare and seasonal/peak-delivery solutions.
- Parcel Pending by Quadient (Irvine, California) — Broad deployment footprint and depth in temperature-controlled solutions. Recent disclosures highlight a large global installation base and revenue targets tied to retail and grocery use cases, signaling mature delivery and service capabilities across regions.
- KEBA AG (Linz, Austria) — High-capacity locker solutions with strong integration into parcel networks and retail partners. Strategic alliances and exclusive supplier relationships emphasize KEBA’s role in infrastructure-led rollouts.
- TZ Limited (Singapore) — Regional specialist with click-and-collect smart lockers optimized for supermarket environments, often suited to quick deployments and multi-format store rollouts in dense urban markets.
Recent company developments point to two operational realities: (1) incumbent locker and parcel players are pushing aggressive installation and revenue targets tied to grocery deployments, and (2) suppliers are differentiating by temperature control, robotics, and software integrations that simplify partner logistics.
What the full PW Consulting report includes (operationally focused)
We designed the full study as a pragmatic decision-support package for procurement, operations, and strategy teams. Highlights include:
- Methodology and transparent market-sizing: historical series (2020–2025) and a 2026–2032 forecasting model with scenario toggles for adoption rates and pricing.
- Decision playbooks: site-selection criteria, pilot templates, and rollout sequencing optimized for different store footprints and customer demographics.
- Vendor diligence matrices: comparative frameworks for product features (temperature control, robotics, integration APIs), service-level expectations, and contract negotiation levers.
- Commercial tools: TCO and ROI calculators, maintenance schedules, and depreciation schedules aligned to common supermarket procurement cycles.
- Compliance and data strategy guidance: implementation checklists to satisfy data-localization and contactless-access regulations in major markets.
- Case studies and procurement templates: real-world examples and contracting language to accelerate commercial negotiations.
The report is intentionally practical: executives receive not only market sizing and trend analysis but also the templates and KPIs needed to move from pilot to scale without unnecessary rework.
Recommended 2026 playbook — actionable steps
- Run two parallel pilots: one focused on high-frequency urban stores with temperature-controlled units; the other on suburban pickup models using standard smart lockers. Use identical KPI sets (customer pickup time, locker utilization, incremental basket lift, labor delta) for apples-to-apples comparison.
- Score vendors against a weighted matrix that prioritizes API openness, data residency options, modular upgrade paths, and proven maintenance throughput.
- Embed regulatory checkpoints into procurement milestones: contract sign-off contingent on demonstrable data localization and contactless-access compliance tests.
- Stage capital allocation over a 36-month horizon tied to utilization milestones rather than a single upfront budget; this both mitigates risk and captures vendor-led cost declines in electronics and connectivity.
- Adopt a sustainability clause in procurement to secure recyclable materials and low-energy electronics as baseline requirements — a move that lowers operational energy spend and supports corporate ESG goals.
KPIs to monitor in 2026
- Locker utilization (pickups per locker per day)
- Average customer pickup time and rate of failed pickups
- Labor hours saved per pickup node and associated wage delta
- TCO per locker over a 5‑ to 7‑year lifecycle (including service contracts)
- Percentage of transactions routed via integrated API vs manual override
Concluding note — strategic framing
Supermarket lockers are not a binary decision: they are a configurable infrastructure layer that can reshape last-mile economics, customer convenience, and store operations when deployed with discipline. The mid-single-digit CAGR through 2032 suggests patient, stage-gated investment will generally outperform speculative scale-ups. The full PW Consulting Supermarket Lockers Market study supplies the granular segmentation, vendor scorecards, and financial models necessary to translate these strategic insights into executable programs.
To access the granular segmentation, vendor financials, and downloadable ROI tools that underpin these recommendations, visit our full report landing page. The executive briefing above is designed to orient 2026 planning — the detailed modules will accelerate procurement, piloting, and scaled deployment with confidence.
For detailed analysis of this topic, please visit the official page: Supermarket Lockers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


