



PW Consulting: Refuge Chamber Market to Hit USD 268.56 Million by 2032 (4.3% CAGR)

Refuge Chamber Market — 2026 Strategic Briefing
As PW Consulting’s lead industry analyst, I present a focused introduction to our latest Refuge Chamber Market study — a practitioner-oriented briefing engineered to inform board-level strategy, procurement choices, and operational programs through 2026 and beyond. Built on a rigorous 2020–2025 historical baseline (base year 2025) and forward-modeled across 2026–2032, the market is sized and forecast in USD (Million). The market grew from approximately USD 162.0 Million in 2020 to USD 200.0 Million in 2025 and is projected to reach nearly USD 268.6 Million by 2032, reflecting a compound annual growth rate (CAGR) of roughly 4.3% over the forecast window. These headline numbers frame a stable, risk-aware growth environment where safety-enabled capital and service revenue create strategic options for multiple stakeholders.
Refuge Chamber Market
Why this study matters for 2026 decision cycles
- Capital allocation: Boards and CFOs must weigh mine and tunneling safety upgrades against competing CAPEX demands. Our study provides the financial envelope and scenario-tested use-cases that translate safety requirements into capital and operating budgets for 2026.
- Procurement & supplier strategy: Procurement teams need a supplier scorecard and a practical RFP architecture that reduces specification ambiguity while ensuring regulatory compliance. The report supplies templates and vendor comparison frameworks to shorten decision cycles.
- Product and service roadmaps: OEMs and systems integrators require a near-term view on feature priorities (e.g., life-support autonomy, remote telemetry, modularity) to sequence product development and aftermarket service investments for the upcoming procurement window.
- Risk management & insurance: Insurers and risk officers must reconcile equipment reliability, activation profiles, and total cost of ownership (TCO) with premium and reserve-setting decisions; our modelling makes these trade-offs explicit.
- M&A and partnership screening: The market’s steady mid-single-digit CAGR points to value-accretive consolidation opportunities — particularly where service, software, or local manufacturing capabilities can be accretive to core product offerings.
Market dynamics and growth drivers
The Refuge Chamber Market growth is underpinned by several persistent and emergent forces:
Refuge Chamber Market
- Regulatory tightening and audit scrutiny: Stricter mine safety regimes and more frequent emergency preparedness audits sustain baseline demand for refuge chambers and upgrade kits.
- Infrastructure and tunneling activity: Public-private partnerships and urban tunneling projects continue to require on-board and fixed refuge solutions, creating a steady demand corridor in developed and emerging markets.
- Technological diffusion: Improvements in closed-circuit breathing systems, CO2 scrubbing, positive pressure isolation, and low-maintenance ventilation increase the reliability and appeal of modern refuge solutions.
- Service- and software-led differentiation: Remote monitoring, predictive maintenance, and activation analytics are creating recurring-revenue opportunities and shifting buyer preference toward suppliers with telemetry-enabled service offers.
- Cost pressures and total cost of ownership focus: Operators increasingly evaluate lifetime maintenance and inspection burdens, creating opportunity for suppliers who can demonstrably reduce TCO through design for maintainability and modular spare parts.
These drivers interact with macro variables — commodity cycles, regional CAPEX programs, and labor market constraints — to create a market environment best described as "steady growth with episodic acceleration" rather than boom-bust volatility.
Refuge Chamber Market
What the report contains: practical, operational deliverables
Our study is designed as a decision-support tool rather than a purely academic resource. Highlights include:
- Executive dashboard with headline market sizing, trajectory, and sensitivity (2020–2032).
- Methodology appendix that documents data sources, triangulation logic, and key assumptions used to build the market model.
- Scenario-based financial models (baseline, upside, downside) with editable inputs so clients can test internal assumptions against our base case CAGR of 4.3%.
- Procurement playbooks: RFP templates, evaluation scorecards, and technical checklists aligned to commonly audited safety standards.
- Implementation roadmaps: activation drills, inspection schedules, spare-parts planning, and service-level agreement (SLA) prototypes for operators and mine owners.
- Technology deep-dive: comparative assessment of life-support systems, monitoring stacks, modular designs, and activation mechanisms.
- Go-to-market and aftermarket strategies for OEMs and integrators, including partnership archetypes and pricing approaches that prioritize service annuity economics.
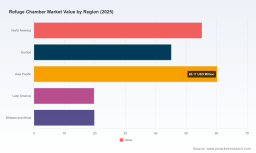
To preserve the single-source strategic value of the full study, the article intentionally omits granular regional and application-level splits and proprietary price curves; those detailed segmentations and downloadable models are available on the report landing page and to licensed clients.
Competitive landscape — incumbents, challengers, and strategic positions
The market exhibits moderate concentration: the top three players control a substantial share of installed base activity, with the top five broadening that footprint further. This concentration reflects the technical and regulatory barriers to entry — certification, life-support engineering, and trusted service networks — but it does not preclude specialized entrants who can deliver clear incremental value.
- MineARC Systems (Kewdale, Western Australia) — Positioned on intrinsic safety for coal and tunneling markets. Their portfolio emphasizes hazard-tested units with closed-circuit breathing, CO2 scrubbing and integrated monitoring, making them a natural choice for high-risk coal operations and customers prioritizing turnkey safety certification.
- Strata Worldwide (Sandy Springs, Georgia) — Competes on configurable refuge solutions and elective features. Their strength lies in customization and global design options, appealing to complex operations and international contractors that demand fit-for-purpose installations.
- Drägerwerk AG & Co. KGaA (Lübeck, Germany) — Leverages breadth in respiratory and isolation technologies to deliver mobile and on-board refuge chambers that prioritize positive-pressure isolation and industrial-grade breathing gas systems—a good match for extreme underground conditions and tunneling projects.
- SUB'ROCA (France) — Differentiates through modular, connected chambers with extended autonomy and low-maintenance ventilation, addressing operators who need ease-of-deployment, quick reconfiguration and integrated telematics.
- Wattrix (WTX Mining) (Boronia, Victoria) — Focuses on reliability, maintainability and low total cost of ownership. Their value proposition aligns to operators managing tight maintenance budgets and looking for simplicity.
- WeWalter S.r.l. (Cologno Monzese, Milan) — Serves tunneling and large-construction markets with quick-activation standard models designed for fast deployment in linear construction environments like TBMs and road tunnels.
- ON2 Solutions (Morden, Manitoba) — Builds integrated refuge systems and portable chambers with automated life-support; appeals to customers seeking end-to-end systems rather than component suppliers.
- Shandong China Coal Industrial & Mining Supplies Group (Shandong Province) — A major regional manufacturer with product lines focused on coal-mine resilience, oxygen systems and explosion-protection, well-positioned for domestic projects and price-sensitive tender environments.
Strategic takeaways: market leaders win on demonstrated safety performance, certification history, and service networks; challengers can win pockets of demand through niche capabilities — fast activation, connectivity, low TCO — or through price-competitive production in regional contexts.
Strategic playbook for 2026 (recommended actions)
- For operators: Prioritize tested life-support autonomy and remote monitoring in the next procurement cycle. Insist on integrated maintenance and spare-parts plans that convert safety equipment into operational readiness, not just capital assets.
- For OEMs/suppliers: Invest in telemetry and service offerings that migrate buyers from one-off hardware purchases to recurring revenue models. Demonstrate failure-mode data and MTTR (mean time to repair) improvements in bid responses.
- For investors and PE: Target assets that combine product manufacturing with scalable service delivery — aftermarket contracts materially improve margin visibility relative to hardware-only models.
- For insurers and risk managers: Use scenario models to align premium pricing with activation likelihood and documented maintenance regimes. Incentivize certified training and drill frequencies to reduce claim exposure.
- For governments and regulators: Standardize certification crosswalks where possible to reduce procurement friction for international suppliers while maintaining minimum safety envelopes.
Scenario planning and sensitivities
Our forecast base case uses a 4.3% CAGR. Key sensitivities include: commodity-driven CAPEX cycles (affecting upside potential), regulatory shocks that can precipitate faster retrofits, and supply-chain constraints that may delay deployments and compress near-term revenue. We model three practical scenarios in the report — baseline, accelerated adoption (higher safety spend and retrofit cadence), and constrained CAPEX (budgetary pullback) — and provide prescriptive interventions for each.
Conclusion — how to use this study in 2026 strategy
Refuge chambers are not a commodity: they are safety-critical systems whose value accrues across engineering, operations, and risk-management functions. For 2026, the strategic imperative is clear — translate regulatory and operational requirements into procurement and service strategies that reduce operational risk while protecting capital. Our report gives buyers, suppliers, investors and policymakers the tools to do precisely that: verified market sizing, scenario-ready financials, supplier scorecards, compliance checklists, and operational roadmaps. If your 2026 planning cycle includes safety modernization, vendor selection, M&A screening, or service transformation in underground environments, this study is designed to be the single-source reference that accelerates good decisions.
We intentionally withhold granular regional and application-level splits in this briefing to preserve the unique analytical value of the full report; those detailed segmentations, downloadable models, and procurement templates are available in the licensed release on the PW Consulting report page.
For access to the complete dataset, bespoke scenario runs, or a walkthrough of the procurement templates and vendor scorecards, contact the PW Consulting research team to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Refuge Chamber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


