



PW Consulting: OBC market to reach USD 325M by 2032, growing at 7.88% CAGR

Olefin Block Copolymer (OBC) Market — 2026 Strategic Preview for Corporate Decision-Makers
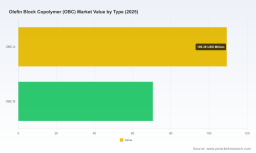
PW Consulting’s latest market study on Olefin Block Copolymer (OBC) delivers a focused, decision-grade perspective for executives preparing strategic moves in 2026. Built on a 2025 base year and a 2026–2032 forecasting window, the analysis quantifies a clear growth trajectory for the OBC market — underpinned by a multi-year compound annual growth rate of 7.88% — and projects material expansion from the 2025 baseline through 2032. For companies facing capital allocation decisions, product roadmaps, or supply-chain reconfigurations next year, this research converts market momentum into operational priorities and investment guardrails.
Olefin Block Copolymer (OBC) Market
Why this research matters in 2026
-
Timing of capacity investments. Producers and converters considering new lines, debottlenecking, or backward integration need an independent forward view of demand growth and grade migration to avoid overcommitment or missed opportunities.
Olefin Block Copolymer (OBC) Market -
Shifting application content. Electrification, packaging performance demands, and lightweighting are altering polymer specifications. Understanding which grade attributes command a premium is essential for product positioning and pricing strategy.
Olefin Block Copolymer (OBC) Market -
Supplier strategy and risk. Feedstock volatility, regulatory shifts on recyclability and chemical restrictions, and recent capacity announcements make supplier selection and contracting structure high-priority items for procurement teams.
-
M&A and partnership scouting. With established polymer majors and specialized innovators both active in the space, 2026 will be a year to choose between bolt-on acquisitions, JVs, or licensing arrangements to capture differentiated value.
What this PW Consulting study delivers — practical, transaction-ready outputs
-
Robust market sizing and forward forecast built from a bottom-up model calibrated to primary interviews, company disclosures, and trade flows. We provide topline numbers for the 2020–2025 historical window and a detailed projection through 2032 to support strategic planning horizons.
-
Demand-driver analysis that links macro trends (mobility electrification, packaging format shifts, adhesives performance needs, and consumer durables design) to grade-level uptake and willingness-to-pay.
-
Supply-side mapping with plant-by-plant capacity overlays, announced expansions, and technological differentiators. Notable public inputs — such as producer disclosures of existing INFUSE™ production capacity and recent expansion programs — are integrated into our capacity-utilization scenarios.
-
Price and margin modelling that stresses test outcomes across raw-material swings, grade mix evolution, and competitor pricing tactics. These transparent models are provided in Excel format for client-side sensitivity runs.
-
Competitive scorecards and playbooks. Each leading supplier is profiled on technology platform, go-to-market posture, typical end-use relationships, and likely near-term strategic moves. M&A targets and licensing candidates are highlighted for acquirers and strategic partners.
-
Scenario planning and a decision matrix tailored for 2026 actions — from greenfield investments to tiered off-take agreements — enabling rapid prioritization under multiple demand and supply futures.
-
Regulatory and sustainability impact assessment, covering recyclability requirements, circular-economy pathways, and disclosure obligations that influence product acceptance in regulated end-markets.
Competitive landscape — incumbents, challengers, and capability clusters
-
Dow Inc. (Midland, Michigan, United States) — A focal supplier with an established INFUSE™ OBC portfolio targeting soft-touch, sealing and flexible applications. Public signals around production capacity and announced expansions position Dow as a volume leader with an expansive grade slate. Recent capacity expansion announcements and earlier capacity declarations have important implications for regional supply balance and pricing dynamics.
-
Mitsui Chemicals, Inc. (Tokyo, Japan) — A technology-led player with NOTIO™ grades focused on automotive soft-touch and sealing. Strong OEM linkages in passenger vehicle supply chains and reported OBC volume growth through 2024–2025 tie Mitsui closely to vehicle platform content trends.
-
LG Chem Ltd. (Seoul, South Korea) — Pursuing metallocene-derived elastomers that compete with OBC in packaging and consumer goods. Planned commercial introductions position LG Chem to capture growth in flexible packaging and higher-volume consumer segments.
-
ExxonMobil Corporation (Irving, Texas, United States) — With Vistamaxx™ performance polymers that overlap the OBC value proposition, ExxonMobil continues to push into performance niches; a recent premium-grade launch for waterproof membranes in construction underscores product diversification within the family of performance olefins.
-
Borealis AG (Vienna, Austria) , LyondellBasell Industries N.V. (Rotterdam, Netherlands) , SABIC (Riyadh, Saudi Arabia) , and Eastman Chemical Company (Kingsport, Tennessee, United States) — These players offer complementary product lines or OBC-adjacent elastomers and bring regional strength, film- and molding-focused grade sets, and integration advantages. Collectively, the competitive set blends large polymer majors with specialty innovators, producing differentiated grade stacks and commercial models.
Recent industry developments and their strategic implications
-
Capacity and capability moves: Several producers have publicly signalled capacity increases and expanded product families, shifting the supply curve and accelerating the commercialization of higher-performance grades. These expansions necessitate closer attention to timing: new tonnes arriving in-market can depress spot spreads even while average selling prices for premium grades hold.
-
Product innovation: New premium grades pitched at construction membranes and other specialty outlets expand the addressable market for OBC-type polymers beyond traditional applications. This increases the strategic value of portfolio breadth and application development capabilities for securing long-term contracts.
-
OEM-driven adoption: Automotive manufacturers remain a critical growth vector, with some producers already embedded in OEM platforms. This relationship-driven demand creates differentiated opportunities for companies that can meet automotive qualification and scale supply reliably.
-
New entrants and adjacent technologies: Metallocene-derived elastomers and proprietary performance olefins challenge incumbents on cost and performance in selected applications, raising the bar for continuous product development and customer proof-points.
Market dynamics — where margins will be made in 2026
-
Grade premiumization: Expect the clearest margin opportunities in specialized grades that solve well-defined performance gaps (e.g., sealant adhesion, waterproofing membranes, and high-elasticity footwear components). Commodity-grade competition will be driven by scale, feedstock integration, and logistics efficiencies.
-
Geography of cost and access: Regional feedstock availability, existing cracker integration, and plant footprint decisions will determine who can sustainably supply low-cost volumes versus who must play the specialty/technical-service card.
-
Customer co-development: Firms that embed technical service, rapid qualification capabilities, and joint cost-to-serve models will secure longer-term contracts and reduce the churn associated with spot-sourced supply.
-
Risk vectors: Volatility in olefin feedstock prices, regulatory shifts around polymer recycling, and the pace of EV adoption introduce upside and downside scenarios that materially alter the ROI calculus for 2026 investments.
How to use this research for 2026 decision-making
-
Board-level capital allocation: Use our scenario outputs to stress-test greenfield timing and scale, identify break-even price curves, and set go/no-go triggers tied to realized demand and feedstock outcomes.
-
Product portfolio prioritization: Align R&D and commercialization spend with grade attributes that command premium adoption in target applications; deprioritize commoditized grade development where scale players dominate.
-
Commercial contracting: Negotiate supply agreements with volume-flex mechanisms and indexed pricing that protect against short-term feedstock shocks while preserving upside participation in premium-grade uptake.
-
M&A and partnerships: Leverage our target screens and scorecards to identify acquisition candidates that fill technological gaps, accelerate market entry, or offer advantaged regional footprints.
Next steps — where the full intelligence sits
This preview frames the strategic choices that will matter in 2026, but the operational details and the proprietary models that turn foresight into executable initiatives are contained in the full PW Consulting OBC Market report. The complete package includes granular regional and application demand splits, company-level market shares, plant-level capacity schedules, price and margin ladders by grade, and an editable Excel model for bespoke sensitivity analysis. For executive briefings, tailored scenario workshops, or to license the underlying dataset and commercial templates, contact PW Consulting to schedule an engagement.
For detailed analysis of this topic, please visit the official page: Olefin Block Copolymer (OBC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


