



PW Consulting: Advocacy Software Market to Hit USD 730.45M by 2032 at 10.12% CAGR

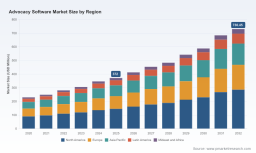
Advocacy Software Market 2026: Strategic Preview for Enterprise Leaders
As PW Consulting’s lead industry analyst, I present a strategic preview of our Advocacy Software Market research — a pragmatic guide for enterprise decision-makers preparing vendor, product, and investment choices in 2026. The space has moved beyond simple petition pages and email blasts; it is now a data‑driven, AI‑infused layer of civic engagement, public affairs, and social impact technology. Our benchmarking shows the global market expanding at a compounded annual growth rate of approximately 10.12% from the recent historical baseline, nearly doubling in scope across the upcoming forecast window. These macro dynamics create both opportunity and strategic risk for procurement, program teams, and C-suite leaders who must balance reach, compliance, and operational scalability.
Advocacy Software Market
Why this study matters for 2026 decisions
-
Timing and momentum: The advocacy market crossed an inflection point over 2020–2025 as organizations shifted budgets toward digital constituent engagement and policy intelligence. With continued double‑digit CAGR, 2026 is the year many buyers move from tactical pilots to enterprise rollouts — making vendor selection, data governance, and integration choices consequential for multi‑year programs.
Advocacy Software Market -
AI and automation are operational imperatives: Leading vendors are embedding agentic AI capabilities and automation into workflows that historically consumed disproportionate staff time (e.g., legislative monitoring, petition routing, and supporter triage). Organizations that treat AI as a strategic enabler — not just a feature checkbox — will compress time‑to‑value and materially reduce labor costs in advocacy operations.
Advocacy Software Market -
Regulatory and reputational exposure: Heightened privacy regulation (GDPR, CCPA) and a measurable rise in sector breaches have forced a rethink of vendor risk assessments. By 2026, privacy‑centric architectures and demonstrable security postures are procurement gating items, not negotiation levers.
Market dynamics and the business implications
-
Growth drivers: Digital-first campaigning, expanded fundraising and supporter engagement channels, and the adoption of AI for policy monitoring collectively drive sustained market growth. Expect vendors to accelerate investment in embedded analytics, predictive segmentation, and real‑time action orchestration.
-
Consolidation and concentration: The competitive landscape shows a moderate level of concentration among established players, while a healthy long tail of niche and open‑source options retains tactical appeal. This hybrid structure creates room for both platform consolidation and point-solution sourcing depending on organizational risk appetite and functional depth requirements.
-
Security and compliance as differentiators: Data breaches and regulatory scrutiny mean that vendors who can demonstrate privacy‑by‑design, comprehensive audit capabilities, and robust anonymization processes will win larger enterprise agreements. Procurement teams must bake compliance verification into RFPs and pilots.
-
Cost and accessibility: Entry-level pricing tiers remain available for grassroots and smaller organizations, but enterprise buyers face a different calculus — total cost of ownership, integration overhead, migration costs, and the staff resources required to operationalize sophisticated features.
Competitive landscape: strategic profiles and implications
Our coverage examines established platform families, specialist vendors, open‑source projects, and adjacent policy intelligence suppliers. A concise, comparative read of the key players provides insight into where functional strengths and go‑to‑market plays are concentrated:
-
Blackbaud — Traditionally strong in nonprofit fundraising and constituent engagement, Blackbaud has moved decisively into AI, launching an AI agent and an industry coalition to accelerate embedded intelligence for social impact work. For enterprise buyers, Blackbaud signals a platform‑level approach to combining fundraising, analytics, and agentic automation — attractive for organizations seeking an integrated supplier with scale.
-
NationBuilder — With the recent introduction of NationBuilder Engage, the company is sharpening its multi‑channel advocacy and volunteer mobilization capabilities. NationBuilder’s pricing accessibility at the entry level makes it a durable option for organizations that need quick deployments and community organizing tools, while the new product line aims to compete more directly for larger campaign requirements.
-
Salsa Labs and EveryAction — Both vendors remain viable choices for nonprofits focused on supporter engagement, fundraising, and canvassing. Their strengths lie in action toolkits and campaign orchestration, with EveryAction’s integration into broader ecosystems offering cross‑product leverage for organizations that prefer vendor ecosystems over point solutions.
-
CiviCRM — As an open‑source option, CiviCRM remains compelling where customization, cost control, and community‑driven development matter most. It is particularly attractive to organizations with internal development capacity or constrained budgets that need CRM and advocacy functionality without vendor lock‑in.
-
Quorum , FiscalNote — These suppliers occupy the public affairs and legislative intelligence niche. Their focus on policy monitoring, stakeholder mapping, and compliance support makes them primary choices for organizations whose advocacy is tightly bound to legislative outcomes. FiscalNote’s application of AI to policy signals faster, higher‑fidelity insights for teams that require real‑time tracking.
-
NGP VAN , Action Network , CallHub — These vendors serve campaign and grassroots mobilization requirements with strengths in political campaign workflows, action tracking, and telephony/canvassing integrations. They remain mission‑critical for high‑tempo campaign environments where rapid supporter activation is the metric of success.
Recent vendor movements and their strategic meaning
-
Blackbaud’s October 2025 unveiling of an AI Agent and an AI Coalition for Social Impact signifies a platform strategy to embed agentic workflows across fundraising, advocacy, and operations. For buyers, this trend means assessing not just feature lists, but the vendor’s roadmap for AI governance, explainability, and embedded compliance.
-
NationBuilder’s January 2026 launch of NationBuilder Engage highlights the competitive race for multi‑channel orchestration and volunteer management. Expect vendors to either broaden horizontal capabilities or double down on deep vertical specialization (e.g., political campaigns vs. nonprofits).
What our full report delivers (practical, implementation‑ready content)
This research is designed as an operational tool for 2026 planning cycles. Key deliverables include:
- Market sizing and forward scenario modeling to support budgeting and portfolio planning.
- Vendor scorecards and a decision matrix tuned for functionality, security posture, AI maturity, and integration cost.
- RFP templates and pilot frameworks that embed privacy, auditability, and data portability clauses.
- Implementation playbooks and change management checklists tailored to advocacy workflows (fundraising-to-action conversion, volunteer mobilization, legislative tracking).
- ROI and TCO models that quantify labor savings from automation, incremental revenue from digital actions, and risk reduction from improved compliance.
- Strategic M&A and partnership maps showing where consolidation and co‑innovation are most likely over the forecast horizon.
Note: while this preview shares the market’s overall trajectory and vendor dynamics, detailed regional and application breakdowns, as well as granular vendor financials and pricing comparisons, are deliberately withheld in this summary to preserve analytical depth for subscribers and buyers who access the full dataset.
Practical 2026 playbook — recommended executive moves
-
Start with a compliance‑first procurement: Require demonstrable GDPR/CCPA controls, incident response SLAs, and anonymization routines in every shortlist. Schedule security proof‑points as part of pilots, not just post‑contract audits.
-
Adopt phased AI pilots with measurable KPIs: Test agentic workflows on constrained use cases (e.g., legislative sentiment tagging, supporter qualification) and measure labor reduction, accuracy, and supporter experience before scaling platform‑wide.
-
Design for composability: Favor platforms that offer modular APIs and prebuilt connectors to CRM, DMP, and analytics stacks. This reduces lock‑in risk and preserves optionality as the market consolidates or new specialist entrants appear.
-
Consolidate where it creates value: For organizations with broad advocacy and fundraising needs, consolidation can reduce integration overhead. For mission‑specific workflows (legislative tracking or high‑tempo campaign ops), maintain specialized suppliers that excel in vertical capabilities.
-
Build a governance and talent plan: Technical capability is necessary but not sufficient. Create cross‑functional teams (legal, IT, comms, program) to oversee vendor governance, content policies, and ethical AI use.
How to use PW Consulting’s research in procurement and M&A
Procurement teams should use our vendor scorecards and pilot templates to convert market insight into contractual advantage — negotiating clear data portability clauses and phased payments tied to delivery milestones. For corporate development and private equity, the report identifies white‑space adjacencies, potential bolt‑on targets, and the valuation implications of AI roadmaps and compliance investments.
Conclusion — strategic value proposition
In 2026, advocacy software is no longer a marginal tool; it sits at the intersection of civic influence, brand reputation, and regulated data custody. Our market study equips executives with the macro view (growth trajectory and concentration dynamics), the competitive context (who leads where and why), and the tactical instruments (RFPs, pilots, governance frameworks) to make confident, defensible decisions. For organizations that must balance rapid supporter activation with privacy and compliance, the next 12–24 months will determine whether advocacy capability becomes a competitive advantage or a source of operational risk.
For a complete breakdown of regional, type, and application sub‑segments, granular vendor comparisons, and the downloadable implementation toolkit, please consult the full PW Consulting Advocacy Software Market report.
For detailed analysis of this topic, please visit the official page: Advocacy Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


